This pervasive myth does a profound disservice to everyday earners. In reality, modern wealth is rarely built through speculative gambles; rather, it is methodically engineered through the slow, unglamorous, and mathematically unstoppable engine of regular monthly investing.
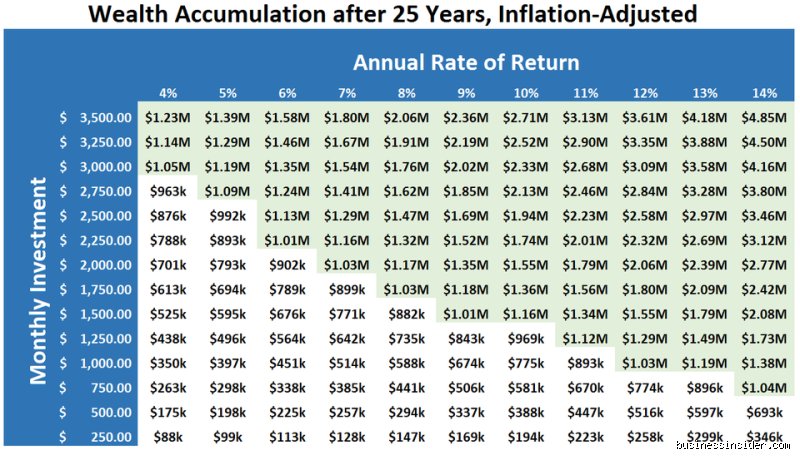
When you ask financial planners how much you need to set aside each month to cross the million-dollar threshold, the standard answer is a frustratingly elusive: “It depends.” It depends on your age, your current savings, your expected rate of return, and—most critically—how many decades or years you are willing to let compound interest work its quiet magic. However, looking at generalized averages reveals a stark truth: becoming a millionaire is far more accessible than most people assume, provided you start early enough to let time shoulder the heaviest burden.
To demystify this process, this first part of our expert analysis breaks down the core mechanics of wealth accumulation, examines the heavy lifting performed by compound interest, and maps out the exact monthly investment commitments required across different life stages.
The Core engine: Understanding the math of compounding
Before looking at specific dollar amounts, we must first look at the underlying mathematical principle that makes wealth creation possible for ordinary wage-earners: compound interest. Albert Einstein reportedly called compound interest the eighth wonder of the world, noting that “those who understand it, earn it; those who don’t, pay it.”
When you invest money in a diversified portfolio of equities, such as broad-market index funds tracking the S&P 500, your money does not simply sit in a vault. It buys fractional ownership in the world's most profitable corporations. These companies generate earnings, reinvest in growth, and distribute dividends. Over long historical horizons, a diversified stock portfolio has delivered an average nominal annual return of roughly 9% to 10%, or about 7% when adjusted for historical inflation.
A 7% annualized return means that your money doubles approximately every ten years. But compounding goes a step further: you earn returns not only on your original principal contributions, but also on all the accumulated returns from previous years.
To visualize this, consider the dramatic difference between simple interest and compound interest over a 30-year horizon:
If you save $753 every month and hide it under your mattress, you will deposit a total of $271,080 over 30 years. That is your absolute ceiling.
If you take that exact same $753 monthly contribution and invest it into a portfolio compounding at an average annual rate of 7%, your total out-of-pocket contributions remain $271,080. However, your final portfolio balance balloons past $1,000,000.
In this scenario, your own savings account funded only about 27% of your milestone. The remaining 73%, over $728,000, was generated entirely by market returns. This is the fundamental secret of wealth generation: at a certain point, your money makes more money than you do through your daily job.
The timeline Factor: Why starting age changes everything
Because compound interest relies exponentially on the variable of time (ttt), the single most important factor determining your required monthly investment is your age when you begin. Time is an asymmetric asset; no amount of high-income earning later in life can fully compensate for losing a decade of early compounding.
To illustrate how drastically time shifts the burden, let us examine what it takes to reach a $1,000,000 portfolio assuming a standard, historically grounded 7% annual rate of return, starting from scratch:
1. The early starter: Beginning at age 25 (40-Year horizon)
If you enter the workforce in your mid-twenties and commit to investing early, the math is remarkably forgiving. To reach $1,000,000 by age 65, you need to invest roughly $319 per month.
Total out-of-pocket contributions: ~$153,000
Growth generated by compounding: ~$847,000 (roughly 85% of your final wealth)
Takeaway: Starting in your twenties requires a modest commitment roughly equivalent to a monthly car payment or dining budget, letting time do 85% of the heavy lifting.
2. The Mid-Career builder: Beginning at age 35 (30-Year horizon)
If life events, education, or early career expenses delay serious investing until your mid-thirties, the required monthly contribution climbs steeply. To hit the millionaire mark by age 65, your monthly target increases to approximately $753.
Total out-of-pocket contributions: ~$271,000
Growth generated by compounding: ~$729,000
Takeaway: Waiting ten years more than doubles your required monthly savings rate because you have eliminated the decade where compounding experiences its steepest exponential acceleration curve.
3. The Late-Starter Catch-Up: Beginning at age 45 (20-Year horizon)
If you start focusing on aggressive wealth accumulation at age 45 with a 20-year runway to retirement at 65, the required monthly investment jumps dramatically to about $1,842.
Total out-of-pocket contributions: ~$442,000
Growth generated by compounding: ~$558,000
Takeaway: At this stage, compound interest still provides more than half of your final total, but you must supply nearly three times the capital out of your monthly paycheck compared to starting at age 25.
The psychological and structural barriers to consistent investing
Knowing the arithmetic is straightforward; executing it in the real world is where most people stumble. Human psychology is notoriously poorly equipped for long-term exponential planning. We naturally think in linear terms, which makes the early years of investing feel discouragingly slow.
During the first five to seven years of a monthly investing plan, your account balance grows primarily because of your own cash deposits. Market gains will feel modest, and routine market corrections can temporarily erase months of contributions. This friction causes many beginners to abandon their strategy, time the market, or halt contributions altogether.
Overcoming this psychological hurdle requires shifting from willpower to automation. Expert wealth-builders do not rely on monthly decisions to invest; they set up automatic transfers that sweep funds from their checking accounts directly into low-cost brokerage or retirement accounts the day after payday. By removing human emotion from the equation, investing becomes as routine as paying rent or utility bills.
This concludes Part 1 of our expert guide. In the upcoming second part, we will explore advanced optimization strategies, including tax-advantaged accounts like 401(k)s and IRAs, navigating inflation adjustments, selecting optimal asset allocations, and managing market volatility without derailing your seven-figure target.
Putting the plan into action: Overcoming common roadblocks
Once you understand the math, the next challenge is execution. Knowing that you need $381, $750, or $1,920 a month is very different from successfully transferring that money out of your checking account every single pay period without fail.
The path to a million dollars is rarely derailed by bad math; it is almost always derailed by behavioral friction, lifestyle creep, and inconsistent habits. To bridge the gap between a spreadsheet projection and real-world wealth, you must build systems that protect your investment strategy from your own impulses.
1. Automate Everything
Willpower is a finite resource. If you rely on manually logging into your brokerage account each month to transfer funds and buy index funds, life will eventually get in the way. You will forget, or you will hesitate during a market downturn and decide to "wait and see."
Set Up Direct Paycheck Splits: Have your employer deposit your designated investment amount directly into a brokerage or retirement account if possible, or schedule an automatic transfer for the exact day after your paycheck lands.
Remove the Decision-Making Process: When investing is treated like an untouchable monthly bill, just like rent, electricity, or insurance, you stop negotiating with yourself about whether you can afford it this month.
2. Defend against lifestyle creep
As your career progresses and your income grows, your natural instinct will be to upgrade your lifestyle: a nicer apartment, a newer car, more frequent dining out. This phenomenon, known as lifestyle creep, is the silent killer of long-term wealth.
The 50% Rule for Raises: Whenever you receive a raise, bonus, or promotion, commit to directing at least 50% of that extra net income straight into your investment accounts before you ever see it in your checking account.
Live Below Your Net Income: By maintaining a stable baseline of living expenses while your earnings scale upward, your monthly investment contributions can increase naturally over time, drastically accelerating your timeline to a million dollars.
Optimizing Your vehicle: Where should Your money Live?
The monthly figures we calculated earlier assume your money is working for you in growth-oriented assets, typically a diversified equity portfolio. Leaving your money sitting in a standard cash savings account will not get you to a million dollars unless your monthly contributions are massive, because inflation and low yields will eat away at your purchasing power.
To maximize your returns while managing risk, you need to leverage the right accounts and asset classes:
| Account Type | Primary Tax Advantage | Best Suited For |
|---|---|---|
| Tax-Advantaged Retirement Accounts (e.g., 401(k), IRA) | Tax-deferred growth or tax-free withdrawals in retirement | Long-term wealth accumulation and retirement milestones |
| Taxable Brokerage Accounts | No early withdrawal penalties; flexible capital gains tax rates | Reaching a million dollars before traditional retirement age |
| Low-Cost Index Funds / ETFs | Broad market diversification with minimal expense ratios | Core equity exposure (e.g., S&P 500 or total world stock funds) |
Keep Fees Low: High management fees can quietly siphon away tens of thousands of dollars over a 30-year horizon. Stick to low-cost index funds or exchange-traded funds (ETFs) where expense ratios are fractions of a percent.
Tax Efficiency Matters: Utilizing tax-advantaged accounts first shields your compounding growth from annual drag, allowing your capital to accumulate much faster than it would in a heavily taxed environment.
The reality check: What million means today vs. Tomorrow
As you look toward your seven-figure goal, it is vital to keep perspective on what that money will actually represent when you arrive. A million dollars is a powerful psychological milestone, but inflation means its purchasing power changes over time.
The Inflation Factor: At a historical average inflation rate of roughly 2.5% to 3%, $1 million thirty years from now will buy significantly less than it does today. If you are starting young with a 30-to-40-year horizon, your actual target for lifestyle parity might need to be higher, or your monthly contributions should scale upward as your earning power increases.
Focus on Income Replacement: Instead of fixating on an arbitrary round number like $1 million, seasoned financial planners often recommend focusing on your projected annual expenses. Using the popular 4% safe withdrawal rule, a $1 million portfolio safely generates roughly $40,000 per year in pre-tax spending. If your desired lifestyle requires more, your target portfolio size, and consequently your monthly investment rate, will need to adjust accordingly.
The first step outweighs the formula
The exact monthly amount you need to invest to become a millionaire depends entirely on your starting age, your timeline, and the returns you secure. If you are 25, a few hundred dollars a month will get you across the finish line. If you are starting later, the required monthly commitment climbs steeply, demanding either higher contributions, a longer career runway, or a more aggressive savings rate.
Yet, obsessing over finding the "perfect" number or waiting for the "ideal" market moment is the most common trap. The market will fluctuate, inflation will shift, and your personal income will change. None of those variables matter as much as the decision to start today.
Compound interest is patient, but it cannot work with zero. Whether your starting number is $100, $500, or $1,500 a month, automating that first transfer turns a theoretical calculation into a lived reality. The million-dollar mark isn't reached by a single massive financial breakthrough; it is built quietly, reliably, one automated month at a time.
Investment Growth Projection