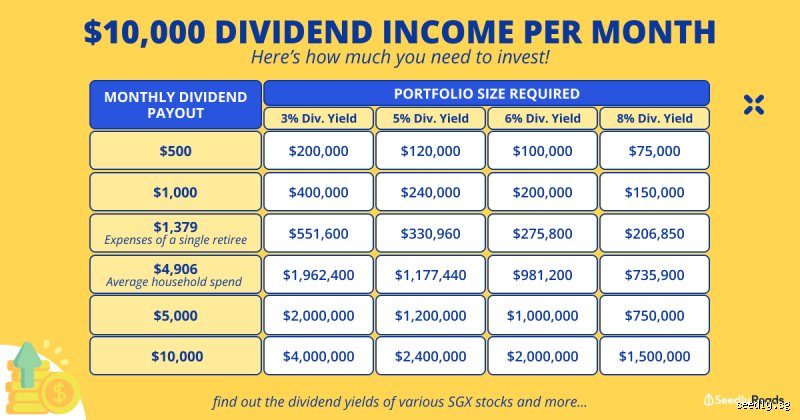
This first part of our comprehensive expert analysis breaks down the core math, explores realistic portfolio yield scenarios based on current market conditions, and evaluates the critical variables that govern sustainable dividend growth.
1. The baseline mathematics: Translating Monthly Income into Capital requirements
To determine the portfolio size needed to generate $10,000 per month, we must first convert the monthly target into an annual figure and apply the fundamental dividend yield formula:
Required Capital=Annual Dividend IncomePortfolio Dividend Yield ext{Required Capital} = \frac{ ext{Annual Dividend Income}}{ ext{Portfolio Dividend Yield}}Required Capital=Portfolio Dividend YieldAnnual Dividend Income
Target Monthly Income: $10,000
Target Annual Income: 10,000×12=$120,00010,000 imes 12 = \$120,00010,000×12=$120,000
The total portfolio value required hinges entirely on the weighted average dividend yield of the assets you hold. Because different investment vehicles offer varying yields, ranging from conservative broad-market indexes to high-yield income funds, the required capital shifts dramatically depending on your asset allocation strategy.
Capital requirement matrix by Portfolio Yield
| Portfolio Dividend Yield | Annual Income Target | Total Principal Required |
|---|---|---|
| 2.0% (Conservative Growth & Dividend Blend) | $120,000 | $6,000,000 |
| 3.0% (Dividend Growth Focus, e.g., established ETFs like SCHD) | $120,000 | $4,000,000 |
| 4.0% (Balanced Income Portfolio) | $120,000 | $3,000,000 |
| 5.0% (High-Yield Equities and REITs) | $120,000 | $2,400,000 |
| 6.0% (Aggressive Income / Closed-End Funds) | $120,000 | $2,000,000 |
As illustrated above, increasing your portfolio's weighted average yield from 3.0% to 5.0% reduces the total principal requirement by a substantial $1,600,000. However, pursuing higher yields introduces structural trade-offs that every investor must carefully evaluate.
2. Analyzing Real-World Yield tiers and market realities
When constructing a portfolio targeting $120,000 annually, relying on a single stock or asset class exposes you to concentration risk. Instead, investors build diversified baskets of assets. Let us examine what different yield tiers look like in practice under prevailing market conditions:
The Low-Yield, High-Growth Tier (1.0% to 2.0%): Broad market benchmarks, such as the S&P 500, historically hover around a dividend yield of roughly 1.0% to 1.5%. While a $4,000,000 to $6,000,000 portfolio is required to pull $10,000 a month directly from these yields alone, these portfolios typically benefit from superior capital appreciation and aggressive dividend growth over time. Companies in this category often reinvest a large portion of their earnings into expansion rather than immediate payouts.
The Moderate Dividend Growth Tier (2.5% to 3.5%): Dividend-focused exchange-traded funds (such as the Schwab U.S. Dividend Equity ETF, which yields approximately 2.99%) or portfolios of mature Dividend Aristocrats sit comfortably in this bracket. Requiring a principal between $3,428,571 (at 3.5%) and $4,000,000 (at 3.0%), this tier strikes a balance between reliable current income and inflation-hedging capital growth.
The High-Yield Income Tier (4.5% to 6.0%+): Focused utility stocks, telecommunications, select Real Estate Investment Trusts (REITs), and fixed-income instruments can push portfolio yields higher. At a 5% yield, the target principal drops to $2,400,000. However, high nominal yields often correlate with slower underlying business growth, higher sensitivity to interest rate fluctuations, or elevated structural risk (often referred to in finance as a "yield trap").
3. Pre-Tax vs. Post-Tax realities: The hidden impact of taxes
A critical error many aspiring dividend investors make is calculating their required capital using gross (pre-tax) income figures. In taxable brokerage accounts, dividends are categorized either as qualified dividends (taxed at preferential long-term capital gains rates of 0%, 15%, or 20% depending on your taxable income bracket) or ordinary dividends (taxed at higher ordinary income tax rates, common with REITs and certain fixed-income funds).
If your goal is to net $10,000 per month in spendable cash ($120,000 per year) after taxes, your gross portfolio income must be higher.
Illustrative Tax impact scenario
Assuming a moderate household tax profile where your dividend income faces an effective blended tax rate of 15%:
Net Annual Cash Needed: $120,000
Effective Tax Rate: 15%
Gross Annual Income Required:
Gross Income=$120,0001−0.15=$120,0000.85≈$141,176.47 ext{Gross Income} = \frac{\$120,000}{1 - 0.15} = \frac{\$120,000}{0.85} \approx \$141,176.47Gross Income=1−0.15$120,000=0.85$120,000≈$141,176.47
Applying this gross target of $141,176.47 to a 4.0% yielding portfolio shifts the required principal:
Required Capital=$141,176.470.04=$3,529,411.76 ext{Required Capital} = \frac{\$141,176.47}{0.04} = \$3,529,411.76Required Capital=0.04$141,176.47=$3,529,411.76
Failing to account for taxes means your net monthly take-home pay would fall significantly short of the $10,000 target, netting closer to $8,500 instead. Utilizing tax-advantaged accounts like Roth IRAs (where eligible) or traditional retirement accounts can alter this math, though withdrawal rules and contribution limits apply.
4. The power of Dividend Growth and inflation protection
Generating $10,000 a month today is only half the battle; maintaining the purchasing power of that $10,000 over a 10- to 20-year retirement horizon requires addressing inflation.
If inflation averages 2.5% per year, the purchasing power of $10,000 monthly will erode significantly over time. To combat this, smart dividend investing relies heavily on dividend growth investing (DGI) rather than chasing static high yields.
Key Financial Principle: A company yielding 3.0% that grows its dividend by 8% annually will rapidly outpace a stagnant company yielding 5% whose payout remains flat. Over time, your yield on cost, the annual dividend divided by your original purchase price, compounds exponentially.
In Part 2 of this expert analysis, we will explore practical asset allocation strategies, step-by-step accumulation roadmaps, and the exact blueprint for transitioning from an active accumulation phase to a fully funded dividend income stream.
Building Your strategy: Balancing Yield and Capital preservation
When targeting a substantial passive income stream like $10,000 a month ($120,000 annually), the biggest trap investors fall into is chasing raw yield. It is easy to look at closed-end funds (CEFs), business development companies (BDCs), or covered-call ETFs yielding 10% to 12% and assume you only need roughly $1,200,000 to reach your goal. However, ultra-high-yield strategies often come with hidden structural risks, including capital erosion, lack of dividend growth, and high sensitivity to market downturns.
A sustainable, expert-level portfolio construction relies on a blended approach. By combining core dividend growth assets with moderate-yield income generators, you can protect your principal while hitting your monthly cash flow targets.
Sample Portfolio allocations for ,000/Month
To visualize how different risk tolerances impact the capital required, consider three distinct portfolio archetypes:
1. The Conservative Growth & Income approach (4.5% blended Yield)
Required Capital: ~$2,666,000
Core Holdings: Dividend Aristocrats, blue-chip stocks, and broad dividend growth ETFs (e.g., SCHD, VIG).
Characteristics: Prioritizes annual dividend increases that outpace inflation. While you need more upfront capital, your payouts will organically grow year over year without requiring additional contributions.
2. The Balanced hybrid approach (6.5% blended Yield)
Required Capital: ~$1,846,000
Core Holdings: A mix of dividend growth ETFs, select BDCs, and options-based income funds (e.g., JEPI, JEPQ).
Characteristics: Strikes a balance between immediate cash flow and capital appreciation. This is often the sweet spot for investors transitioning into early retirement who want robust monthly checks without sacrificing total portfolio health.
3. The Aggressive Income approach (9.0% blended Yield)
Required Capital: ~$1,333,000
Core Holdings: High-yielding preferred shares, real estate investment trusts (REITs), and specialized high-payout funds.
Characteristics: Maximizes immediate liquidity with significantly less starting capital, but demands active monitoring. Principal volatility is higher, and the risk of a dividend cut during a macro shock is elevated.
The hidden impact of taxes
Gross income is rarely net income. Depending on whether your portfolio is held in a taxable brokerage account or tax-advantaged vehicles like a Roth IRA or traditional IRA, taxes will heavily dictate your timeline:
Qualified Dividends: In taxable accounts, qualified dividends benefit from preferential long-term capital gains tax rates (0%, 15%, or 20% federally, depending on your income bracket).
Ordinary Dividends & Distributions: REIT distributions, certain foreign dividends, and distributions from options-heavy ETFs are often taxed at ordinary income tax rates, which can significantly dent your monthly cash flow.
To net a clean $10,000 monthly after taxes, a taxable account investor may actually need to target a gross income of $12,500 to $14,000 a month, shifting the required capital requirement upward accordingly.
Action Plan to reach Your goal
Building a five-figure monthly dividend engine rarely happens overnight. Execution requires a disciplined, step-by-step framework:
Calculate Your Personal Target: Determine your exact net monthly goal after accounting for your local tax jurisdiction and expected inflation.
Establish the Core Foundation: Build your initial capital base using broad-market growth assets or low-cost dividend appreciation funds before tilting toward high-yield vehicles.
Automate Reinvestment (DRIP): During your accumulation phase, keep the Dividend Reinvestment Plan active to leverage the power of compounding interest. Turn DRIP off only when you are ready to live off the cash flow.
Diversify Across Sectors: Ensure your income isn't tied to a single industry. Balance financials, healthcare, consumer staples, technology, and alternative income sources to withstand sector-specific downturns.