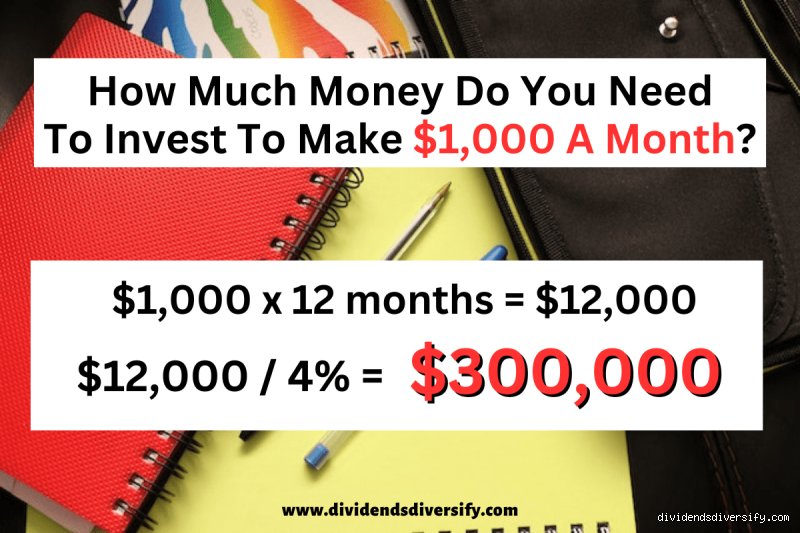
Understanding the math behind your financial independence goals
not even close when assuming a flat 4% withdrawal rate solves everything. The trouble is that the macroeconomic climate in 2026 looks vastly different from the low-interest-rate playground of the 2010s. Because of that, your target principal fluctuates wildly.
The baseline principal requirements
Generating twelve thousand dollars annually demands a hard look at yield curves (which explains why veterans scoff at novice expectations). If you park cash in high-yield savings accounts yielding 4.5% in early 2026, you require precisely $266,666 to hit your target. But that number shifts the moment yields drop.
Why historical averages lie
The catch: the stock market rarely returns a smooth 8% year over year. Sequence of returns risk can completely eviscerate a portfolio in its infancy. As a result, relying on a static calculator in downtown Chicago or suburban London is practically a coin toss.
Dividend stocks versus real estate syndications for monthly cash flow
Equities offer liquidity, whereas brick-and-mortar investments offer tangible leverage—that makes a real difference. I personally find pure dividend investing dreadfully boring, yet the safety net it provides is undeniable. Opinions are split on whether REITs outperform traditional blue-chip aristocrats like Procter & Gamble or Johnson & Johnson, and it's unclear who holds the winning hand.
Building a reliable dividend portfolio
To secure $1000 a month exclusively from dividend payers yielding 3.5%, your capital outlay sits right around $342,000. Companies residing in the S&P 500 distribute cash quarterly, meaning you have to manually budget for those dry months. The hard part is managing dividend cuts during a recession.
Private credit and alternative yield vehicles
Private debt funds operating out of New York have recently pushed yields toward 9%. But higher returns introduce severe counterparty risk. If a borrower defaults on a commercial bridge loan originated in October 2024, your monthly distribution vanishes overnight.
Peer-to-peer lending and high-yield instruments compared
Retail investors often chase alternative platforms hoping to bypass traditional market friction. Yet default rates on unsecured consumer loans spiked significantly across platforms like Prosper and European equivalents over the past two years. In short, chasing double-digit yields usually invites catastrophic downside.
Assessing liquidity trade-offs
Tying up funds in a real estate fund locked for five years is completely different from buying liquid ETFs on Robinhood. You sacrifice peace of mind for extra basis points. And because transaction costs eat early gains, your net cash flow might barely clear $800 after fees.
Weighing traditional equities against alternative digital assets
Staking stablecoins on decentralized finance protocols can yield upwards of 6% to 12%, though regulatory crackdowns loom large. Traditional index funds tracking the total stock market remain the gold standard for long-term compounding, despite their lower initial cash distributions. Which path you choose ultimately depends on your stomach for sudden drawdowns.
The hidden tax burden on monthly income
Ordinary income taxes will bite heavily into your monthly distributions unless sheltered inside tax-advantaged accounts like a Roth IRA or a UK ISA. If you net $1000 a month in a taxable brokerage account, Uncle Sam might take 15% to 24% right off the top, forcing you to boost your initial investment target by at least $50,000 to compensate.
Mistakes people make
Chasing unrealistic yields
People often believe a high-yield investment can double overnight. Yet, greed blinds operators to severe market risks. As a result, accounts vanish before lunch. You need to invest to make $1000 a month through steady compounding rather than reckless speculation. The problem is that social media feeds are flooded with fake gurus selling overnight wealth.
Ignoring hidden fees and taxes
Many beginners forget that broker commissions and capital gains tax take a massive bite out of profits. This is why a portfolio generating exactly twelve thousand dollars annually on paper falls short in reality. You might hit your gross target, but Uncle Sam always wants his cut. (Always keep a cash cushion for unexpected liabilities.)
Putting all eggs in one basket
Concentration builds wealth, but diversification preserves it. The problem is that novices dump their entire savings into a single volatile asset. When that sector drops, panic sets in. You must spread your capital across different asset classes to protect your principal.
One thing people overlook
The liquidity trap
Real estate and private equity look great on spreadsheets. But try withdrawing cash quickly when an emergency strikes. You cannot pay rent with an illiquid deed. Having passive income strategies means nothing if your funds are locked for a decade. Experienced operators always maintain a liquid emergency fund alongside their income-generating assets.
Frequently asked questions
Is 0,000 enough to generate ,000 a month consistently?
A principal of $100,000 requires a steady 12 percent annual return to hit your target. This level of performance demands exposure to riskier equities or high-yield corporate bonds. Yet, achieving this sustainably year after year without a major drawdown is exceptionally difficult. Market conditions fluctuate, meaning your monthly payouts will likely swing up and down rather than arriving like a predictable paycheck.
Can dividend stocks alone achieve this financial goal safely?
Dividend investing remains a popular path for generating regular cash flow without selling underlying shares. To secure $1,000 monthly using a reliable 4 percent average dividend yield, you need a total portfolio value of roughly $300,000. Because blue-chip companies rarely pay out massive yields safely, scaling this up takes patience and continuous capital injection. You are trading higher required capital for lower active stress.
How does inflation destroy a fixed monthly income target?
Inflation silently erodes the purchasing power of your hard-earned cash over time. If you lock into fixed-income instruments paying a flat rate, a loaf of bread that costs five dollars today might cost eight dollars in a few years. Consequently, your nominal goal of $1,000 will buy significantly less goods and services down the road. You must factor in growth-oriented assets to outpace rising consumer prices.
Our take
Anyone whispering that generating passive income requires zero effort is selling a fantasy. The journey demands relentless discipline, ironclad risk management, and thousands of dollars in upfront capital. We must stop treating the stock market like a casino and start viewing it as a long-term business. In short, your financial freedom is entirely a math problem waiting for you to solve it.