The Allure of Four Figures
We have all stared at the glowing spreadsheets, tracing a crooked line toward the holy grail of personal finance: the passive four-figure monthly payout. Earning $1,000 a month in dividends feels like the ultimate economic boundary layer, the invisible wall separating wage slavery from genuine financial autonomy. Yet, the math behind this milestone is rarely discussed with the brutal honesty it demands.
Deconstructing the Yield Reality
What if I told you that the standard advice circulating across financial blogs is dangerously incomplete? Because chasing an arbitrary monthly cash flow without accounting for portfolio decay is like trying to fill a bucket with a massive hole in the bottom, the entire premise deserves a rigorous teardown.
The Core Mathematics of Dividend Income
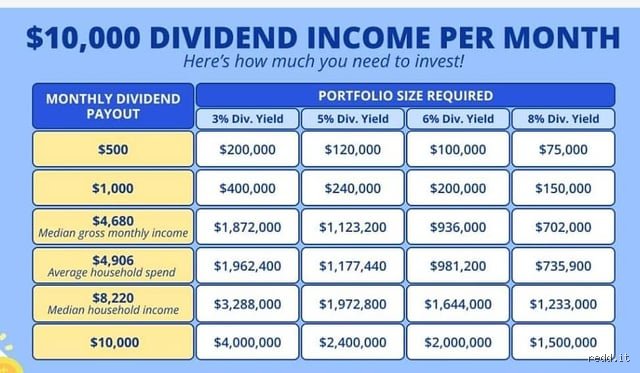
To generate $1,000 every single month, you need an annual cash return of $12,000. How much capital does that require? The answer relies entirely on your blended portfolio yield, which explains why two investors with identical net worths can experience wildly different lifestyles.
The Yield Spectrum and Capital Requirements
At a conservative 3.0% yield: You require $400,000 invested.
At a moderate 4.5% yield: You require approximately $266,667 invested.
At an aggressive 6.0% yield: You require $200,000 invested.
Except that chasing higher yields almost always introduces hidden structural risks, which experts disagree on, and honestly, it's unclear whether high-yield traps ultimately outpace steady dividend growth over a twenty-year horizon.
Challenging Conventional Wisdom
Conventional wisdom insists that you simply buy a basket of blue-chip dividend aristocrats, set your brokerage account to auto-pilot, and wait for the checks to clear. But this rosy narrative completely ignores the corrosive erosion of inflation and the heavy tax drag on taxable accounts. (Furthermore, corporate payout ratios fluctuate wildly during macroeconomic downturns, meaning your safe harbor can instantly spring leaks when you least expect it.)
The Hidden Drag of Taxes and Inflation
And when you factor in capital gains taxes, dividend taxes, and the creeping cost of everyday goods, that $1,000 in nominal dollars buys significantly less purchasing power five years down the road. As a result: the gross amount you calculate today must be adjusted upward if you want your real lifestyle to remain insulated from economic shocks.
Navigating the Trade-Offs
When building a cash-flowing portfolio, you face a permanent trilemma: safety, growth, and current yield. You can pick any two, but you cannot maximize all three simultaneously. Hence, the investor who prioritizes immediate monthly income often sacrifices the long-term capital appreciation needed to fight inflation.
In short, crossing the $1,000-a-month threshold is less about finding a secret high-yield stock and more about understanding the sheer volume of capital required to make simple math work in your favor.
What specific dividend yield are you currently targeting for your own portfolio, and how are you planning to bridge the gap to reach your target capital?
The Power of Dividend Growth and Reinvestment
While upfront capital requirements give you a clear destination, very few investors start with hundreds of thousands of dollars ready to deploy.
When companies increase their payouts annually—a hallmark of Dividend Aristocrats and established blue-chip firms—your "yield on cost" rises. For example, if you purchase a stock at a 3% yield and the company increases its dividend by 6% each year, your effective yield on your original purchase price compounds significantly over a 10-to-15-year horizon. Combined with regular monthly contributions, this dynamic shrinks the total out-of-pocket capital needed to hit your $1,000-per-month ($12,000-per-year) milestone.
Strategic Frameworks for Portfolio Construction
Structuring a portfolio to generate reliable cash flow requires balancing high yield against capital preservation. Relying solely on ultra-high-yielding assets can expose you to value traps or stagnant underlying businesses. Consider these core pillars when executing your strategy:
Diversification Across Sectors: Avoid concentration risk by spreading investments across resilient sectors such as consumer defensives, healthcare, utilities, and financial services.
Focus on Payout Ratios: Prioritize companies with sustainable payout ratios (typically under 75% for most industries).
This ensures the business retains enough capital to reinvest in growth and weather economic downturns without cutting distributions. Core-Satellite Approach: Build a foundation using broad-market dividend exchange-traded funds (ETFs) for stability, supplemented by individual blue-chip equities to optimize your blended yield.
Managing Tax Efficiency and Account Types
The tax treatment of your dividends can dramatically alter your net take-home cash flow. Where you hold your assets matters just as much as what you buy:
Tax-Advantaged Accounts (IRAs and Roth IRAs): Utilizing tax-deferred or tax-free accounts shields your dividend distributions from immediate taxation, allowing your cash flow to compound unhindered. In a Roth IRA, qualified withdrawals later in life are entirely tax-free.
Taxable Brokerage Accounts: Dividends received in standard accounts are categorized as either qualified (taxed at lower capital gains rates) or unqualified (taxed as ordinary income). If you are building wealth outside of retirement accounts, keeping an eye on tax drag is essential for maintaining your monthly target.
Accelerating Your Timeline
Reaching $1,000 a month is a major milestone that transforms your relationship with money, providing a tangible cushion for essential living expenses.