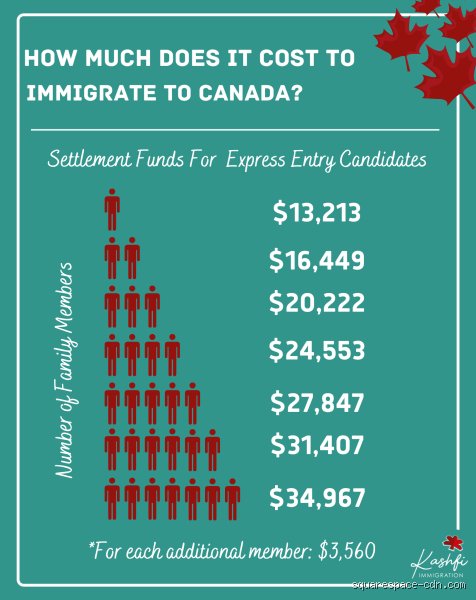
When people talk about moving to Canada, the conversation almost always drifts toward the glittering skyscrapers of Toronto, the stunning mountain backdrops of Vancouver, or the quiet, community-driven charm of the Maritimes. We talk about healthcare, the polite locals, and the snow. But we rarely talk about the brutal, unromantic math that sits quietly at the center of the entire enterprise.
Official government websites will give you a neat, tidy number. They will hand you a schedule of fees, a minimum-funds threshold for Express Entry, and a polite checklist. If you follow those numbers blindly, you are setting yourself up for a very rude awakening. I firmly believe that the Canadian immigration system's published financial requirements are less of a safety net and more of a cruel joke designed for people who have never tried to rent an apartment in a major Canadian city.
Let’s be honest right from the start: the official financial requirement is a floor, not a ceiling. Treating it like a budget is like packing a light windbreaker for a blizzard because the weather app said it was going to be "chilly."
The Official Numbers vs. Ground Zero Reality
To understand the gap between theory and practice, we have to look at what Immigration, Refugees and Citizenship Canada (IRCC) actually asks for under the federal skilled worker streams.
If you are applying as a single applicant through Express Entry without a valid job offer, the government currently requires you to show proof of a specific amount of funds based on the size of your family. For a single person, that baseline sits around $14,000 to $15,000 CAD. For a couple, it scales up. On paper, it sounds manageable. It feels like an attainable savings goal that you can chip away at over a couple of years of disciplined living.
Here is where the nuance contradicts the conventional wisdom: those funds are not meant to be spent on your relocation. They are proof of settlement funds—money you must possess to prove you won't immediately require social assistance. But try telling a landlord in downtown Toronto or Vancouver that you plan to live off $14,000 CAD for months while you look for work. That money will evaporate before you even unpack your winter coats.
Between the mandatory immigration fees, biometrics, language tests, educational credential assessments (ECAs), medical exams, and police certificates, a single applicant can easily drop $2,000 to $4,000 CAD before they even pack a single bag. And that is before you buy a single plane ticket.
The Upfront Paperwork Toll: Where Your Savings Bleed First
Before you can even throw your hat into the immigration ring, you have to pay the gatekeepers. This is the invisible tax of dreaming about a new life. Every single document must be verified, translated, tested, and stamped.
Language Tests: Whether you take IELTS General or CELPIP, testing fees are non-negotiable. If you need to retake the test to bump your Canadian Language Benchmark (CLB) score up by a single point—which can make or break an Invitation to Apply (ITA)—you are paying again.
Educational Credential Assessments (ECAs): Organizations like World Education Services (WES) need to look at your foreign university degree and decide what it's worth in Canadian terms. It is an administrative toll booth that you cannot bypass.
Medical Exams and Police Checks: Canada wants to know that you are healthy and law-abiding. Panel physicians and local police departments charge hefty fees for these certificates, and they usually have an expiration date, meaning if your processing time drags out, you might have to pay for them twice.
It is genuinely unclear why the processing fees are structured the way they are, with separate fees for processing and right of permanent residence, other than to extract maximum revenue from hopeful applicants. Experts disagree on whether these fees will stabilize or continue to climb with inflation, but history suggests the only direction they move is up.
The Housing Crisis and the Cost of Landing
Once you clear the paperwork hurdle and actually get your confirmation of permanent residence (COPR), the real financial pressure cooker begins. You land at the airport, clear customs, and step out into a housing market that is currently undergoing one of its most volatile and expensive eras in modern history.
If you arrive thinking you can secure a long-term rental from abroad without credit history, a local job, or a Canadian guarantor, you are in for a humbling experience. Most landlords in competitive markets will look right past your foreign credentials and ask for first and last month's rent, plus proof of employment. Many newcomers are forced into expensive short-term rentals or Airbnb units for their first month or two, which can drain thousands of dollars in weeks.
Furthermore, setting up a basic household—even if you buy everything second-hand—adds up fast. Matteds, kitchenware, utilities deposits, mobile phone plans, internet setup, and winter clothing that can actually withstand a Canadian January will systematically dismantle your savings account. A light winter jacket from your home country will not cut it when the wind chill drops below minus twenty. You need proper layers, heavy-duty boots, and thermal gear, all of which command a premium price tag in local retail stores.
The Job Market Paradox
You might think, "I'll just find a job immediately." And yes, Canada has pockets of incredible labor demand, particularly in healthcare, trades, and specialized tech fields. But the silent trap that catches many high-skilled immigrants is the Canadian experience paradox.
You arrive with a stellar resume, years of international management or engineering experience, and quiet confidence. Then you start applying. You quickly realize that many employers value local Canadian experience above almost everything else. Getting your foot in the door can take anywhere from three months to over a year, depending on your sector, your networking hustle, and how heavily regulated your profession is.
If you are an engineer, an accountant, or a lawyer, you cannot simply start practicing the day you land. You will likely need to go through licensing bodies, write professional exams, and pay association dues. During this transition period, your savings are your only lifeline. If you arrive with only the bare minimum required by the government immigration guidelines, you are walking a tightrope without a safety net, praying that a stiff economic wind doesn't blow you off balance.
Navigating Hidden Costs and Post-Arrival Financial Realities
While meeting Immigration, Refugees and Citizenship Canada (IRCC) baseline settlement funds—such as approximately CAD $15,263 for a single applicant or CAD $28,362 for a family of four—is mandatory for programs like the Federal Skilled Worker Program, these figures only scratch the surface of what a successful transition actually demands.
Phase 1: Government Processing and Administrative Outlays
Before you ever pack a suitcase or book a flight, the bureaucratic pathway to permanent residency demands a steady stream of capital. These mandatory fees are separate from your settlement funds and must be paid directly in Canadian Dollars (CAD) or equivalent currency through official channels:
Language Testing: General training tests like IELTS or CELPIP for English, or TEF/TCF for French, typically range from CAD $300 to $450, depending on your testing center and location.
Educational Credential Assessment (ECA): Having your foreign degrees and diplomas evaluated by designated organizations (such as WES Canada) generally costs between CAD $200 and $350, plus international courier fees.
Government Application & Permanent Residence Fees: Express Entry processing fees sit at roughly CAD $950 per adult, alongside the Right of Permanent Residence Fee (RPRF) of CAD $575 per adult.
Including dependent children adds approximately CAD $260 per child. Biometrics and Medical Exams: Expect to pay roughly CAD $85 per person (or CAD $170 for a family) for biometric collection, while panel physician medical examinations range from CAD $200 to $500 per person based on local clinic rates.
Phase 2: The Critical First 90 Days Post-Arrival
The moment you land in Canada, your settlement funds will be heavily tested before your first paycheck arrives. Experienced newcomers quickly realize that the official IRCC thresholds are tight baselines rather than comfortable cushions. Your initial three-month budget should anticipate the following high-impact expenses:
Phase 3: Mitigating Common Financial Pitfalls
Immigration applications face intense financial scrutiny from visa officers. To avoid devastating delays or refusals, keep these regulatory rules in mind:
The "No Borrowed Money" Rule: IRCC explicitly forbids using borrowed cash, personal loans, or lines of credit to satisfy proof-of-funds mandates.
Every dollar must be unencumbered, fully liquid, and legally accessible. Scrutiny of Sudden Deposits: If a large lump sum appears in your bank account shortly before your application, officers will demand a verifiable paper trail. Sudden, unexplained windfalls without a formal Gift Deed or asset-sale documentation frequently trigger administrative refusals.
The Currency Fluctuation Buffer: Because exchange rates shift daily, holding your savings right at the absolute minimum threshold is a dangerous game.
A sudden drop in your home currency's value against the CAD can render your profile non-compliant overnight. Always maintain a safety buffer of at least CAD $2,000 to $3,000 above the legal minimum.
Final Strategic Advice
Imigrating to Canada is as much an economic investment as it is a life change. By building a realistic financial buffer that covers administrative processing, rigid banking guidelines, and a comfortable 3-to-6-month domestic runway, you protect your family from early vulnerabilities and position yourselves for long-term prosperity in the Canadian market.
What specific immigration stream or province are you targeting for your move, and would you like a customized breakdown of regional living costs for that area?