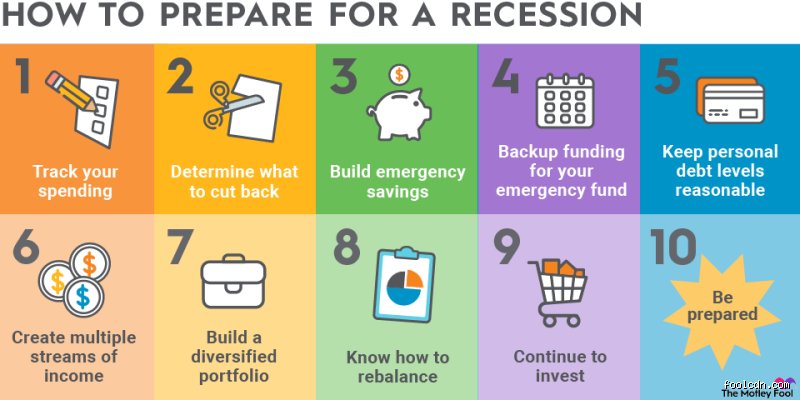
When consumer spending contracts, corporate earnings compress, credit markets tighten, and unemployment figures tick upward, asset classes do not behave uniformly. High-flying, speculative growth equities that relied heavily on cheap capital and future promises often experience severe valuation contractions. Conversely, specific defensive categories of assets tend to demonstrate remarkable durability, preserving capital, generating consistent cash flows, and occasionally even appreciating as frightened capital flees risky environments.
Understanding which assets survive—and even thrive—during a recession requires a nuanced examination of corporate fundamentals, macroeconomic behavior, structural liquidity, and the timeless principles of modern portfolio risk management.
The anatomy of a recession: Understanding market stress
To effectively identify which assets can weather a macroeconomic contraction, one must first understand the structural pressures that a recession exerts on the financial ecosystem. A recession is officially defined as a significant decline in economic activity spread across the economy, lasting more than a few months, normally visible in real GDP, real income, employment, industrial production, and wholesale-retail sales.
As corporate revenues slow down due to a broad-based drop in consumer and business demand, companies face a severe test of their operational and financial resilience. Firms saddled with excessive leverage and floating-rate debt find themselves crushed under mounting interest expenses at the exact moment their top-line revenue is shrinking. Consequently, equity markets routinely reprice risk downward, punishing overextended enterprises and punishing cyclical sectors, such as discretionary consumer goods, heavy industrial manufacturing, and high-beta technology, while bidding up safe havens.
For the individual investor or wealth manager, navigating this environment requires moving away from the "growth-at-all-costs" mentality that characterizes bull markets. Instead, attention must pivot toward three foundational pillars of recession survival: intrinsic utility, pristine balance sheets, and non-correlated cash flows. Assets that possess these attributes form the bedrock of any defensive portfolio strategy.
Pillar I: Defensive equities and the Power of inelastic Demand
While equities are generally viewed as risk assets, not all stocks are created equal. During an economic contraction, institutional capital routinely rotates out of cyclical growth plays and into defensive sectors, industries characterized by inelastic demand. Inelastic demand means that consumers will continue purchasing these goods and services regardless of whether the broader economy is expanding or contracting.
1. Consumer staples: The ultimate household defense
When household budgets tighten, families rapidly cut back on luxury vacations, high-end dining, brand-name apparel, and major discretionary purchases. However, they do not stop buying groceries, toothpaste, basic cleaning supplies, and essential hygienic products.
Companies operating within the consumer staples sector, such as mega-cap household product manufacturers, major global beverage brands, and discount warehouse retailers, exhibit extraordinary resilience during downturns. Elite consumer staples companies often possess strong "pricing power". This is the rare ability to raise prices to offset input cost inflation without experiencing a catastrophic loss of market share. Because their products are fundamental to daily survival, consumers absorb the minor price increases rather than forgoing the items entirely. This dynamic protects corporate profit margins even when the macro environment turns hostile.
2. Healthcare and pharmaceuticals: Essential medical needs
The healthcare sector represents another classic defensive bastion. Medical treatments, pharmaceutical prescriptions, surgical procedures, and essential health insurance coverage cannot be indefinitely deferred based on the state of the business cycle.
Demographic tailwinds, such as an aging global population, further insulate healthcare systems from acute economic shocks. Within this sector, large pharmaceutical firms with diversified drug pipelines, medical technology giants, and essential healthcare service providers typically maintain steady revenue streams. Even if elective medical procedures experience temporary dips, critical care and maintenance medications ensure a high baseline of continuous cash generation.
3. Utilities: Regulated monopolies and predictable cash flows
Electricity, water, and natural gas are modern necessities. Consumers may turn down their thermostats or turn off unused lights to shave a few dollars off their monthly bills, but basic utility consumption remains remarkably stable through recessions.
Utility companies frequently operate as regulated monopolies within their geographic footprints, granting them legally protected operating environments with predictable, stable cash flows. Because of this cash-flow visibility, utility firms traditionally pay reliable, above-average dividend yields. During market downturns, income-seeking investors frequently flood into utility stocks for safety, helping support their valuations while broader equity indexes experience steep declines.
Pillar II: Fixed income and the flight to quality
As equities experience heightened volatility and downside pressure, capital historically migrates toward fixed-income instruments. However, navigating the bond market during a recession requires careful calibration of duration, credit quality, and macroeconomic conditions.
Sovereign debt and High-Grade Government Bonds
Government-issued securities, particularly short-to-intermediate-duration benchmark treasuries, are widely regarded as the ultimate safe-haven asset during acute financial panics. When private sector risk explodes, institutional investors accept lower yields in exchange for the absolute guarantee of principal repayment backed by the issuing government.
As economic growth slows, central banks frequently respond by cutting benchmark interest rates to stimulate borrowing and investment. Falling interest rates cause existing fixed-rate bonds with higher coupons to appreciate in secondary market value, providing capital gains that can offset equity losses in a diversified portfolio.
Investment-Grade corporate credit vs. High-Yield debt
While sovereign bonds offer maximum safety, high-quality investment-grade corporate bonds provide an attractive middle ground, delivering higher yields while maintaining strict balance-sheet standards. Conversely, high-yield (or "junk") corporate bonds often experience severe distress during recessions. When speculative-grade companies face tightening credit markets and declining revenues, default rates spike, causing high-yield debt instruments to suffer equity-like drawdowns. Consequently, risk-conscious asset allocators systematically upgrade the credit quality of their fixed-income holdings ahead of expected economic contractions.
(This concludes Part I of our comprehensive analysis. In the upcoming sections, we will explore the roles of real assets, commodities, precious metals, strategic liquidity buffers, and behavioral discipline in constructing an impenetrable, recession-resistant portfolio framework.)
Navigating the economic downturn: The definitive Asset playbook
As economic cycles inevitably shift, the specter of a recession looms large over global markets. For investors, the critical question is no longer if a contraction will occur, but how to position capital to not only survive the storm, but emerge with purchasing power intact. While speculative growth assets often capture the headlines during economic expansions, market contractions ruthlessly punish over-leveraged businesses and volatile valuations.
Building a truly recession-resilient portfolio requires a disciplined transition toward assets anchored in fundamental utility, structural demand, and robust cash flows. Below is the continuation and strategic conclusion of the framework for identifying the assets capable of surviving, and thriving through, a severe economic downturn.
III. The inelastic Demand engine: Consumer staples and healthcare
When consumer discretionary spending contracts under the weight of job insecurity and tighter credit conditions, businesses relying on impulse purchases experience severe revenue compression. Conversely, assets tied to absolute human necessities exhibit remarkable top-line stability.
1. Global consumer staples giants
Consumers may trade down from premium brands to private-label alternatives, but they do not stop purchasing basic household goods, hygiene products, and essential foodstuffs.
Pricing Power: The hallmark of a recession-surviving staple stock is its pricing power, the ability to pass input cost inflation onto consumers without triggering a catastrophic drop in unit volume.
Balance Sheet Strength: Elite consumer staple corporations maintain low debt-to-equity ratios and long-standing histories of consistent, multi-decade dividend growth. These cash distributions provide a vital total-return cushion when equity price appreciation stalls.
2. Healthcare and medical Infrastructure
Medical treatments, essential pharmaceuticals, and device manufacturing operate largely independently of economic cycles.
Secular Tailwinds: Beyond pure recession resistance, the healthcare sector benefits from long-term demographic trends, such as aging populations in developed economies, ensuring continuous baseline demand.
Defensive Defensive Growth: Diversified healthcare conglomerates and pharmaceutical leaders with entrenched pipelines often combine defensive earnings predictability with low historical correlation to broader equity market sell-offs.
IV. Real assets, Infrastructure, and commodities as hard hedges
In modern economic environments where recessions can occasionally overlap with lingering inflationary pressures (stagflationary impulses), traditional financial assets alone may fall short. Hard assets provide a physical and structural floor against currency devaluation and supply chain friction.
+-----------------------------------------------------------------+
THE HARD ASSET DEFENSIVE SPECTRUM
+-----------------------+-----------------------------------------+
| Asset Class | Primary Recessionary Function |
+-----------------------+-----------------------------------------+
| Essential Utilities | Regulated cash flows, high dividend |
| | yields, non-discretionary demand. |
+-----------------------+-----------------------------------------+
| Critical Infrastructure| Long-term contracted cash flows, |
| (Data/Logistics) | inflation-linked revenue models. |
+-----------------------+-----------------------------------------+
| Precious Metals (Gold)| Neutral store of value, ultimate |
| | systemic risk and fiat hedge. |
+-----------------------+-----------------------------------------+
1. Regulated Utilities
Demand for electricity, water, and gas services remains steady regardless of macro volatility. Because utility providers often operate under state-regulated monopolies or quasi-monopolies, their revenue streams are insulated from open-market pricing wars. Their predictable cash generation allows them to maintain attractive dividend yields, making them a primary destination for capital fleeing riskier sectors.
2. Specialized real estate and Infrastructure
Not all real estate fares equally during a downturn. While office and discretionary retail spaces may face occupancy pressures, specialized infrastructure, such as data centers, logistics hubs, cell towers, and cold-storage facilities, relies on long-term, mission-critical leases. These assets often feature built-in inflation escalators, protecting investor yields even as economic growth slows.
3. Gold and Precious Metals
As a time-tested, neutral store of value, gold historically performs well during periods of systemic financial stress, geopolitical fragmentation, or diminished confidence in fiat currencies. It carries no counterparty risk and acts as ultimate portfolio insurance when equity-bond correlations break down.
V. Strategic fixed income and the Liquidity buffer
Cash and short-duration fixed income play a dual role in a recessionary survival plan. While cash can be a drag during high-inflation periods if held in excess, maintaining a dedicated liquidity buffer is essential to prevent becoming a "forced seller" of risk assets during a market bottom.
High-Quality Government and Investment-Grade Bonds: Intermediate-duration sovereign bonds and high-grade corporate issues tend to rally as central banks pivot toward monetary easing to combat economic cooling. They provide reliable capital preservation and regular coupon income.
The Liquidity Bucket: Allocating a portion of the portfolio to cash equivalents (such as short-term Treasury bills or high-yield money market instruments) ensures that living expenses or unexpected capital calls are met without liquidating depressed equity holdings. This cash acts as "dry powder" to opportunistically acquire high-quality assets at distressed valuations once the panic subsides.
Discipline over prediction
Attempting to time the exact onset and bottom of a recession is a notoriously unreliable endeavor. The most successful investors do not rely on flawless macro-economic forecasting; instead, they construct portfolios engineered to absorb shocks regardless of timing.
By concentrating capital in businesses with unassailable balance sheets, inelastic consumer demand, pricing power, and hard asset backing, while maintaining a disciplined cash buffer, investors can safeguard their accumulated wealth. Wealth is rarely preserved by chasing speculative highs during late-cycle expansions; it is secured through the quiet resilience of quality assets weathering the storm.