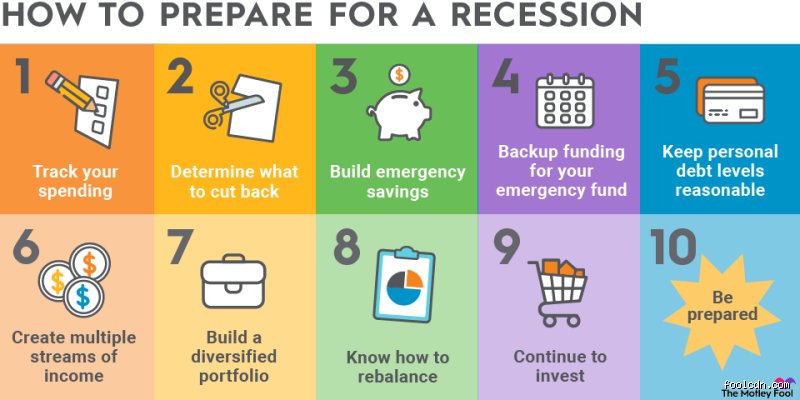
If the economy collapses, your primary goal shifts from growing wealth to preserving it. You should reduce exposure to fragile digital systems, eliminate high-risk debt, and hold a mix of physical cash and tangible assets that retain value even if banks freeze or currency devalues.
How economic collapses actually happen
Real-world financial crises rarely look like instant movie catastrophes. They usually unfold as a process involving the erosion of trust in institutions. You might see banking freezes where ATMs stop working or withdrawals are capped. Alternatively, governments may print money to pay debts, leading to inflation that erodes the purchasing power of your savings. In some cases, major firms default, leaving investors tied up in legal proceedings for years. Understanding these specific failure modes helps you prepare for the actual risks rather than hypothetical ones.
Securing your liquidity
Digital money is convenient, but it depends entirely on the infrastructure working. If the power grid fails or banks impose capital controls, your balance is just a number you cannot access. To mitigate this, keep a reserve of physical cash. Aim for one to three months' worth of essential living expenses. Store this securely at home or in a safe location. This cash is your bridge for immediate needs when electronic payment rails fail. For longer-term reserves, consider highly capitalized institutions or money market instruments that allow easy withdrawal without lock-ups.
Reducing dependency on intermediaries
In a stable economy, using brokerages and digital banks is efficient. In a crisis, these intermediaries become choke points. Audit your assets to see how many entities stand between you and your wealth. Favor direct ownership where possible. This means holding physical possession of assets or having direct legal title rather than relying on a third party's promise to deliver value later. Simultaneously, eliminate unnecessary leverage. Margin debt and adjustable-rate loans become dangerous when asset values drop and income stops. Paying down debt is one of the most effective ways to lower the amount of money you need to survive.
Diversifying into tangible assets
When fiat currency loses trust, value shifts to items with inherent utility. Precious metals like gold and silver have historically held value during currency implosions. Real estate, particularly land with utility, can also serve as a store of value, though it is less liquid. Consumer goods with long shelf lives, such as fuel, water purification tools, and non-perishable food, become valuable in tight markets. You do not need to turn your home into a bunker, but having a portion of your portfolio in non-financial assets provides a hedge against total monetary failure.
Building non-monetary resilience
Money is a proxy for value, but skills and community are the original forms. In a severe collapse, barter networks often replace formal markets. Practical skills in medicine, engineering, agriculture, or maintenance become highly valuable. Cultivate relationships with neighbors and local communities. Knowledge of how to produce food, purify water, or generate power independently reduces your reliance on centralized supply chains. Investing time in learning these skills is an investment in human capital that cannot be frozen or debased.
Positioning for recovery
Economic cycles eventually bottom out. Those who preserve their capital during the downturn are in a strong position when assets become undervalued. Watch for signs of stabilization. When forced liquidations peak, you may find opportunities to acquire real assets at lower prices. As new financial systems emerge, gradually reallocate capital into foundational enterprises that provide essential goods and infrastructure. The key is to remain flexible and avoid panic-driven decisions during the chaotic phase.