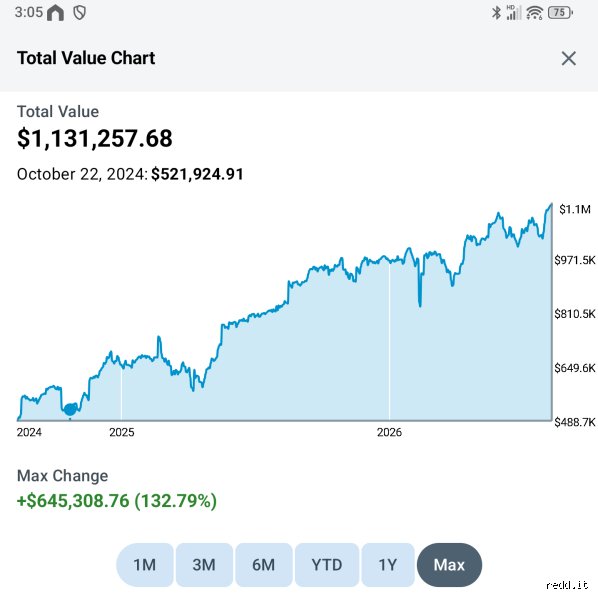
Financial velocity depends heavily on how your assets interact with time, volatility, and leverage. Treating a $500,000 balance like a larger version of a starter savings account guarantees that inflation and opportunity cost will erode your purchasing power. Instead, reaching the 1-million-dollar threshold demands an architectural blueprint that aligns your personal risk tolerance with proven economic growth engines.
Harnessing the mathematics of compounding and the Rule of 72
Understanding how capital doubles begins with fundamental arithmetic rather than market speculation. The financial shortcut known as the Rule of 72 provides a clear baseline for projecting how long your principal will take to reach seven figures without adding another dime. By dividing 72 by your expected annual rate of return, you discover the exact timeline required to turn $500,000 into $1,000,000.
The impact of Return rates on Your timeline
The 4% Conservative Path: Earning a modest 4% return through high-yield instruments or short-term fixed income means dividing 72 by 4, resulting in an 18-year timeline to double your money.
The 7% Balanced Shield: Achieving a historical blended return of 7% through a diversified portfolio reduces the doubling timeline to roughly 10.3 years.
The 10% Growth Engine: Targeting a 10% annualized return, which mirrors long-term equity benchmarks like the S&P 500, cuts the timeline down to approximately 7.2 years.
Controlling friction costs and drag
Every percentage point lost to advisory fees, unoptimized tax brackets, or high expense ratios acts as an anchor on your velocity. A 1% annual management fee on a half-million-dollar portfolio strips away $5,000 every single year. Over a decade of compounding, that hidden cost balloons into tens of thousands of dollars missing from your final seven-figure balance. Minimizing friction requires shifting toward low-cost index funds or direct asset holding structures that keep your gross returns inside your own accounts.
Deploying real estate leverage to accelerate Equity Growth
While public equities offer steady, passive appreciation, real estate introduces a completely different mechanism for scaling wealth: strategic leverage. Using a $500,000 lump sum as a collection of down payments rather than an all-cash purchase allows an investor to control millions of dollars in physical assets. This approach fundamentally alters the math of wealth generation because gains are calculated against the total asset value rather than just your invested equity.
How Mortgage-Backed multiplication works
When you deploy capital across multiple income-producing properties, tenant rents cover the operational debt service, maintenance reserves, and local taxes. Meanwhile, historical property appreciation compounds against the entire portfolio value.
The Equity Multiplier: If you utilize your capital to control $2.5 million worth of real estate, a modest 5% annual appreciation rate yields $125,000 in raw asset growth.
The Cash-on-Cash Return: Measured against your initial $500,000 deployment, that $125,000 gain represents a massive annual return on equity, far outpacing the underlying property growth rate due to the borrowed capital multiplier.
Managing liquidity and operational headwinds
Real estate is rarely a passive endeavor, and treating it as such introduces severe tenant and maintenance risks. Physical property lacks the instant liquidity of the stock market; you cannot sell a kitchen or a roof shingle to reallocate funds on a Tuesday afternoon. Success in this tier requires maintaining a dedicated cash buffer outside of your real estate equity to absorb unexpected vacancies or capital expenditure requirements without forcing a distress sale.
Constructing the Core-Satellite Equity portfolio
For investors who prefer public markets over physical property management, the most efficient path to $1 million relies on a disciplined core-satellite allocation strategy. This method anchors the bulk of your $500,000 in broad-market, low-cost instruments while carving out a controlled percentage for high-conviction growth opportunities.
The core allocation foundation
Placing 70% to 80% of your capital into total market index funds or diversified exchange-traded funds establishes an unshakeable foundation. These instruments eliminate single-company bankruptcy risk and track the broader economic output of leading global industries. Because the expense ratios on these funds are often near zero, your capital stays fully invested and compounds without unnecessary drag.
The satellite Growth layer
The remaining 20% of your portfolio can be dedicated to satellite positions—such as targeted sector funds, individual blue-chip equities, or emerging market opportunities—designed to capture alpha. This compartmentalized risk ensures that while you chase higher-than-average returns to accelerate your journey toward the 1-million-dollar mark, a catastrophic misstep in a single sector cannot derail your entire financial foundation.
How to Double Your Net Worth: Turn $500K Into $1 Million Using Proven Strategies
This video is relevant because it breaks down the core structural frameworks, asset distribution choices, and psychological adjustments required to safely scale a $500,000 portfolio into a seven-figure net worth.
Beyond public equities: Alternative engines for Growth
Scaling a portfolio from half a million to one million requires looking past standard index funds, especially if the timeline is tight. While broad-market equities form a dependable foundation, private equity, commercial real estate syndications, and direct business investments introduce asymmetrical return profiles.
Real estate syndications, for instance, allow accredited investors to pool capital into multi-family housing, industrial complexes, or self-storage facilities. These investments typically generate consistent cash flow distributions while leveraging depreciation to shield income from immediate taxation. By participating in these deals, capital compounds efficiently without facing the annual drag of ordinary income taxes. Syndicators handle property management, tenant relations, and operational scaling, allowing passive investors to benefit from tangible asset appreciation and forced equity creation through strategic property renovations.
Another avenue involves private credit or direct lending. Small and mid-sized enterprises frequently seek capital outside traditional banking channels to fund inventory, payroll, or expansion. Providing bridge loans or participating in structured debt funds can yield annual returns ranging from eight to twelve percent. These yields outpace traditional fixed-income instruments significantly, providing the steady cash injection necessary to accelerate the timeline toward the seven-figure threshold. Naturally, due diligence is mandatory; evaluating borrower creditworthiness, collateral backing, and historical default rates protects principal against unexpected corporate downturns.
Mitigating sequence of returns risk
A critical vulnerability when doubling a capital base is market volatility. Experiencing a severe market downturn right after deploying half a million dollars can permanently derail growth projections. Guarding against this requires a phased deployment strategy, commonly known as dollar-cost averaging on a macro scale, combined with a robust cash buffer.
Allocating the capital in tranches over a twelve-to-eighteen-month window neutralizes the danger of buying at a cyclical peak. If markets correct downward, subsequent tranches purchase assets at discounted valuations. Meanwhile, keeping six months of living expenses in high-yield cash equivalents ensures that personal liquidity needs never force a premature liquidation of appreciating assets.
Investors should also examine volatility drag. When a portfolio drops fifty percent, it requires a one-hundred-percent gain just to break even. Implementing defensive asset classes, such as short-term treasury bills, gold, or uncorrelated alternative assets, softens the blow during systemic corrections, preserving the purchasing power of the initial capital base.
Tax optimization Strategies to accelerate Growth
Taxes represent the single largest drag on investment compounding. Minimizing this liability acts as an immediate multiplier on returns. Utilizing tax-advantaged accounts such as Roth IRAs, traditional IRAs, and health savings accounts maximizes the portion of capital working continuously without government interference.
For taxable brokerage accounts, asset location strategy becomes paramount. Placing high-turnover, income-generating assets like corporate bonds or actively managed funds inside tax-sheltered wrappers preserves capital efficiency. Conversely, holding tax-efficient instruments, such as broad-market index funds or individual municipal bonds, in standard taxable accounts minimizes annual capital gains realizations.
Tax-loss harvesting offers another powerful mechanism. During market corrections, selling underperforming positions to offset realized capital gains shields profits from taxation while maintaining market exposure by reinvesting into correlated, non-identical assets. This practice effectively recovers lost ground through tax savings, turning market downturns into portfolio advantages. Strategic Roth conversions during lower-income years allow investors to transition pre-tax money into tax-free growth vehicles at exceptionally favorable marginal tax brackets.
Structuring the portfolio for the final push
As the portfolio approaches the $750,000 mark, maintaining discipline determines the ultimate success of the strategy. Greed often prompts investors to pivot toward speculative high-beta stocks or leveraged derivatives in a bid to cross the finish line faster. This emotional reaction frequently destroys years of careful accumulation.
Maintaining a balanced asset allocation ensures that growth remains steady rather than volatile. A core-satellite approach works exceptionally well during this final phase. Allocate seventy percent of the portfolio to reliable, low-cost growth engines, such as global equity indexes and cash-flowing real estate. Dedicate the remaining thirty percent to tactical opportunities, individual equities with strong balance sheets, cash-secured put options for income generation, or private investments with high upside potential.
Dividend growth investing provides another stable pathway through this final stretch. Selecting companies with decades of consecutive dividend increases creates a compounding feedback loop. Reinvesting these distributions purchases additional shares automatically, lowering the average cost basis and accelerating share accumulation during flat market cycles.
Reaching the Seven-Figure milestone
Crossing the one million dollar threshold relies less on finding a singular winning investment and more on consistent execution, stringent cost control, and disciplined rebalancing. Review the portfolio quarterly to trim oversized winners and reallocate funds into lagging asset classes, buying low and selling high automatically.
Building wealth is a mechanical process built on math, time, and emotional control. By implementing diversified growth vehicles, shielding returns from excessive taxation, and resisting the urge to chase speculative hype, doubling a half-million-dollar portfolio transitions from an ambitious aspiration into a mathematical certainty. The habits forged during this journey, frugality, continuous financial education, and patience, ultimately ensure that sustaining the seven-figure net worth proves just as achievable as reaching it.