The universal language of commerce
Often mischaracterized as mere bookkeeping or tax preparation, professional accounting is the systematic process of recording, classifying, summarizing, and interpreting financial transactions. At its core, it provides stakeholders, investors, creditors, and management with a clear, reliable mirror reflecting the economic reality of an organization.
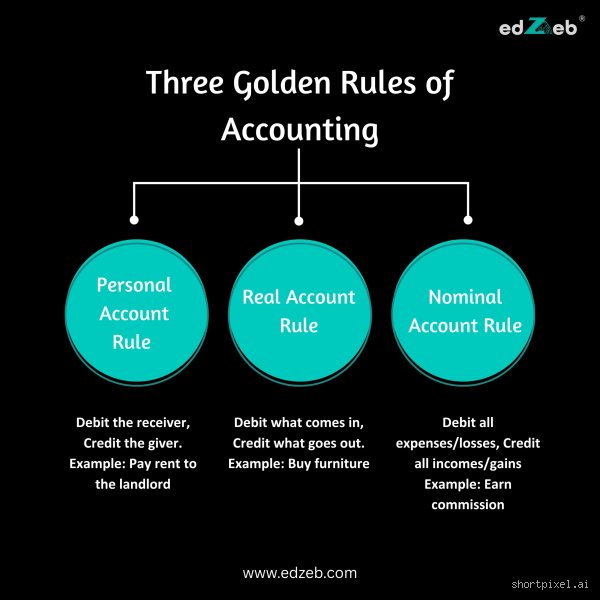
However, before an enterprise can draft a complex balance sheet, analyze cash flow statements, or forecast multi-year financial projections, it must master the foundational bedrock upon which all financial reporting is built. This bedrock is governed by the three basic rules of accounting, traditionally known as the Golden Rules of Accounting.
In this comprehensive first part of our expert series, we will peel back the layers of double-entry bookkeeping, explore the structural classification of accounts, and dissect the first of the three golden rules in exhaustive detail. By the end of this guide, you will understand not just what the rules are, but why they form an unshakeable mathematical and logical framework for the financial world.
The foundation: The anatomy of financial Accounts
To understand the rules that govern accounting entries, one must first understand what an "account" actually is. In accounting terminology, an account is a chronological record of increases and decreases in a specific asset, liability, equity component, revenue stream, or expense category.
Every single business event is captured through double-entry bookkeeping, a brilliant system invented centuries ago by the Italian mathematician and Franciscan friar Luca Pacioli in 1494. The fundamental principle of double-entry bookkeeping is simple yet profound: every financial transaction has a dual effect on the financial position of a business. For every debit entry, there must be an equal and corresponding credit entry.
To operationalize this dual effect, accounts are categorized into distinct types. How these accounts behave under the pressure of business transactions determines the rules we apply to them. Broadly speaking, accounts are split into two major camps: Personal and Impersonal accounts. Impersonal accounts are further subdivided into Real and Nominal accounts.
1. Personal Accounts
Personal accounts relate to individuals, firms, companies, or artificial legal entities with whom the business conducts transactions. They track who owes money to the business (receivables) and to whom the business owes money (payables). Personal accounts can be further broken down into three sub-categories:
Natural Personal Accounts: Accounts belonging to real human beings (e.g., John Doe’s Capital Account, Sarah’s Drawing Account, or a specific customer’s receivable account).
Artificial Personal Accounts: Accounts belonging to entities created by law or recognized as legal persons, such as corporations, partnerships, limited liability companies, banks, and cooperative societies (e.g., Apple Inc. Account, Chase Bank Loan Account).
Representative Personal Accounts: Accounts that represent a specific person or group of persons regarding outstanding expenses or incomes. Examples include Outstanding Salaries Account, Prepaid Rent Account, or Accrued Interest Account.
2. Real Accounts
Real accounts are the accounts relating to assets, properties, and possessions owned by the business. They do not close at the end of an accounting period; instead, their balances roll over from year to year, forming the backbone of the balance sheet. Real accounts are split into two categories:
Tangible Real Accounts: Assets that possess a physical existence and can be touched, seen, and measured. Examples include Land, Buildings, Machinery, Inventory, Cash, and Furniture.
Intangible Real Accounts: Assets that do not have a physical substance but possess monetary value and legal rights. Examples include Goodwill, Patents, Trademarks, and Copyrights.
3. Nominal Accounts
Nominal accounts are the temporary accounts relating to expenses, losses, revenues, and gains. Unlike real accounts, nominal accounts do not carry their balances forward indefinitely. At the end of every fiscal accounting period, their balances are summarized and transferred to the income statement (Profit and Loss Statement) to calculate the net income or loss, after which the nominal accounts are "closed" or reset to zero for the next period. Examples include Rent Expense, Salaries Paid, Interest Received, Sales Revenue, and Advertising Costs.
The ultimate anchor: The Accounting Equation
Before diving headfirst into the rules governing these accounts, we must acknowledge the master equation that holds the entire system together:
Assets=Liabilities+Equity ext{Assets} = ext{Liabilities} + ext{Equity}Assets=Liabilities+Equity
This equation is always in balance. Every transaction alters one or more elements of this equation, but the equality remains intact. The three rules of accounting act as the mechanical gears that ensure this mathematical equilibrium is maintained effortlessly across thousands or millions of daily entries.
When we speak of "Debits" (Dr. ext{Dr.}Dr.) and "Credits" (Cr. ext{Cr.}Cr.):
Debit simply means an entry on the left-hand side of a ledger account.
Credit simply means an entry on the right-hand side of a ledger account.
Depending on the nature of the account, a debit or credit can mean an increase or a decrease. This is precisely where the Three Golden Rules provide absolute clarity, acting as a foolproof compass for accountants worldwide.
Rule #1 explored deeply: The Rule of Personal Accounts
We now arrive at the first of the three pillars of accounting. Because personal accounts deal with human beings and legal entities, the logic governing them revolves around reciprocity, obligation, and relationship.
The Golden Rule for Personal Accounts: Debit the receiver, Credit the giver.
The Underlying Logic
Think about how human relationships work in commerce. When someone takes resources from your business, they become a debtor or a recipient of your value, they owe you, or your ledger must record them as the sink receiving the value. Conversely, when someone provides resources, funding, or goods to your business, they are a benefactor or a source, they give value to the enterprise, and your ledger must record them as the giver.
Let us examine how this rule functions in practical business scenarios.
Practical scenario a: Extending Credit to a customer
Imagine your consulting firm provides marketing services worth $5,000\$5,000$5,000 to ABC Corporation on credit.
Who is receiving the value? ABC Corporation is receiving the service without paying cash immediately. They are the receiver of the economic benefit.
Application of the Rule: Therefore, we debit ABC Corporation’s account by $5,000\$5,000$5,000.
Practical scenario b: Receiving Capital from an Owner
Suppose the owner of a startup, Jane, invests $50,000\$50,000$50,000 of her personal savings into the business bank account.
Who is giving the value? Jane (via her Capital Account) is providing funds to the business entity. She is the giver.
Application of the Rule: Therefore, we credit Jane's Capital Account by $50,000\$50,000$50,000.
Practical scenario c: Settling a liability
Your retail store pays $1,200\$1,200$1,200 to a supplier, XYZ Wholesale, to settle an outstanding invoice for merchandise purchased earlier.
Who is receiving the value? XYZ Wholesale is receiving the payment, reducing the obligation your business had toward them. As the recipient of the cash settlement, they are debited.
Application of the Rule: We debit XYZ Wholesale’s account by $1,200\$1,200$1,200.
| Transaction Type | Account Involved | Account Classification | Rule Applied | Debit / Credit Action |
|---|---|---|---|---|
| Good/Service on Credit | Client Corporation | Personal Account | Debit the receiver | Debit |
| Owner Capital Injection | Owner's Capital | Personal Account | Credit the giver | Credit |
| Supplier Payment | Supplier Vendor | Personal Account | Debit the receiver | Debit |
Preparing for Part Two
As we have seen through personal accounts, accounting is not an arbitrary collection of guesses, but a strict logical system designed to track economic accountability. By understanding natural, artificial, and representative entities and applying the directive to debit the receiver and credit the giver, we establish complete control over our receivables and payables.
However, a business does not run on human relationships alone; it relies heavily on physical properties, machinery, cash, and the day-to-day operating costs and revenues that generate profit.
In Part Two of this expert series, we will continue our deep dive by exploring the remaining two pillars:
The Rule of Real Accounts (Debit what comes in, credit what goes out) with complex asset management examples.
The Rule of Nominal Accounts (Debit all expenses and losses, credit all incomes and gains) detailing how operational performance is captured.
Advanced integration of all three rules into complete, multi-faceted journal entries that drive corporate financial statements.
Detailed breakdown of the Three Golden Rules
To master double-entry bookkeeping, you must look past simple memorization and understand how each rule governs a specific classification of accounts. Let's examine each rule, its underlying rationale, and how it translates into everyday journal entries.
1. Personal Accounts: Debit the receiver, Credit the giver
Personal accounts relate to individuals, firms, companies, or other legal entities with whom a business conducts transactions. These can be further subdivided into natural persons (living human beings like a customer named John), artificial persons (corporations, banks, or partnerships), and representative persons (accounts representing specific expenses or incomes, such as outstanding salaries or prepaid rent).
The Rule: Debit the receiver, credit the giver.
The Logic: When a person or entity receives value from the business (such as cash, goods on credit, or services), their account is debited because they owe an obligation or have absorbed resources. Conversely, when an entity provides value to the business, they are credited because the business now owes them or has benefited from their contribution.
Practical Application Example: Imagine your business purchases $1,500 worth of raw materials on credit from Apex Suppliers.
Accounts involved: Apex Suppliers Account (Personal Account) and Purchases Account.
Application: Apex Suppliers is the giver of the goods, so you credit Apex Suppliers. The matching debit goes to your inventory or purchase account.
2. Real Accounts: Debit what comes in, Credit what goes out
Real accounts are permanent accounts that track the tangible and intangible assets owned by a business. They do not close out at the end of an accounting period; instead, their balances roll over into the next fiscal year. Examples include cash, bank balances, land, buildings, machinery, equipment, patents, and trademarks.
The Rule: Debit what comes in, credit what goes out.
The Logic: This rule relies on the physical or economic flow of resources. Because assets have a natural debit balance, increasing an asset requires a debit (something coming in). Decreasing an asset, such as selling machinery or paying out cash, requires a credit (something going out).
Practical Application Example: Your company purchases a new office computer for $1,200 cash.
Accounts involved: Equipment/Computers Account (Real Account) and Cash Account (Real Account).
Application: The computer equipment enters your business, so you debit the Equipment Account. Cash leaves your safe or bank, so you credit the Cash Account.
3. Nominal Accounts: Debit all Expenses and losses, Credit all Incomes and gains
Nominal accounts are temporary accounts that capture revenues, expenses, gains, and losses over a specific accounting period. At the end of the fiscal year, these accounts are zeroed out (closed) into the income summary or retained earnings accounts. Examples include salary expenses, utility bills, sales revenue, interest earned, and losses from the sale of old equipment.
The Rule: Debit all expenses and losses, credit all incomes and gains.
The Logic: Expenses reduce the overall equity of the business, which naturally corresponds to a debit movement. Incomes and gains increase equity, which corresponds to a credit movement.
Practical Application Example: Your firm pays $800 in monthly office rent via bank transfer.
Accounts involved: Rent Expense Account (Nominal Account) and Bank Account (Personal/Real tracking).
Application: Rent is an expense that reduces net income, so you debit the Rent Expense Account. The bank balance decreases as value leaves the institution, resulting in a credit to the Bank Account.
Putting it all together: A comprehensive Multi-Rule scenario
To see how these three rules interact dynamically within a real-world accounting cycle, consider a sequence of transactions for a growing enterprise. Every single transaction below respects the fundamental accounting equation (Assets=Liabilities+Equity ext{Assets} = ext{Liabilities} + ext{Equity}Assets=Liabilities+Equity) through equal and opposite debit and credit postings.
| Date | Transaction Description | Accounts Involved | Account Types | Rule Applied | Journal Entry |
|---|---|---|---|---|---|
| Oct 1 | Invested $50,000 cash to start the business | Cash, Capital | Real, Personal | Debit what comes in (Cash), Credit the giver (Owner/Capital) | Debit Cash $50,000 Credit Capital $50,000 |
| Oct 5 | Paid $2,500 for monthly warehouse rent | Rent Expense, Cash | Nominal, Real | Debit all expenses (Rent), Credit what goes out (Cash) | Debit Rent Expense $2,500 Credit Cash $2,500 |
| Oct 12 | Sold consulting services for $4,000 cash | Cash, Service Revenue | Real, Nominal | Debit what comes in (Cash), Credit all incomes (Revenue) | Debit Cash $4,000 Credit Service Revenue $4,000 |
| Oct 20 | Purchased office furniture on credit from Acme Corp for $6,000 | Furniture, Acme Corp | Real, Personal | Debit what comes in (Furniture), Credit the giver (Acme Corp) | Debit Furniture $6,000 Credit Acme Corp $6,000 |
Traditional Golden Rules vs. Modern Accounting Approach
While the three golden rules remain a cornerstone of traditional bookkeeping pedagogy across the globe, modern financial accounting often relies on the Modern Approach (Accounting Equation Approach).
Rather than categorizing accounts into Personal, Real, and Nominal, the modern framework categorizes accounts into five core types: Assets, Liabilities, Capital (Equity), Revenues (Incomes), and Expenses.
Assets & Expenses: Increased by Debits, Decreased by Credits.
Liabilities, Capital, & Revenues: Increased by Credits, Decreased by Debits.
Despite the different classification vocabulary, the mathematical outcome is identical. Both frameworks ensure that total debits equal total credits, maintaining absolute mathematical integrity in the ledger. For students and junior accountants, learning the traditional golden rules provides an intuitive, conceptual bridge to understand why values move the way they do based on interpersonal obligations and physical resource flows.
Conclusion
Mastering the three basic rules of accounting is non-negotiable for anyone serious about financial literacy, auditing, or corporate accounting. By systematically categorizing every business event into personal, real, or nominal accounts and applying the corresponding debit and credit logic, accountants eliminate guesswork.
These rules protect organizations from imbalances, streamline the preparation of trial balances and financial statements, and establish a reliable audit trail. Whether you are balancing a small business ledger by hand or configuring an enterprise resource planning (ERP) system, the golden rules remain the bedrock upon which reliable financial reporting is built.