Introduction: The Universal Language of Business
In the dynamic world of commerce, financial statements serve as the universal language through which businesses communicate their economic health to investors, creditors, regulatory bodies, and internal management. However, just as spoken languages require grammar and syntax to prevent miscommunication, the financial ecosystem requires a rigid structure of standardized rules to ensure clarity, comparability, and trust.
Without these shared rules, financial reporting would quickly descend into chaos. Companies could manipulate their earnings reports, assets could be arbitrarily valued at whatever price seemed advantageous at the moment, and external stakeholders would have no reliable way to compare the performance of one firm against another. To prevent this, standard-setting bodies—such as the Financial Accounting Standards Board (FASB) in the United States, which governs Generally Accepted Accounting Principles (GAAP), and the International Accounting Standards Board (IASB), which oversees International Financial Reporting Standards (IFRS)—have established a robust framework of core principles.
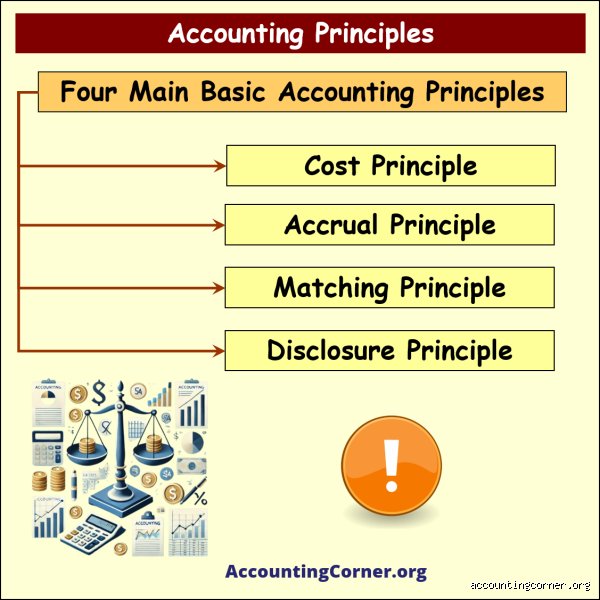
While the full landscape of accounting standards includes dozens of nuances, assumptions, and constraints, financial analysts, auditors, and business leaders universally anchor their work to a core set of pillars. In this first part of our comprehensive expert guide, we will explore the underlying philosophy of these guidelines and dive deeply into the first two of the four main principles of accounting: the Historical Cost Principle and the Revenue Recognition Principle.
Understanding the Framework: Principles vs. Concepts
Before dissecting individual rules, it is helpful to distinguish between accounting concepts and accounting principles.
Accounting concepts represent broad theoretical assumptions or general underlying ideas—such as the Going Concern Concept or the Economic Entity Concept—which shape how we view a business entity.
Accounting principles, on the other hand, are the specific operational rules and guidelines that dictate how economic events are measured, recorded, and presented on financial statements.
When financial professionals refer to the "main principles" that drive day-to-day bookkeeping and external reporting, they typically point to a core quartet that ensures transactions are captured objectively, matched correctly, and disclosed transparently. Mastering these rules is essential for anyone looking to interpret balance sheets, income statements, and cash flow reports accurately.
Principle 1: The Historical Cost Principle
Definition and Core Concept
The Historical Cost Principle is one of the oldest and most rigid rules in traditional accounting. It dictates that businesses must record their assets, liabilities, and equity instruments at their original acquisition cost (the actual amount of cash paid or the fair value of the consideration given at the time of purchase) rather than their current market value.
For example, if a corporation purchases a commercial warehouse for $1,000,000, that property must remain listed on the balance sheet at $1,000,000 (minus any accumulated depreciation), even if real estate prices skyrocket and the building becomes worth $3,000,000 a decade later.
The Rationale Behind Objectivity
The primary driver behind the historical cost principle is objectivity and verifiability.
Elimination of Subjectivity: Market values fluctuate constantly and are frequently open to interpretation, bias, or manipulation.
Two independent appraisers might estimate the current market value of a specialized piece of manufacturing equipment differently. Verifiable Evidence: Historical cost, by contrast, is anchored by hard, verifiable documentation—such as bank statements, purchase orders, canceled checks, and vendor invoices.
By relying on facts rather than forecasts for asset valuation, financial statements maintain a high degree of credibility and protect against overly optimistic management projections.
Practical Application and Limitations
In everyday accounting operations, the historical cost principle provides a stable baseline for tracking capital expenditures. However, modern financial reporting has recognized certain limitations to this approach.
Inflation and Purchasing Power: Over long periods, inflation can render historical costs misleadingly low relative to current economic realities.
Fair Value Exceptions: To bridge this gap, modern accounting standards (such as ASC 320 for investments or specific IFRS rules for financial instruments and biological assets) increasingly permit or require fair value accounting for certain volatile assets like marketable securities and derivatives.
Nevertheless, for long-lived tangible assets like property, plant, and equipment (PP&E), the historical cost principle remains the gold standard of conservative baseline reporting.
Principle 2: The Revenue Recognition Principle
Definition and Core Concept
The Revenue Recognition Principle dictates when a business should officially record income in its accounting records.
This principle serves as the dividing line between cash-basis accounting (where revenue is recorded only when money hits the bank account) and accrual-basis accounting (where economic activity dictates timing).
To satisfy the criteria of being "earned," the seller must have substantially completed what it promised to do to be entitled to the benefits represented by the revenues—typically when goods are delivered or services are fully rendered.
The Accrual Connection and Complex Modern Standards
In past decades, revenue recognition was relatively straightforward: you deliver a product, hand over an invoice, and record the sale. However, in today’s service-oriented and digital economy—characterized by multi-year software subscriptions, bundled service packages, and complex licensing agreements—determining when a good or service is "earned" has become highly intricate.
This led to major regulatory updates, notably ASC 606 (under US GAAP) and IFRS 15 (under International Standards), which establish a standardized five-step model for recognizing revenue:
Identify the contract with a customer.
Identify the performance obligations in the contract.
Determine the transaction price.
Allocate the transaction price to the performance obligations.
Recognize revenue when (or as) the entity satisfies a performance obligation.
Impact on Financial Integrity
Proper application of the revenue recognition principle prevents companies from artificially inflating their short-term performance.
Instead, the revenue recognition principle requires the firm to spread that income across the three years as the consulting services are actively delivered. This gives investors an accurate, transparent view of ongoing operational earning power.
Continue to Part 2 to explore the remaining core pillars: the Matching Principle and the Full Disclosure Principle, alongside how these four concepts integrate into complete financial models.
Would you like to review specific examples of how the Matching Principle interacts with accruals before we proceed to Part 2?
...Building upon the foundational framework of the economic entity and going concern assumptions, we turn our attention to the operational mechanics of modern financial reporting. While the initial principles establish who is reporting and under what condition the business operates, the remaining core principles dictate when and how financial transactions are recorded, measured, and disclosed to stakeholders.
Mastery of these principles is not merely an academic exercise for certified public accountants; it is the bedrock upon which sound business strategy, investor trust, and regulatory compliance are built.
Operational Principles: Accrual, Matching, and Revenue Recognition
To truly understand how financial statements reflect the economic reality of an enterprise, one must examine the triad of operational accounting principles: the Accrual Principle, the Matching Principle, and the Revenue Recognition Principle.
1. The Accrual Principle and Economic Reality
Under cash-basis accounting, transactions are recorded only when cash changes hands. While simple, this method fails to capture the true financial health of a dynamic business. The Accrual Principle mandates that revenues are recorded when they are earned, and expenses are recorded when they are incurred, regardless of when cash flows.
Why it matters: Consider a software-as-a-service (SaaS) company that signs a $120,000 annual contract paid upfront in January. Under cash accounting, January looks exceptionally profitable, while the subsequent eleven months show zero revenue despite heavy customer support and server maintenance costs. Accrual accounting distributes the $10,000 monthly revenue evenly across the year, aligning income with the delivery of service.
Strategic impact: Management and investors rely on accrual-based statements to evaluate operational performance, forecast cash flows, and make informed capital allocation decisions without the distortion of timing discrepancies in cash receipts.
2. The Matching Principle: Synchronizing Cause and Effect
Closely tied to accrual accounting is the Matching Principle, which dictates that expenses must be reported in the same period as the revenues they helped generate.
The logic of cause and effect: If a manufacturing firm produces a batch of widgets in March using raw materials purchased on credit and labor paid that month, but the widgets are sold in May, the production costs must be recognized in May alongside the revenue from the sale.
Inventory and Depreciation: This principle is the primary driver behind complex accounting treatments like inventory capitalization and depreciation. By spreading the cost of a multi-million-dollar factory machine over its useful life (matching its depreciation expense against the revenue generated over years of production), financial statements prevent artificial profit spikes and dips.
3. Revenue Recognition: Defining the Finish Line
When is a sale actually a sale? The Revenue Recognition Principle (formalized globally under standards like ASC 606 and IFRS 15) provides a rigorous five-step framework to answer this question. It requires that revenue be recognized only when the control of goods or services has been transferred to the customer, in an amount that reflects the consideration the company expects to be entitled to.
Mitigating manipulation: In the past, companies could prematurely log revenue for long-term projects before work was complete, misleading investors. Modern revenue recognition eliminates this loophole, ensuring that top-line figures represent earned economic value rather than contractual promises.
Guardrails of Integrity: Consistency, Disclosure, and Conservatism
Beyond recording mechanics, financial reporting is governed by principles designed to ensure transparency, comparability, and prudence.
+------------------------------------------------------------+
| THE PILLARS OF FINANCIAL INTEGRITY |
+------------------------------------------------------------+
| • Consistency: Enabling year-over-year trend analysis. |
| • Full Disclosure: Leaving no material fact hidden. |
| • Conservatism: Anticipating no profits, providing for all.|
+------------------------------------------------------------+
The Principle of Consistency
The Consistency Principle requires a company to adopt the same accounting methods, policies, and classifications from one period to the next (e.g., sticking with FIFO vs. LIFO for inventory valuation).
If an enterprise changes its accounting method (for instance, switching depreciation methods), it must explicitly disclose the change and its financial impact in the footnotes. Without consistency, financial statement analysis becomes an exercise in guesswork, destroying historical comparability.
The Full Disclosure Principle
Transparency is the lifeblood of efficient capital markets. The Full Disclosure Principle dictates that financial statements must include all information necessary to prevent a reasonably prudent investor from being misled.
This is where footnotes, supplementary schedules, and management discussion and analysis (MD&A) sections become critical. Contingent liabilities (such as pending lawsuits), complex debt covenants, and related-party transactions must be brought to light, ensuring that the balance sheet and income statement tell the whole story.
The Principle of Conservatism (Prudence)
Accounting is inherently prone to estimation—estimating bad debt allowances, asset useful lives, and warranty reserves. The Conservatism Principle acts as an anchor of prudence: when choosing between two acceptable accounting treatments, an accountant should select the option that is less likely to overstate assets or income.
In practice: If a customer's creditworthiness is questionable, conservatism dictates recording an allowance for doubtful accounts immediately, rather than waiting for formal default. It ensures that businesses do not project unwarranted optimism to stakeholders.
Accounting Principles in the Modern Era
As we navigate through the digital landscape, the application of these foundational accounting principles continues to evolve. Emerging business models—such as decentralized finance (DeFi), intangible digital assets (like intellectual property and data portfolios), and complex subscription economies—test the boundaries of historical cost and economic entity assumptions.
Furthermore, artificial intelligence and automated ERP systems are redefining how transactions are captured and matched. Yet, while software automates the ledger, the human interpretation of these principles remains irreplaceable. Algorithms can process data at lightning speed, but financial leaders must still apply professional judgment to ensure that accounting treatments honor the spirit, not just the letter, of these foundational rules.
Conclusion
The four main principles of accounting—expanded into the broader framework of accrual, matching, consistency, going concern, and full disclosure—form a universal language of business. They transform raw transactional noise into structured, reliable economic signals. For business leaders, entrepreneurs, and investors alike, a deep fluency in these principles is not merely about compliance; it is the key to decoding financial truth and driving sustainable enterprise value.