The evolution of Double-Entry ledger mechanics: Where it all began
Accounting is not merely a modern corporate headache. Around 1494 in Venice, a Franciscan friar named Luca Pacioli codified a system that merchants had been whispering about for decades. He did not invent it, but his documentation revolutionized commerce. Before Pacioli’s system took root, tracking wealth was a messy, single-entry affair where mistakes went unnoticed until a business was already bankrupt. Merchants literally guessed their profits based on the cash in their pockets, we are far from that primitive guessing game today.
The architecture of the account classifications
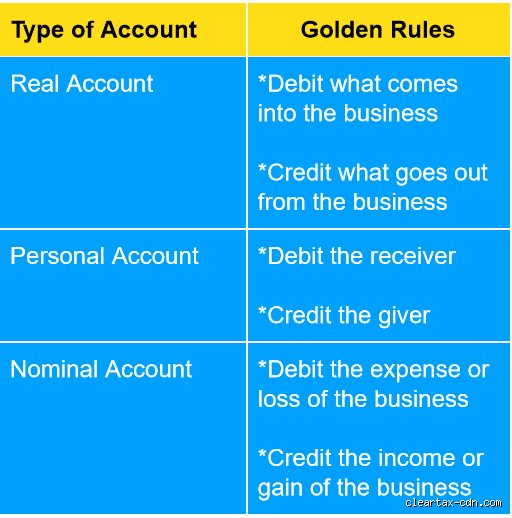
Before you even touch a ledger, you must realize that everything in business fits into three distinct buckets. Personal accounts track your dealings with living, breathing human beings or legal entities like Acme Corp. Real accounts handle the tangible stuff, machinery, buildings, hard cash, and the intangible ones like patents. Finally, nominal accounts capture the fleeting, ephemeral nature of expenses, losses, and revenues. If you misclassify a piece of manufacturing equipment as an expense, your entire balance sheet warps into pure fiction.
Why manual principles persist in a Cloud-Based world
Modern enterprise resource planning systems like SAP or NetSuite are just Pacioli’s brain wrapped in slick user interfaces. Software breaks down. When a junior accountant inputs an invoice incorrectly, the automated system will happily balance a completely erroneous entry. Understanding the underlying mechanics allows you to spot the ghost in the machine. I have seen multi-million-dollar discrepancies that took weeks to untangle, all because an automated script confused a liability with an equity draw during a routine system migration.
Decoding rule one: The realm of real accounts and tangible assets
Let us strip away the jargon and look at the first pillar, which dictates that you debit what comes in and credit what goes out. This specific doctrine applies strictly to real accounts, which encompass everything from cold hard cash in a bank vault in Manhattan to the delivery trucks idling outside a warehouse in Frankfurt. When assets change hands, this rule dictates the precise direction of the financial flow.
The internal friction of asset acquisition
Imagine your company buys a new delivery van on March 15, 2026, for $45,000 in cash. The van is coming into the business, so the vehicle account receives a debit. Conversely, cash is walking out the door, which necessitates a corresponding credit to the cash asset account. It sounds simple on paper. Yet the complication is handling the hidden transaction costs like registration fees or delivery charges, do they count as part of the asset or a separate expense? Traditionalists argue for capitalization, but modern practices occasionally diverge depending on regional tax laws.
The nuance of depreciation and disposal
Assets do not stay pristine forever. As machinery ages, its value deteriorates, creating an accounting paradox where the physical asset remains, but its book value shrinks. When you eventually sell that old van for scrap metal, you must reverse the initial entry process entirely. This is where many novice bookkeepers stumble. Because they forget to credit the original asset account for its historical cost while simultaneously accounting for accumulated depreciation, the ledger ends up permanently distorted.
Decoding rule two: Personal accounts and the human element of debt
The second fundamental guideline shifts our focus away from physical objects and toward relationships, establishing that you must debit the receiver and credit the giver. Personal accounts represent individuals, vendors, customers, and institutions like JPMorgan Chase. This rule governs credit transactions, which form the absolute lifeblood of modern corporate commerce where cash rarely changes hands immediately.
Managing credit transactions without losing track
Suppose a long-term client, Smith & Sons Ltd, purchases $12,000 worth of raw steel from your warehouse on credit. Under this specific framework, Smith & Sons is the receiver of the goods, which means their account is immediately debited. You have not received a single cent of physical money yet. But you have acquired a legal claim on their future cash, known as an account receivable. Months later, when they finally send a wire transfer to settle the debt, they become the giver, resulting in a credit to their personal account and a corresponding debit to your bank account.
The problem of the uncollectible debt
What happens when a client vanishes into thin air or files for bankruptcy? The problem is that you cannot indefinitely carry a dead asset on your books. When a personal account defaults, you must aggressively write it off, converting that dead receivable into a nominal loss. It's unclear why some firms delay this painful process, though it usually stems from a desire to make quarterly earnings look artificially inflated to shareholders.
The structural divergence: Real accounts versus nominal accounts
A major point of confusion for anyone entering the financial sector is the inherent friction between real accounts and nominal accounts. Real accounts are permanent fixtures that survive the closing of the fiscal year, carrying their balances forward into the next chapter of the company's life. Nominal accounts, however, are intentionally wiped clean at midnight on the final day of the accounting cycle, their contents poured directly into the retained earnings pool.
The temporal nature of expenses and revenue
Think of nominal accounts as temporary buckets designed to measure performance over a specific, limited window of time. The third rule, debit all expenses and losses, credit all incomes and gains, rules this domain completely. When you pay a $5,000 monthly office rent bill, that money is gone forever; it does not create a lasting asset like buying a building would. So it is recorded as a debit to rent expense. That matters most when analyzing profitability, because if you accidentally mix these up with real accounts, your net income figures become utterly meaningless overnight.
Common pitfalls and distorted accounting myths
The illusion of the permanent cash bias
Many bookkeepers stumble here. You stare at the bank statement and assume every single line item dictates an immediate entry, ignoring the architectural reality of accrual accounting. Cash changes hands long after or before value is generated. Recording a transaction solely because money moved violates the matching principle. The core problem is that amateur accountants treat the cash account like a personal checking ledger. It is not. If you ship goods on credit, the revenue belongs to today, not next quarter when the client finally settles the invoice.
Confusing nominal and real accounts
Mixing up your ledger categories breeds absolute chaos. People routinely debit an asset account when they should be hitting an expense line, skewing the entire balance sheet. Why does this happen? Because human intuition fails when confronted with abstract legal entities. A company vehicle is a tangible asset, yet the fuel filling its tank represents an immediate operational cost. If you misclassify a major repair as a structural upgrade, you artificially inflate your net worth while deflating your current liabilities.
The double-entry symmetry trap
Just because your total debits perfectly equal your total credits does not mean your books are flawless. This mathematical harmony often masks catastrophic structural blunders. You could easily record a valid $5,000 debit to equipment instead of inventory. The system balances beautifully. The reports look immaculate. Yet, your asset distribution is completely corrupted, which explains why reliance on automated software verification can lead to a false sense of security.The hidden engine of the ledger: Sub-ledger isolation
Why your main general ledger is lying to you
The traditional approach instructs you to log everything into the main pipeline, but true experts know the real magic happens in sub-ledger decoupling. This technique isolates high-volume transactional data, preventing your primary system from becoming sluggish and unreadable. Think about a retail operation processing 45,000 unique credit sales daily. Shifting these micro-transactions into an auxiliary sales ledger preserves the clarity of your core records.
What happens if you ignore this strategy? Your system bogs down under sheer volume, rendering real-time financial analysis impossible. By implementing a strict data-gatekeeping protocol, you ensure that only aggregated daily summaries ever touch the primary accounts. It requires extra maintenance, but the alternative is data paralysis.
Frequently asked questions
How frequently do fatal errors slip through the three golden rules of journal entry?
Empirical data reveals that roughly 12% of manually entered transactions contain some form of classification or transposition error. Even when accounting systems show perfect balance, underlying flaws persist. For instance, a recent industry survey highlighted that 42% of corporate audit adjustments stem directly from initial ledger misclassifications. These oversight patterns typically surface during quarterly reconciliations rather than daily operations. The upshot: organizations lose hundreds of billable hours untangling historical errors that bypassed basic validation checks.Can automated accounting platforms completely replace human understanding of these principles?
Software serves as an incredible calculator, yet it utterly lacks institutional context. An algorithm cannot determine whether a $10,000 legal fee represents a routine operational cost or a capitalizable acquisition expense. The system merely executes the electronic parameters you define. But can a machine understand business intent? Absolutely not, meaning human oversight remains the definitive backstop against data corruption. Relying blindly on automation usually accelerates the rate at which you generate systemic errors.