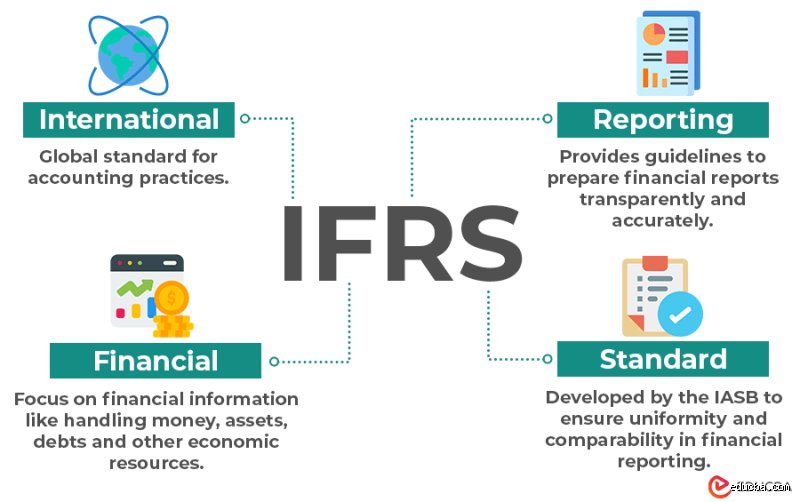
In the hyper-connected architecture of modern global commerce, financial transparency is the ultimate currency, and at the very heart of this global economic dialogue lies a deceptively simple acronym: IFRS.
For anyone stepping into the worlds of corporate finance, auditing, investment banking, or global business management, understanding the exact terminology is non-negotiable. The correct full form of IFRS is International Financial Reporting Standards.
However, reducing IFRS to a mere three-word definition is like describing a skyscraper by looking only at its cornerstone. To truly grasp what IFRS represents, one must examine its origins, its foundational philosophy, its governing architecture, and why it has become the gold standard for financial accountability across more than 140 jurisdictions worldwide. This opening part of our expert exploration will dissect the anatomy of IFRS, establishing why these standards are the bedrock upon which modern cross-border investment is built.
1. Deconstructing the name: What International Financial Reporting Standards really mean
To appreciate the weight of the full form, we must break down its components word by word:
International: Unlike regional or domestic accounting rules (such as the US Generally Accepted Accounting Principles, or US GAAP), IFRS is designed to transcend borders. It provides a common financial language that bridges economic divides between Tokyo, London, New York, Frankfurt, and Sydney.
Financial Reporting: IFRS goes far beyond bookkeeping or balancing ledger books. It governs how financial performance is communicated to the outside world—encompassing balance sheets, income statements, cash flow statements, and comprehensive disclosures that tell the true economic story of an enterprise.
Standards: These are not mere suggestions or guidelines; they are rigorous, authoritative principles developed to ensure consistency, comparability, and reliability. They dictate how transactions and other economic events should be recognized, measured, presented, and disclosed in financial statements.
When combined, International Financial Reporting Standards represent a comprehensive, principle-based framework intended to ensure that financial statements are transparent, comparable across international boundaries, and of high enough quality to help investors and other market participants make informed economic decisions.
2. The historical imperative: Why the world needed a common Financial language
For decades, international trade was hampered by a Babel-like barrier of accounting practices. If a multinational corporation based in France wanted to acquire a competitor in Singapore, or if a pension fund in Canada wanted to invest in an emerging market enterprise in Brazil, financial analysts had to undergo grueling translations not just of language, but of accounting logic.
A company showing a healthy profit under one nation's domestic GAAP might look deeply troubled or overly inflated under another's. This fragmentation created massive friction, increased the cost of capital, and confused global investors who lacked a reliable yardstick to measure risk and return.
The roots of IFRS trace back to the late 20th century, driven by the acceleration of globalization, the deregulation of financial markets, and the meteoric rise of cross-border capital flows. Investors demanded transparency, regulators sought systemic stability, and corporations wanted to reduce the administrative and financial burdens of complying with multiple disparate regulatory regimes.
Enter the International Accounting Standards Board (IASB) and its parent organization, the IFRS Foundation. Headquartered in London, the IASB assumed responsibility in 2001 (succeeding the International Accounting Standards Committee, which began issuing International Accounting Standards, or IAS, in 1973) for developing a single set of high-quality, understandable, enforceable, and globally accepted accounting standards.
The mandate was clear: replace a patchwork quilt of national rules with a unified, high-integrity global framework.
3. Principles vs. Rules: The philosophical core of IFRS
One of the most defining characteristics of IFRS—and a point of intense study for financial experts, is its principles-based approach, contrasted sharply against the historically rules-based approach of frameworks like US GAAP.
The Principle-Based Philosophy
Under IFRS, standards are built around clear conceptual objectives. Accountants and auditors are required to look at the economic substance of a transaction rather than just its legal form. If a rule does not explicitly cover a novel business transaction, professionals must refer back to the overarching framework of IFRS to determine the most faithful representation of the economic reality.
Pros: It encourages professional judgment, reduces the opportunity for legalistic loopholes designed to bypass strict text-based rules, and adapts more fluidly to innovative business models (such as digital assets, platform economies, and complex financial derivatives).
Cons: It can sometimes lead to greater divergence in professional interpretation, making consistency harder to enforce across different jurisdictions and industries.
By focusing on concepts like relevance, faithful representation, comparability, verifiability, timeliness, and understandability, IFRS ensures that financial statements act as a clear window into a company's financial health rather than a maze of technical compliance checkboxes.
4. The architecture of the IFRS Framework
To understand how IFRS functions in practice, one must look at how the standards are structured. The IFRS body of work is not a single monolithic rulebook, but a dynamic, interconnected ecosystem consisting of:
The Conceptual Framework for Financial Reporting: The foundational document that sets out the fundamental concepts guiding the IASB when it develops IFRS standards. It assists preparers in developing consistent accounting policies when no specific standard applies.
IFRS Standards: Standards issued by the IASB post-2001. These cover specific, complex financial topics, ranging from revenue recognition (IFRS 15) and leases (IFRS 16) to financial instruments (IFRS 9) and insurance contracts (IFRS 17).
International Accounting Standards (IAS): Standards issued by the predecessor organization (IASC) between 1973 and 2001. Many of these remain active and authoritative today unless superseded or amended by newer IFRS standards.
Interpretations: Developed by the IFRS Interpretations Committee (formerly IFRIC), these provide authoritative guidance on newly identified financial reporting issues not explicitly addressed in IFRS or IAS, or contexts where divergent interpretations have developed.
5. Looking ahead: Setting the stage for global consistency
As international markets continue to evolve at a breakneck pace, driven by technological disruption, environmental, social, and governance (ESG) reporting demands, and shifting macroeconomic tides, the relevance of IFRS has never been more pronounced.
Knowing the correct full form, International Financial Reporting Standards, is merely the entry point to understanding a sophisticated global architecture designed to foster trust, reduce friction, and allocate capital efficiently across borders.
In the subsequent sections of this expert analysis, we will dive deeper into the mechanics of specific standards, explore the ongoing convergence efforts with other major global frameworks, and examine how IFRS shapes the day-to-day decisions of chief financial officers, auditors, and global investors alike.
HTML
Common HTML mistakes to avoid
Writing clean, accessible, and valid HTML is foundational for modern web development. However, even experienced developers occasionally fall into bad habits that can harm site performance, accessibility, and search engine optimization (SEO). Being aware of these common pitfalls helps ensure your web pages remain robust and user-friendly.
1. Neglecting semantic elements
One of the most frequent errors is overusing generic tags like <code><div></code> and <code><span></code> for structural layout instead of proper semantic elements. HTML5 introduced tags like <code><header></code>, <code><nav></code>, <code><main></code>, <code><article></code>, <code><section></code>, and <code><footer></code> to give structural meaning to content. When you rely solely on divs, screen readers and search engines struggle to understand the hierarchy and importance of different page sections, diminishing both accessibility and SEO rankings.
2. Forgetting alt text on images
Images are essential for visual engagement, but omitting the <code>alt</code> attribute on <code><img></code> tags creates a major accessibility barrier. Screen readers rely entirely on alternative text to describe images to visually impaired users. If an image fails to load, the alt text provides crucial context for all visitors. Always include descriptive, concise alt text that conveys the actual purpose or visual content of the image.
3. Improper heading hierarchy
Headings (<code><h1></code> through <code><h6></code>) create a logical outline of your page content. A common mistake is choosing heading tags based on their default CSS styling rather than their hierarchical role, such as jumping straight from an <code><h1></code> to an <code><h4></code> just because of font size preferences. Headings should always follow a sequential, descending order. Skipping levels disrupts the document outline, making navigation difficult for users relying on assistive technologies.