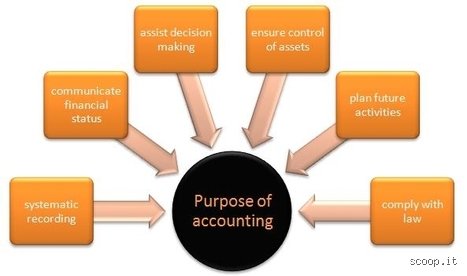
At its core, the primary purpose of accounting can be encapsulated in a single, powerful mandate: to provide decision-makers with relevant, reliable, and timely financial information that enables rational allocation of scarce economic resources.
Yet, understanding this purpose requires unpacking layers of economic philosophy, historical evolution, and modern corporate governance. This first part of our comprehensive exploration will deconstruct what accounting truly is, separate it from common misconceptions, examine its philosophical underpinnings, and map out the vast ecosystem of stakeholders who rely on its outputs to navigate an uncertain financial world.
1. Beyond the numbers: Defining the true essence of Accounting
To understand the purpose of accounting, one must first dismantle a persistent linguistic confusion: the conflation of bookkeeping and accounting. While these two disciplines are inextricably linked, they serve distinct functions within the financial lifecycle.
Bookkeeping (The Mechanics): Bookkeeping is the systematic, chronological recording of daily financial transactions. It is the tactical execution of data entry—ensuring that every sale, purchase, receipt, and payment is logged accurately using established frameworks like double-entry bookkeeping. Bookkeeping captures the what and the how much of past transactions.
Accounting (The Strategy and Interpretation): Accounting begins where bookkeeping ends. It involves the design of information systems, the summarization, analysis, verification, and interpretation of financial data, and the transformation of raw numbers into strategic insights. Accounting asks why the numbers look the way they do, what they imply for the future, and how they should be communicated to external and internal audiences.
Accounting operates as a communication channel. Just as human language translates abstract thoughts into structured words so that two minds can share an understanding, accounting translates complex, multifaceted operational activities, factory production, supply chain logistics, employee hours, R&D expenditures, and customer sales, into standardized financial statements. Without this translation, a business would be an opaque black box, impossible for investors to value, lenders to risk-assess, or managers to steer.
2. The core purpose: Decision-Usefulness and economic stewardship
If you were to open the conceptual frameworks established by major global accounting standard-setters, such as the Financial Accounting Standards Board (FASB) in the United States or the International Accounting Standards Board (IASB), you would encounter a guiding North Star phrase: Decision-Usefulness.
Financial reporting is not an end in itself; it is a means to an end. The overarching objective of general-purpose financial reporting is to provide financial information about the reporting entity that is useful to existing and potential investors, lenders, and other creditors in making decisions relating to providing resources to the entity.
This purpose rests on two distinct pillars:
A. Reducing information asymmetry
In any market economy, a fundamental friction exists known as information asymmetry. The managers running a company always know more about its true operational health, risks, hidden liabilities, and future prospects than external shareholders or banks lending capital. If left unchecked, this asymmetry creates a "lemons market" scenario where investors, fearing the worst, withhold capital entirely due to distrust. Accounting acts as the great equalizer. By enforcing standardized rules (such as US GAAP or IFRS), independent audits, and transparent disclosures, accounting bridges the trust gap, lowering the cost of capital and allowing efficient markets to function.
B. Accountability and economic stewardship
Beyond forward-looking decision-making, accounting serves a historical, stewardship-oriented purpose. Managers act as agents entrusted with the capital of principals (shareholders and owners). Accounting provides the mechanism by which these stewards render an account of their stewardship. Did they safeguard the assets entrusted to them? Did they generate a reasonable return? Did they comply with legal and contractual covenants? By answering these questions, accounting establishes corporate accountability, deterring fraud, managerial negligence, and resource misallocation.
3. Historical evolution: From tally sticks to Strategic foresight
The purpose of accounting has not remained static; it has evolved in lockstep with the complexity of human commerce.
Ancient Roots: Thousands of years before the common era, ancient civilizations in Mesopotamia, Egypt, and China used clay tokens and papyrus scrolls to track agricultural yields, taxes, and trade inventories. Here, the primary purpose was purely administrative control and taxation.
The Double-Entry Revolution (1494): The publication of Summa de Arithmetica by the Franciscan friar Luca Pacioli in Venice revolutionized commerce. By introducing the double-entry system, where every debit has a corresponding credit, ensuring mathematical self-correction, accounting provided merchants with a comprehensive snapshot of wealth, debt, and profitability for the first time.
The Industrial Revolution and the Rise of the Corporation: As businesses scaled from small family shops to massive joint-stock railway and manufacturing conglomerates requiring capital from thousands of anonymous investors, accounting shifted from private record-keeping to public reporting. The need for standardized rules became paramount to protect public savings.
The Modern Era (Digital, Global, and ESG-Integrated): Today, in the mid-2020s, the purpose of accounting is expanding once again. While traditional financial metrics (net income, cash flow, return on equity) remain vital, modern stakeholders increasingly demand accountability over non-financial dimensions: environmental impact, social responsibility, supply chain ethics, and data security. Accounting is morphing from historical financial reporting into integrated corporate reporting, capturing both tangible monetary value and intangible long-term value creation.
4. The stakeholder ecosystem: Who needs Accounting and why?
To fully grasp the purpose of accounting, one must examine the diverse array of users who depend upon financial data. These users are generally categorized into two groups, each with distinct informational requirements:
+-----------------------------------------------------------------+
| THE STAKEHOLDER ECOSYSTEM |
+---------------------------------+-------------------------------+
|
+------------------------+------------------------+
| |
v v
+------------------------+ +------------------------+
| INTERNAL USERS | | EXTERNAL USERS |
| (Management & Staff) | | (Investors, Lenders, |
+------------------------+ | Regulators, Public) |
| • Cost Accounting | +------------------------+
| • Budgeting & Variance | | • Capital Allocation |
| • Operational Strategy | | • Credit Risk Analysis |
| • Performance Metrics | | • Regulatory Compliance|
+------------------------+ +------------------------+
1. Internal users (Management, executives, and employees)
Inside an organization, accounting serves as an internal compass and control system. Through management accounting, leaders use detailed cost-benefit analyses, variance reports, rolling budgets, and divisional profitability metrics to answer critical operational questions:
Should we launch a new product line or discontinue an unprofitable one?
Are manufacturing costs rising faster than projected revenue?
How much working capital do we need to secure to survive the next quarter?
For internal users, the purpose of accounting is operational optimization, strategic planning, and performance evaluation.
2. External users (Investors, Lenders, creditors, and Regulators)
Outside the corporate perimeter, stakeholders rely on financial accounting statements (the Balance Sheet, Income Statement, and Statement of Cash Flows) to evaluate external risk and reward:
Equity Investors: Look at earnings per share (EPS), profit margins, and growth trends to decide whether to buy, hold, or sell stock.
Banks and Lenders: Scrutinize liquidity ratios, debt-to-equity structures, and cash flow generation to determine creditworthiness and set interest rates.
Tax Authorities and Regulators: Ensure compliance with statutory laws, verify correct tax liabilities, and protect public market integrity.
Suppliers and Customers: Assess whether a company is financially stable enough to fulfill long-term contracts or warrant extended credit terms.
Looking ahead: The bridge to part II
As we have established, the primary purpose of accounting is multifaceted: it bridges information gaps, enforces stewardship, drives internal operational decisions, and provides the bedrock of trust upon which modern capital markets rest. Without accounting, commerce would devolve into localized barter systems, capital would stall, and economic growth would grind to a halt.
In the subsequent section of this expert analysis, we will transition from the foundational philosophy of accounting to its structural mechanics and practical manifestations, exploring how financial statements function as interconnected economic mirrors, how accounting standards ensure global comparability, and how emerging digital technologies are reshaping the accountant's role from historical scorekeeper to strategic architect.
Beyond the numbers: Facilitating Strategic Decision-Making
While recording transactions and balancing ledgers form the bedrock of daily bookkeeping, the true purpose of accounting extends far beyond historical record-keeping. At its highest organizational level, accounting serves as the primary navigation system for business strategy.
Management teams cannot steer a company forward by intuition alone. They require empirical evidence, structured data, and rigorous financial analysis to answer critical operational questions:
Capital Allocation: Which product lines are generating sustainable margins, and which are draining cash reserves?
Cost-Benefit Analysis: Can the organization afford to expand into a new regional market, or should capital be reinvested into research and development?
Operational Efficiency: Where are the bottlenecks in the supply chain that inflate production costs?
Through sophisticated techniques such as managerial accounting, variance analysis, and cost-volume-profit modeling, accountants transform raw data into actionable insights. By establishing key performance indicators (KPIs) and variance reports, accounting allows executives to compare actual performance against projected forecasts, identifying deviations early enough to implement corrective action.
Ensuring transparency, Compliance, and accountability
Another vital pillar of accounting is its role as the guardian of institutional integrity. Modern economies rely heavily on trust, trust that the financial figures reported by corporations are accurate, verifiable, and free from material misstatement.
Regulatory Compliance and taxation
Every jurisdiction enforces strict legal obligations regarding corporate reporting. Financial accounting ensures that organizations adhere to globally recognized frameworks, such as GAAP (Generally Accepted Accounting Principles) or IFRS (International Financial Reporting Standards). These standardized guidelines ensure uniformity across industries, allowing tax authorities, regulatory bodies, and government agencies to calculate accurate corporate tax liabilities and verify adherence to labor and trade laws.
Safeguarding stakeholder trust
When external parties, such as shareholders, bondholders, and financial institutions, invest capital, they do so with the expectation of transparency. Independent audits, performed by certified public accountants (CPAs), provide an objective examination of a company’s financial statements. This external validation mitigates information asymmetry, protecting investors from fraud, mismanagement, and hidden liabilities.
Accounting as the universal language of business
Commerce transcends linguistic, cultural, and geographic borders, but financial communication requires a universal syntax. Accounting provides this common tongue.
Whether an investor is located in Tokyo, London, or New York, a properly prepared balance sheet, income statement, and cash flow statement convey the exact same economic reality:
Liquidity and Solvency: Can the company meet its short-term obligations and service its long-term debt?
Profitability: Is the business generating adequate returns on equity and invested capital?
Operational Cash Flow: Is net income backed by actual cash generation, or is it tied up in uncollected receivables and bloated inventory?
By standardizing how assets, liabilities, revenues, and expenses are measured and reported, accounting enables efficient capital markets. Without this universal clarity, international trade and cross-border investment would grind to a halt due to excessive financial uncertainty.
The evolving role of Accounting in the Digital age
As we look toward the future, the scope and purpose of accounting are undergoing a profound transformation driven by technological innovation. Artificial intelligence, robotic process automation (RPA), and cloud-based enterprise resource planning (ERP) systems are automating routine data entry and transaction matching.
Rather than diminishing the value of the profession, this technological shift elevates the accountant's role from a historical scorekeeper to a strategic business partner. With automated systems handling compliance and data compilation, accounting professionals increasingly focus on:
Predictive Analytics: Leveraging big data to forecast future market trends, customer behavior, and cash flow risks.
Risk Management: Identifying cybersecurity vulnerabilities in digital financial systems and evaluating macroeconomic exposures.
Strategic Advisory: Collaborating directly with executive leadership to design tax-efficient corporate structures and long-term growth roadmaps.
Conclusion
The main purpose of accounting is to provide decision-useful information that empowers individuals, organizations, and societies to allocate scarce resources effectively. By bridging the gap between raw economic activity and transparent, structured reporting, accounting establishes the foundation upon which modern commerce, investment, and economic stability are built.