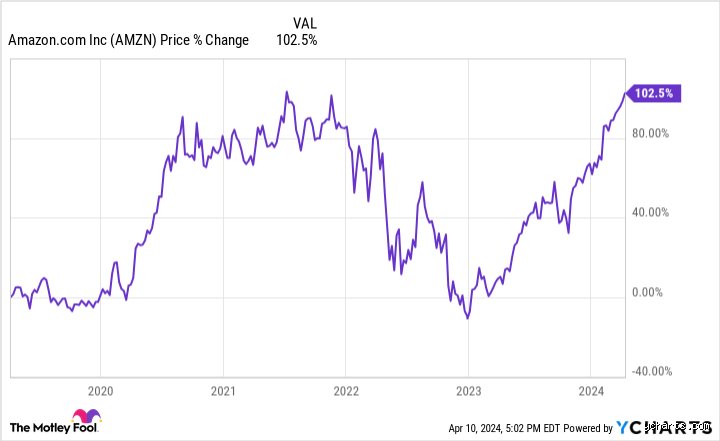
Decoding the next five years: What will Amazon stock be worth?
With a massive market capitalization hovering near $2.8 trillion, Amazon is long past its days of hyper-growth as a purely online bookstore or novelty digital storefront. Today, it operates as a multi-headed corporate titan spanning global e-commerce, third-party logistics infrastructure, high-margin digital advertising, and cloud computing dominance. Looking out toward the horizon of the next half-decade, forecasting Amazon’s share price requires dissecting how these core pillars will evolve, how artificial intelligence (AI) capital expenditures will translate into tangible free cash flow, and how macroeconomic pressures will shape consumer spending behavior.
The core pillars driving Amazon’s Five-Year trajectory
To evaluate where Amazon stock is heading, we must look closely at the engines propelling its financial engine. No longer reliant solely on selling goods to retail consumers at razor-thin margins, Amazon has transformed into a diversified conglomerate where profitability is heavily skewed toward cloud infrastructure and programmatic advertising.
1. Amazon Web Services (AWS) and the artificial intelligence Super-Cycle
The single most critical determinant of Amazon’s five-year valuation remains Amazon Web Services (AWS). As enterprises worldwide accelerate their transition to the cloud and race to integrate generative artificial intelligence models into their operations, AWS acts as the foundational picks-and-shovels provider for the modern digital economy.
Re-Acceleration and Backlog: Recent quarters have underscored a powerful re-acceleration in AWS growth rates, backed by massive multi-billion-dollar enterprise commitments and contract pipelines that span multiple years.
The AI Infrastructure Play: Amazon is deploying staggering amounts of capital into data centers, specialized chips, and power infrastructure. Over the next five years, the crucial test for AWS will not just be capturing market share against Microsoft Azure and Google Cloud, but successfully monetizing these capital-intensive AI investments to expand operating margins. If enterprise demand for AI-driven workloads scales as projected, AWS alone could approach staggering revenue milestones by the end of the decade, serving as the bedrock for the company’s valuation.
2. Digital advertising: The High-Margin profit engine
While retail e-commerce catches headlines for its volume, Amazon’s digital advertising segment has quietly matured into one of the most lucrative advertising ecosystems in the world.
Capital-Light Expansion: Benefiting from prime real estate across its marketplace—where high-intent shoppers go with credit cards already in hand—Amazon's advertising revenue has scaled rapidly.
Margin Accretion: Unlike physical retail, advertising carries exceptional operating margins. Over the next five years, continued expansion in sponsored product listings, Prime Video ad integration, and streaming real estate will inject high-margin cash flow directly into Amazon’s bottom line, buffering the company against retail supply chain cost inflation.
3. E-Commerce efficiency and regional fulfillment networks
Amazon’s traditional retail and third-party seller services have undergone a massive structural overhaul. By decentralizing its U.S. fulfillment network into distinct regional hubs, Amazon has drastically slashed cost-to-serve metrics, shortened delivery times, and improved unit economics. Over the next five years, further automation through robotics and AI-driven inventory forecasting will continue to squeeze inefficiencies out of the physical retail network, ensuring that the commerce side of the house contributes meaningfully to operating income rather than acting as a drag on margins.
Macroeconomic tailwinds, headwinds, and valuation multiples
A five-year forecast cannot exist in a vacuum; it must account for broader macroeconomic realities, interest rate cycles, and market valuation multiples.
Capital Expenditure vs. Free Cash Flow: The multi-hundred-billion-dollar wave of AI infrastructure spending has sparked debate among value and growth investors alike. Bulls argue that these investments are essential moats that will lock in enterprise customers for a generation. Bears caution that heavy depreciation schedules and massive capital outlays could compress near-term free cash flow. How Amazon balances aggressive infrastructure spending with shareholder returns over the next 3 to 5 years will heavily influence its Price-to-Earnings (P/E) multiple.
Wall Street Consensus and Analyst Sentiment: Current institutional consensus places Amazon firmly in "Strong Buy" territory, with long-term algorithmic projections and analyst price targets pointing toward substantial upside as AWS and advertising revenues compound. Depending on the pace of margin expansion, consensus models frequently map out paths where AMZN outpaces the broader S&P 500, supported by structural operating leverage.
(This concludes the first part of our deep-dive analysis on Amazon’s five-year stock outlook. Stay tuned for Part 2, where we break down specific multi-year financial simulation models, bull/bear price targets, and portfolio strategy considerations.)
Catalyst #3: Digital advertising margins and the High-Yield retail flywheel
While cloud infrastructure captures the primary share of institutional enthusiasm, Amazon's rapid ascent as a dominant digital advertising powerhouse serves as the hidden engine of its margin expansion. Advertising revenue continues to compound at a remarkable clip, climbing past a multi-billion dollar annualized run rate.
Unlike traditional retail fulfillment, sponsored listings and native ecosystem ads operate at exceptionally high gross margins. Over the next five years, as brands increasingly shift marketing budgets from legacy linear channels to point-of-sale digital environments, Amazon’s ad monetization capacity within its marketplace and Prime Video streaming interface will fundamentally reshape its consolidated cash flow profile.
Financial modeling: Projecting valuation through 2031
To evaluate what Amazon stock will genuinely be worth five years from now, analysts look at three interconnected financial levers:
CapEx Normalization: The massive front-loaded capital expenditures currently dedicated to data centers and generative AI infrastructure are projected to normalize, unlocking a steep acceleration in free cash flow.
Operating Income Scaling: With AWS maintaining high-growth acceleration and advertising forming a larger percentage of total revenue mix, consolidated operating margins are anticipated to expand well past historical retail averages.
Consensus Price Targets: Wall Street consensus highlights a strong baseline expectation, with major institutional tracking indicating average 12-month targets climbing past $320–$330, and 5-year compound valuation models pointing toward a steady baseline target between $460 and $500 per share assuming a stable forward P/E multiple and a conservative 12% annualized earnings growth rate.
Summary and investor outlook
Amazon's 5-year trajectory depends on its transition from a traditional e-commerce giant into a high-margin technology conglomerate powered by cloud dominance, enterprise AI integration, and targeted digital advertising. While short-term macroeconomic volatility and heavy capital outlays will test investor patience, the long-term structural tailwinds remain exceptionally robust.