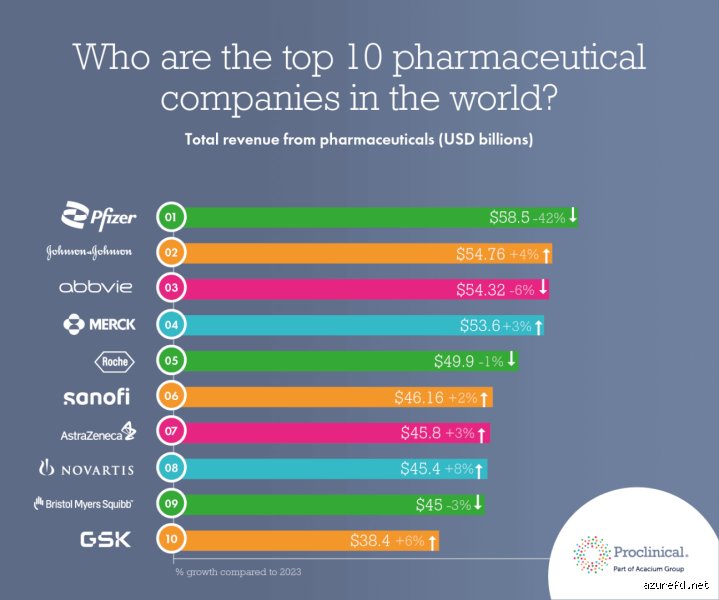
The Multibillion-Dollar ecosystem of modern medicine
Evaluating who truly holds the title of the "largest pharmaceutical company" involves examining more than simple revenue tickers. Analysts must distinguish between total corporate revenue—which for conglomerates like Johnson & Johnson or Roche may encompass medical technologies, consumer health spin-offs, diagnostics, or animal health units—and pure prescription pharmaceutical sales. Market capitalization paints a separate, highly volatile picture, often shifting dramatically based on clinical trial readouts, patent cliffs, and regulatory approvals.
Based on fiscal performance data and prescription drug sales, the landscape of global pharma features titans characterized by massive research and development (R&D) budgets, global footprints spanning over a hundred countries, and workforces numbering in the tens of thousands.
Defining the metrics: Revenue vs. Market Capitalization
Before diving into the specific rankings, it is essential to understand how industry size is quantified. Two primary metrics dominate financial and commercial evaluations:
Total Revenue vs. Pharmaceutical-Specific Revenue: Many legacy healthcare giants are diversified. For instance, Johnson & Johnson generates substantial income from its expansive MedTech division, while Roche maintains a massive diagnostics branch. Conversely, companies like Eli Lilly and Pfizer focus almost entirely on biopharmaceuticals. When ranked strictly by prescription drug and vaccine revenue, the leaderboard shifts significantly.
Market Capitalization: Driven by investor sentiment, future drug pipelines, and commercial successes (such as the meteoric rise of metabolic and weight-management treatments like GLP-1 receptor agonists), market cap reflects the perceived future value of a company rather than just its historical sales ledger.
With these parameters established, we begin our countdown of the world's leading pharmaceutical companies, starting with numbers ten down to six.
10. Bristol Myers Squibb (BMS)
Headquarters: Princeton, New Jersey, USA
Core Therapeutic Focus: Oncology, Hematology, Immunology, and Cardiovascular Disease
Approximate Annual Revenue: ~$48.2 billion
Bristol Myers Squibb secures its position among the world's top ten pharmaceutical companies through a steadfast commitment to transformative science in areas of high unmet medical need. BMS has historically excelled in immuno-oncology, a field that harnesses the body's own immune system to fight cancer.
The company's portfolio features critical anchor assets, including blockbuster treatments for various forms of cancer and autoimmune diseases. However, like many legacy pharmaceutical giants, BMS has had to aggressively manage upcoming patent expirations on several foundational legacy drugs. To sustain its growth trajectory, the company has heavily invested in business development, executing multi-billion-dollar acquisitions to bolster its pipeline in neuroscience, targeted protein degradation, and advanced cellular therapies (CAR-T). With a dedicated workforce of over 30,000 employees, BMS maintains a robust R&D engine designed to transition early-stage laboratory breakthroughs into commercialized specialty medicines.
9. Sanofi
Headquarters: Paris, France
Core Therapeutic Focus: Immunology, Vaccines, Rare Diseases, Neurology, and Oncology
Approximate Annual Revenue: ~€43.6 billion / ~$49.3 billion
Representing Europe's strong footprint in the global life sciences sector, Sanofi stands as a French multinational pharmaceutical and healthcare leader. Sanofi’s business model is uniquely balanced between innovative specialty care, traditional general medicines, and a globally renowned vaccines business (Sanofi Pasteur), which supplies hundreds of millions of vaccine doses worldwide each year to prevent influenza, polio, and other infectious diseases.
In recent years, Sanofi has undergone a strategic transformation, pivoting sharply away from lower-margin primary care lines to focus heavily on immunology and breakthrough biologics. A prime driver of this strategy has been its blockbuster immunology partnership, which treats conditions such as atopic dermatitis, asthma, and other chronic inflammatory diseases. Sanofi's commitment to digital transformation, artificial intelligence in drug discovery, and expanding manufacturing capabilities across Europe and North America ensures its ongoing influence on global public health.
8. Novartis
Headquarters: Basel, Switzerland
Core Therapeutic Focus: Cardiovascular, Renal, and Metabolic, Immunology, Neuroscience, and Oncology
Approximate Annual Revenue: ~$54.5 billion
Headquartered in Basel, Switzerland, Novartis represents the pinnacle of modern, focused innovative medicines. Following the successful spin-off of its generics and biosimilars division (Sandoz), Novartis streamlined its corporate identity to concentrate entirely on high-value, patent-protected innovative therapeutics.
Novartis boasts a powerhouse R&D infrastructure capable of delivering breakthrough treatments in complex disease areas. The company is a pioneer in advanced technology platforms, including radioligand therapies for targeted cancer treatment, gene therapies, and RNA-based therapeutics. With a global workforce exceeding 75,000 employees, Novartis consistently ranks near the top of international corporate responsibility and access-to-medicine indexes, balancing commercial profitability with large-scale global health distribution initiatives aimed at reaching underserved populations in developing nations.
7. AstraZeneca
Headquarters: Cambridge, United Kingdom
Core Therapeutic Focus: Oncology, Rare Diseases, Cardiovascular, Renal, Metabolism, and Respiratory & Immunology
Approximate Annual Revenue: ~$58.7 billion
AstraZeneca, co-headquartered in Cambridge, UK, has experienced one of the most remarkable transformations in modern pharmaceutical history. Once viewed as a traditional primary-care-focused enterprise, the company executed a bold strategic overhaul under visionary leadership, doubling down on science-led oncology and precision medicine.
Today, AstraZeneca's revenue is anchored by a formidable suite of targeted cancer therapies, respiratory inhalers, and rare disease treatments (bolstered by its major acquisition of Alexion). The company invests heavily in next-generation science, exploring antibody-drug conjugates (ADCs), cell therapies, and novel immune-mediated disease mechanisms. Operating in nearly every country worldwide with close to 100,000 employees, AstraZeneca's robust pipeline and aggressive global footprint cement its status as a pillar of European and international biopharma.
6. AbbVie
Headquarters: North Chicago, Illinois, USA
Core Therapeutic Focus: Immunology, Oncology, Neuroscience, Eye Care, and Aesthetics
Approximate Annual Revenue: ~$61.2 billion
Spun off from Abbott Laboratories as an independent biopharmaceutical entity, AbbVie quickly established itself as a commercial powerhouse. For over a decade, the company's flagship immunology drug dominated global pharmaceutical sales charts, generating historic revenue streams that funded extensive pipeline diversification.
Faced with the inevitable loss of exclusivity for its legacy blockbuster, AbbVie executed a masterclass in strategic portfolio management. By successfully launching and scaling next-generation immunological successors, alongside strategic acquisitions in areas like migraine therapeutics, oncology (notably through its multi-billion-dollar purchase of Allergan), and medical aesthetics, AbbVie successfully protected its top-tier revenue standing. Employing roughly 57,000 people globally, AbbVie exemplifies how agile lifecycle management and aggressive clinical development can sustain a pharmaceutical giant through massive market transitions.
End of Part 1. Continue to Part 2 for an analysis of the top five pharmaceutical powerhouses, emerging industry trends, and the future outlook of global healthcare innovation.
...as global healthcare needs continue to evolve at a blistering pace.
The vanguard of biopharmaceutical innovation
When examining the upper echelon of the global pharmaceutical landscape, market dynamics are increasingly dictated by a shift toward targeted therapies, advanced biologics, and transformative metabolic treatments. The traditional dominance of legacy small-molecule blockbusters has been complemented, and in many cases eclipsed, by innovations in areas such as oncology, immunology, and metabolic disorders.
Companies like Eli Lilly and Novo Nordisk have experienced historic ascents driven by unprecedented demand for incretin-based therapies (such as GLP-1 receptor agonists) targeting type 2 diabetes and obesity. This metabolic revolution has fundamentally reshaped market capitalizations, pushing front-runners past historic valuation milestones and forcing legacy powerhouses to aggressively restructure their pipelines through high-stakes mergers and acquisitions.
Key drivers shaping the top tier
The Patent Cliff and Loss of Exclusivity (LOE): Several foundational blockbusters face imminent generic and biosimilar competition. Corporations are actively executing strategic business development deals to acquire mid-to-late-stage clinical assets, ensuring continuous top-line momentum.
Precision Oncology and ADCs: Antibody-drug conjugates (ADCs) have emerged as a cornerstone of cancer treatment, allowing targeted cytotoxic delivery directly to tumor cells while sparing healthy tissue. Partnerships between major global players and nimble biotechnology firms specializing in ADCs have surged.
Artificial Intelligence in Drug Discovery: Machine learning algorithms and AI-driven target identification are now standard across R&D divisions, radically compressing timelines from initial hit-to-lead optimization through clinical candidate selection.
Strategic outlook and future horizons
As the industry navigates complex macroeconomic headwinds, pricing pressures, and evolving regulatory frameworks, the boundary lines between traditional pharmaceuticals and cutting-edge biotechnology continue to blur. The giants securing their positions in the global top ten are those capable of balancing near-term commercial execution with aggressive, diversified investments in cell therapy, gene editing, and RNA therapeutics.
Leadership within the pharmaceutical sector remains dynamic. Sustained success depends not only on defending existing franchises against looming generic erosion but also on pioneering the next generation of breakthrough modalities that redefine standards of care worldwide.