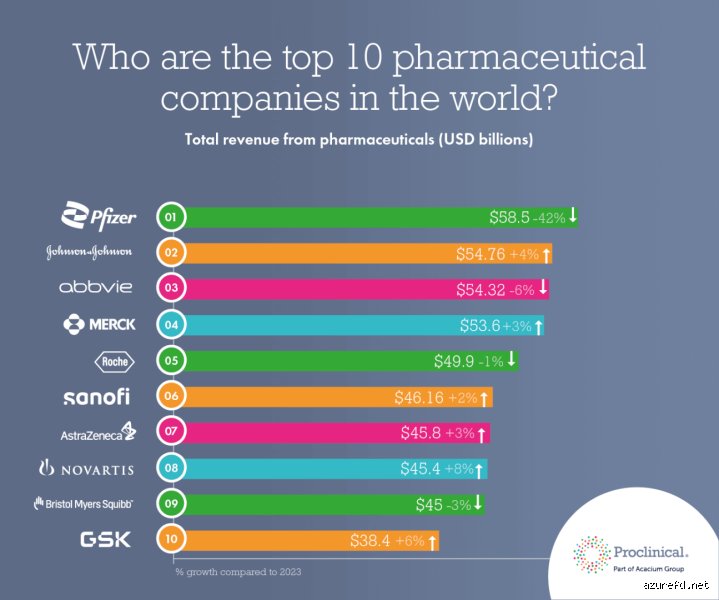
The High-Stakes race for Global pharma dominance
At first glance, answering this question might appear straightforward. One could simply pull a spreadsheet of annual corporate earnings, sort the entries from highest to lowest, and declare a winner. However, the pharmaceutical landscape is notoriously complex. Defining the "top" company depends heavily on the metrics used. Do we measure dominance by total gross revenue, net profit margins, pure prescription drug sales (excluding medical devices or consumer health products), or the sheer impact of a company's research and development (R&D) pipeline on global public health? Structural shifts—such as major corporate spin-offs, post-pandemic market normalization, and the explosive rise of revolutionary metabolic and oncological therapies—have drastically reshaped the leaderboard.
As the industry navigates a transformative era defined by breakthrough biologics, artificial intelligence in drug discovery, and looming patent expirations for historic blockbusters, the crown for the world’s top pharma company is fiercely contested. This comprehensive expert analysis explores the multi-faceted criteria behind industry rankings, evaluates the titans currently vying for the top spot, and examines what truly drives supremacy in modern biopharmaceuticals.
Defining "top": Revenue vs. Therapeutic impact
To understand who reigns supreme, we must first dissect how the industry measures success. Unlike standard retail or tech sectors where revenue is a singular, clean metric, the pharmaceutical sector is encumbered by varying business models.
1. Gross revenue vs. Pure-Play pharma
Some contenders, such as Johnson & Johnson (J&J), operate as massive diversified healthcare conglomerates. J&J commands staggering total revenues fueled not only by its innovative medicine division but also by a massive global MedTech footprint (surgical equipment, orthopedics, and vision care). When looking strictly at total corporate top-line figures, J&J regularly hovers near or above the $90–$100 billion threshold, making it a financial heavyweight.
Conversely, companies like Pfizer, Eli Lilly, and Merck & Co. operate closer to "pure-play" biopharmaceutical models, deriving nearly 100% of their revenues directly from prescription therapeutics and vaccines. When analysts evaluate pure pharmaceutical drug sales alone, the hierarchy shifts significantly, occasionally unseating diversified giants in favor of companies whose portfolios are hyper-focused on high-margin specialty drugs.
2. The power of the blockbuster drug
A single revolutionary molecule can single-handedly elevate a mid-tier player into a global powerhouse. Historically, drugs like Pfizer’s cholesterol-lowering Lipitor or AbbVie’s anti-inflammatory juggernaut Humira defined corporate fortunes for decades. In recent years, the market has witnessed a seismic shift driven by oncology breakthroughs, such as Merck’s Keytruda, and the meteoric rise of GLP-1 receptor agonists for diabetes and chronic weight management, spearheaded by Eli Lilly and Novo Nordisk. A company whose flagship product anchors the global prescription volume chart often exerts an influence that stretches far beyond raw financial statements.
The Contenders for the Crown
While rankings fluctuate quarter by quarter based on currency exchange rates, patent cliffs, and clinical trial results, a distinct tier of elite multinational corporations consistently battles for the top positions.
Johnson & Johnson: The diversified titan
For years, Johnson & Johnson has anchored the conversation surrounding the largest healthcare companies on earth. Following the strategic spin-off of its consumer health division (Kenvue), J&J sharpened its focus heavily on its two core pillars: Innovative Medicine and MedTech.
The Strategy: By balancing cutting-edge oncology, immunology, and neuroscience treatments with an indispensable medical technology business, J&J maintains a uniquely resilient financial structure.
Market Position: With annual pharmaceutical and medical revenues pushing toward the $100 billion milestone, J&J relies on established oncology blockbusters like Darzalex alongside a robust pipeline of surgical and diagnostic devices to defend its standing.
Merck & Co.: The oncology heavyweight
U.S.-based Merck & Co. (known outside North America as MSD) has long been a formidable force in global health, driven largely by one of the most successful commercial pharmaceutical products in history: Keytruda (pembrolizumab).
The Strategy: Merck’s strategic focus on immuno-oncology and vaccines (such as the Gardasil franchise for HPV prevention) has yielded extraordinary financial returns. Keytruda alone accounts for a massive share of the company's annual revenue, routinely pulling in close to or exceeding $25 billion to $30 billion annually.
The Challenge: While Keytruda has cemented Merck’s position near the summit, the looming threat of patent expirations toward the latter half of the decade has forced the company into an aggressive posture of pipeline diversification through strategic acquisitions and internal R&D expansion.
Eli Lilly and the metabolic revolution
Few corporate trajectories in recent history match the explosive ascent of Eli Lilly. Historically respected for its long-standing leadership in diabetes care (including the mass production of insulin and early GLP-1 treatments), Lilly has transformed into one of the most valuable healthcare entities in the world.
The Strategy: The catalyst for this unprecedented growth is the twin-engine success of Mounjaro (tirzepatide) for type 2 diabetes and Zepbound for chronic weight management. Global demand for these metabolic therapies has shattered historical pharmaceutical sales velocity records.
Market Position: Driven by double-digit quarterly revenue surges and massive capital investments in state-of-the-art biomanufacturing facilities, Eli Lilly has rapidly closed the gap with traditional revenue leaders, challenging the very definition of who leads the global pharma sector.
Pfizer: Navigating the Post-Pandemic era
Pfizer captured the world's attention during the global health crisis, leveraging its mRNA technology platform and massive global distribution network to post unprecedented, record-breaking revenues.
The Strategy: In the wake of normalized demand for pandemic-era products, Pfizer has actively re-engineered its long-term outlook. The company has poured billions into aggressive mergers and acquisitions, most notably its multi-billion-dollar acquisition of Seagen, to fortify its next-generation oncology portfolio.
Market Position: Despite post-pandemic revenue adjustments, Pfizer’s immense global footprint, extensive manufacturing infrastructure, and diversified portfolio across vaccines, rare diseases, and internal medicine ensure it remains a perennial top contender in global biopharmaceutical output.
Global perspectives: European powerhouses and international giants
While U.S. multinationals frequently dominate headlines regarding top-line revenues, the global pharmaceutical ecosystem is deeply decentralized, featuring massive international players with multi-billion-dollar footprints.
Roche (Switzerland): Combining a world-leading pharmaceutical division with an advanced diagnostics branch, Roche excels at bridging the gap between disease detection and targeted therapeutics. Its dominant oncology and ophthalmology portfolios give it exceptional defensive strength in global markets.
Novartis (Switzerland): Following the successful spin-off of its generics unit, Sandoz, Novartis successfully repositioned itself as a pure-play, highly focused innovative medicines company centering on cardiovascular, renal, metabolic, immunology, and neuroscience therapies.
AstraZeneca (Sweden/UK): Driven by robust growth across its global oncology, cardiovascular, and rare disease portfolios, AstraZeneca has maintained stellar operational momentum through aggressive international expansion and a heavy commitment to advanced scientific platforms.
Novo Nordisk (Denmark): Alongside Eli Lilly, Novo Nordisk has rewritten the rules of modern metabolic care. Propelled by the global phenomenon of its diabetes and weight-loss treatments (such as Ozempic and Wegovy), the Danish drugmaker has experienced historic financial expansion, dramatically elevating its standing among the world's elite healthcare firms.
(This concludes Part 1 of the expert analysis on the world's leading pharmaceutical companies. The evaluation of R&D investment strategies, patent cliffs, and the future outlook of industry leadership will continue in subsequent sections.)
Financial realignment: Revenue vs. Scope
When evaluating who truly claims the crown of the world's top pharma company, analysts must differentiate between total corporate revenue (which often incorporates massive medical technology, consumer health, or animal health divisions) and pure-play pharmaceutical and vaccine sales.
Traditional giants like Johnson & Johnson (J&J) frequently capture headlines for total overall healthcare revenue, crossing the monumental $94 billion total sales threshold, backed heavily by its expansive MedTech sector. However, when isolating pure pharmaceutical revenue, the landscape shifts dramatically. Competitors such as Eli Lilly, Pfizer, Merck & Co., and AbbVie trade blows for supremacy, driven by high-margin biologic blockbusters and tectonic shifts in global healthcare demand.
The metabolic Super-Cycle: Eli Lilly and Novo Nordisk's ascent
The primary catalyst rewriting the pharma leaderboard is the explosive, unprecedented demand for incretin-based therapies, specifically GLP-1 receptor agonists targeting type 2 diabetes and chronic weight management.
Eli Lilly has captured the imagination of Wall Street and patients alike, surging into the top tier with explosive year-over-year revenue growth. Fueled by the astronomical global adoption of Mounjaro and Zepbound, Lilly's pure pharmaceutical revenue crossed historic milestones, pushing past $65 billion.
Simultaneously, Denmark's Novo Nordisk has climbed aggressively through the global ranks, driven by the unstoppable momentum of its own metabolic portfolio.
This metabolic super-cycle represents a rare historical anomaly: therapeutic products achieving consumer-brand recognition on a global scale, transforming specialized drugmakers into multi-hundred-billion-dollar market titans almost overnight.
The battle of oncology and immunology heavyweights
While metabolic drugs capture public attention, foundational giants continue to defend their territories through oncology and immunology dominance:
Merck & Co. remains an absolute powerhouse, anchored almost entirely by Keytruda (pembrolizumab). As one of the best-selling prescription drugs in human history, Keytruda anchors Merck near the pinnacle of pure-play pharma. However, impending patent expirations toward the latter half of the decade mean Merck, like its peers, is under immense pressure to diversify via strategic multi-billion-dollar acquisitions in antibody-drug conjugates (ADCs) and cardiovascular disease pipelines.
AbbVie successfully engineered one of the most effective life-cycle management transitions in industry history. Even as its historic immunology mega-blockbuster Humira faced severe biosimilar erosion, successors Skyrizi and Rinvoq stepped into the breach with staggering double-digit quarterly growth, keeping AbbVie securely among the elite top tier of global biopharma.
Roche and Novartis, Switzerland’s twin pillars of innovation, continue to rely on deep-bench pipelines spanning ophthalmology (Vabysmo), multiple sclerosis (Ocrevus), and advanced oncology. Roche's unique integration of diagnostics and pharmaceuticals provides a structural advantage in precision medicine that few competitors can replicate.
Strategic challenges ahead: The Patent Cliff and regulatory Pressures
As the industry looks toward the late 2020s, the race for the top spot is complicated by several converging headwinds:
The Looming Patent Cliff: A wave of historic drug patents is expiring. Companies relying too heavily on single, aging blockbusters face steep revenue cliffs as generic and biosimilar competition enters the market. Consequently, top-tier ranking positions fluctuate rapidly based on who successfully buys or builds the next generation of pipeline assets.
Global Pricing Pressures: Legislative actions, such as drug price negotiation frameworks in the United States and tightening cost-containment measures across European health systems, are forcing executive boards to rethink pricing strategies and prioritize assets with undeniable, high-value health economic outcomes.
Advanced Modalities and R&D Shifts: Capital expenditure is increasingly shifting away from traditional small-molecule chemistry toward complex biologics, cell and gene therapies, mRNA platforms, and targeted radioligand therapies. The top pharma company of tomorrow will not simply be the one with the best sales force, but the one that most efficiently translates cutting-edge genetic insights into scalable clinical realities.
The Evolving Definition of "Top"
Declaring a single "top" pharma company depends entirely on the metric applied. If measured by diversified global healthcare footprint and total corporate scale, Johnson & Johnson maintains an unshakeable anchor. Yet, if measured by pure pharmaceutical innovation velocity, market cap expansion, and the sheer cultural and clinical footprint of its drug portfolio, Eli Lilly and its peers spearheading the metabolic revolution have redefined what modern pharmaceutical leadership looks like.
In an era defined by rapid biotechnology breakthroughs and shifting global disease burdens, the crown is no longer permanent; it belongs perpetually to the organization that can best navigate the delicate balance between breakthrough scientific risk and global patient access.