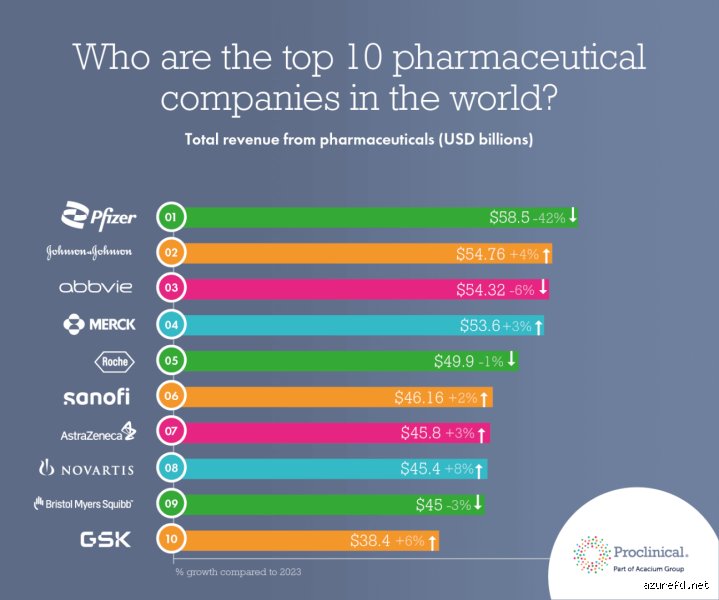
Depending on the specific metric utilized—whether one evaluates total prescription drug sales, overall corporate revenue including consumer health and medical devices, research and development (R&D) expenditure, global market capitalization, or geographical footprint—different corporate giants lay claim to the top position. Consequently, experts disagree on which single enterprise truly deserves the crown of global supremacy. Is it Johnson & Johnson, Pfizer, Roche, Novartis, or Merck & Co.? Each contender brings a distinct corporate structure, product portfolio, and strategic vision to the table, making a definitive coronation far more intricate than simple arithmetic might suggest.
To understand the modern pharmaceutical landscape, let's be clear about one fundamental reality: the pharmaceutical industry is not a monolith, nor is it stagnant. It is a hyper-dynamic, high-stakes ecosystem characterized by patent cliffs, multi-billion-dollar acquisitions, regulatory hurdles, and unpredictable scientific breakthroughs. A company that holds the number one spot by revenue in a given fiscal year might slip a few notches the next due to the expiration of a blockbuster drug patent or a major corporate spinoff. Therefore, answering the core question requires a comprehensive examination of the various metrics that define corporate magnitude in the life sciences sector.
Defining "bigness": The metrics of pharmaceutical dominance
To evaluate which entity stands at the apex of the global pharmaceutical industry, we must first establish the yardsticks by which size is measured. In corporate finance and industry analysis, four primary metrics dominate the conversation:
Total Prescription Drug Revenue (Core Pharma Sales): This metric isolates revenue generated strictly from the sale of prescription pharmaceuticals and biologics, excluding consumer health products, vaccines, medical devices, and animal health divisions. For purists, this is the most accurate reflection of a "pure-play" pharmaceutical powerhouse.
Total Corporate Revenue: This encompasses all revenue streams generated by the parent corporation, including medical devices, diagnostics, consumer health, and nutritional products. Under this broader umbrella, diversified healthcare giants often overshadow companies that focus exclusively on therapeutics.
Market Capitalization: Representing the total market value of a company's outstanding shares of stock, market capitalization reflects Wall Street’s sentiment, future growth expectations, and investor confidence. Unlike static annual revenue reports, market cap fluctuates daily based on macroeconomic trends, clinical trial results, and regulatory approvals.
Research and Development (R&D) Investment: While not a measure of sheer financial size per se, R&D spending indicates the sheer scale of operational commitment to scientific innovation, pipeline expansion, and future drug discovery.
These distinct metrics frequently yield different winners. A corporation might boast the highest overall market capitalization due to investor optimism regarding its oncology pipeline, while another generates superior net prescription sales through a heavily entrenched portfolio of immunology blockbusters.
The historical evolution of Pharma giants
The modern pharmaceutical industry as we know it today was forged through decades of aggressive mergers, acquisitions, and strategic realignments. For much of the late 20th century, the landscape was populated by numerous medium-to-large national players rooted primarily in the United States, Switzerland, Germany, the United Kingdom, and France. However, as the cost of bringing a single new molecular entity (NME) from bench discovery to commercial pharmacy shelves skyrocketed, often exceeding billions of dollars, smaller and mid-sized firms found it increasingly difficult to compete independently.
This economic reality triggered waves of mega-mergers during the late 1990s and throughout the 2000s. Pfizer acquired Warner-Lambert, Pharmacia, and later Wyeth, transforming itself into an acquisition-driven juggernaut capable of generating unprecedented revenue streams. Similarly, Novartis was born out of the massive 1996 merger between Ciba-Geigy and Sandoz, while Sanofi absorbed Aventis and Genzyme over successive decades to cement its place among global elite firms.
These historical consolidations mean that today's pharmaceutical giants are not merely individual companies; they are vast conglomerates comprising dozens of legacy brands, research laboratories, and manufacturing facilities spread across every inhabited continent. This historical context is essential for understanding why corporate structures vary so wildly across the current top-tier contenders.
Analyzing the top contenders
To ground our investigation, let us examine the primary contenders that consistently vie for the title of the world's largest pharmaceutical company. While rankings fluctuate from year to year based on quarterly earnings reports and currency fluctuations, a handful of names persistently anchor the top of global lists.
1. Johnson & Johnson (J&J): The diversified healthcare behemoth
When measured by total corporate revenue, Johnson & Johnson frequently secures the top position globally. Headquartered in New Brunswick, New Jersey, J&J operates on a scale that few other healthcare companies can match. However, any discussion of J&J must include a crucial caveat: its massive revenue is divided between its Innovative Medicine (pharmaceuticals) division and its MedTech (medical devices and diagnostics) sector.
Following the historic spin-off of its consumer health division into a separate entity named Kenvue, J&J sharpened its strategic focus heavily on high-margin pharmaceuticals and advanced medical technology. Its Innovative Medicine arm markets powerhouse therapeutics across immunology, oncology, neuroscience, and cardiovascular health. While J&J's combined enterprise revenue often eclipses that of pure-play pharmaceutical companies, purists occasionally argue that comparing a diversified MedTech-and-pharma hybrid directly against pure drug developers requires careful contextualization.
2. Pfizer: The Vaccine king and commercial titan
Pfizer, headquartered in New York City, has long been synonymous with commercial pharmaceutical might. For many years, Pfizer held the undisputed title of the world's largest prescription drug seller. The company's growth model historically relied on massive, bold mergers and acquisitions, coupled with a powerhouse sales and marketing apparatus capable of launching blockbuster drugs globally.
The COVID-19 pandemic propelled Pfizer into an entirely unprecedented financial stratosphere. Alongside its German partner BioNTech, Pfizer manufactured and distributed billions of doses of its mRNA-based vaccine, Comirnaty, alongside its antiviral treatment Paxlovid. This monumental public health effort generated historic annual revenues, briefly pushing Pfizer's total sales past the $100 billion threshold, a milestone previously unseen in the pharmaceutical sector.
As the acute phase of the pandemic recedes and demand for COVID-19 products normalizes, Pfizer has experienced post-pandemic revenue adjustments. Nevertheless, its underlying infrastructure, expansive R&D pipeline, and legacy commercial reach ensure its standing among the elite upper echelon of global healthcare.
3. Roche: The Swiss precision oncology leader
Based in Basel, Switzerland, F. Hoffmann-La Roche AG represents the pinnacle of European pharmaceutical excellence. Roche occupies a unique dual position in the global healthcare market as both the world's largest biotech company and a leading global provider of in-vitro diagnostics.
Roche’s strategic dominance is built heavily upon its mastery of oncology, immunology, ophthalmology, and infectious diseases. Through its major acquisitions and internal developments, most notably its long-standing majority ownership of Genentech in the United States, Roche pioneered targeted biological therapies that fundamentally transformed cancer treatment. Drugs such as Herceptin, Avastin, and Rituxan established Roche as an indispensable pillar of modern medicine.
Roche's unique integration of diagnostics and therapeutics under one corporate umbrella provides a strategic advantage in the era of personalized and precision medicine. By developing companion diagnostics alongside targeted drugs, Roche ensures that therapies are directed precisely at patient populations most likely to benefit, cementing its competitive moat.
4. Novartis: Redefining focus through strategic divestments
Another Basel-based titan, Novartis, has continually restructured its corporate identity to optimize operational efficiency and shareholder value. Formed via the 1996 mega-merger, Novartis historically maintained a sprawling portfolio that included pharmaceuticals, eye care (Alcon), consumer health, and generics (Sandoz).
In recent years, however, Novartis executed a series of decisive strategic pivots. The company spun off Alcon and, more recently, completely unbundled its generic and biosimilar division, Sandoz, to transform into a "pure-play" innovative medicines enterprise. By shedding lower-margin generic operations, Novartis sharpened its strategic focus entirely on core therapeutic areas: cardiovascular-renal-metabolic diseases, immunology, neuroscience, and oncology. This leaner, highly specialized operational model allows Novartis to channel immense capital directly into cutting-edge modalities such as gene therapies, radioligand therapies, and advanced biologics.
5. Merck & Co. (MSD outside the US & Canada): The power of a single blockbuster
Headquartered in Rahway, New Jersey, Merck & Co. (known as MSD outside North America) represents a classic pharmaceutical heavyweight that owes much of its recent valuation to one of the most successful therapeutic products in medical history: Keytruda (pembrolizumab).
Keytruda, an immuno-oncology checkpoint inhibitor, has achieved staggering global sales, capturing indications across dozens of distinct cancer types. As patents for older blockbusters began to expire across the industry, Keytruda emerged as a cash-generating engine, fueling Merck’s aggressive internal research initiatives and external business development.
To mitigate its reliance on a single product facing future patent expirations, Merck has actively pursued strategic acquisitions, such as its multi-billion-dollar purchase of Prometheus Biosciences to bolster its immunology portfolio. This proactive pipeline diversification exemplifies the relentless balancing act required to maintain top-tier status in the global pharmaceutical arena.
The complex interplay of scale, risk, and innovation
Evaluating the true magnitude of these pharmaceutical giants requires looking beyond raw balance sheets to understand the inherent risks of drug development. Unlike consumer goods companies that can reliably forecast product lifecycles over decades, pharmaceutical enterprises operate in an environment of immense scientific uncertainty.
A single clinical trial failure in Phase III development can wipe out billions of dollars in invested capital and instantly alter a company's market standing. Conversely, the successful commercialization of a breakthrough therapeutic for obesity, Alzheimer's disease, or rare genetic disorders can catapult a mid-tier firm into the upper echelons of global market capitalization almost overnight.
This volatile relationship between risk and reward explains why financial leadership shifts so frequently. While conglomerates like Johnson & Johnson offer stability through diversified business segments, pure-play biotechnology leaders like Roche or specialized pharmaceutical giants like Pfizer and Merck demonstrate how focused scientific execution can dictate global dominance.
Conclusion of Part 1
As we have explored, determining the biggest pharma company in the world is not a matter of pointing to a single undisputed ledger. The answer depends heavily on whether one defines size through diversified healthcare revenue, pure prescription drug sales, market valuation, or scientific R&D commitment.
In the second part of this analysis, we will examine the rising challengers from emerging markets, the profound impact of biotechnology startups, the impending threat of upcoming patent cliffs, and how geopolitical shifts are reshaping the future hierarchy of global healthcare leadership.
The shifting paradigm: Market cap vs. Pure Pharma Revenue
When evaluating who holds the crown as the biggest pharmaceutical company in the world, industry analysts immediately confront a fundamental classification dilemma: do we measure size by stock market valuation (market capitalization), overall corporate revenue (which may include medical devices or consumer health), or strictly by prescription drug and vaccine sales?
Depending on the chosen metric, the title shifts dynamically among US and European giants. This complexity reflects an industry undergoing its most rapid transformation in decades, driven by massive shifts in cardiometabolic blockbusters, oncology breakthroughs, and post-pandemic realignment.
The contenders for the global crown
1. Eli Lilly: The Valuation and growth phenomenon
Driven by the explosive global demand for its incretin-based therapies (such as tirzepatide for diabetes and weight management), Eli Lilly (USA) has surged to unprecedented heights. With a market capitalization comfortably eclipsing the trillion-dollar mark, Lilly represents the modern archetype of a high-growth biopharmaceutical powerhouse. Its annual prescription drug revenues have climbed past $65 billion, propelled by unprecedented adoption rates of its flagship cardiometabolic franchises.
2. Johnson & Johnson: The diversified Revenue titan
If the definition of "biggest" relies on absolute top-line corporate revenue, Johnson & Johnson (USA) remains an unmatched juggernaut. Crossing historic milestones toward a $100 billion annual midpoint, J&J balances its pharmaceutical arm (Innovative Medicine) with a massive global MedTech footprint (spanning surgical systems, orthopedics, and electrophysiology). Even when isolating strictly pharmaceutical revenues, anchored by oncology mainstays like Darzalex and immunology assets like Tremfya, J&J commands a top-tier global presence.
3. Merck & Co. (MSD): The power of oncology
For years, Merck & Co. held a commanding position near the very top of pure pharmaceutical sales, largely on the back of Keytruda (pembrolizumab), the world’s single best-selling prescription checkpoint inhibitor. Generating well over $60 billion annually, Merck maintains an aggressive R&D investment profile, routinely pouring upwards of $15 billion back into clinical pipelines to insulate itself against upcoming patent expirations.
4. Global giants: Roche, Pfizer, AbbVie, and AstraZeneca
Roche: The Swiss multinational balances a dual powerhouse model of pharmaceuticals and advanced diagnostics, consistently pulling in robust revenues near the $60–70 billion threshold through core franchises in ophthalmology (Vabysmo), neurology (Ocrevus), and oncology.
Pfizer: Having navigated the post-pandemic normalization of its vaccine and antiviral revenues, Pfizer continues to anchor itself among the world's elite drugmakers through a diverse portfolio spanning rare diseases, cardiovascular blockbusters (Eliquis), and strategic oncology acquisitions.
AbbVie: Successfully managing the post-Humira patent cliff through next-generation immunology blockbusters Skyrizi and Rinvoq, AbbVie commands a premier position in global biopharmaceutical revenues.
AstraZeneca: Headquartered in the UK, AstraZeneca has maintained stellar high-single-digit growth rates driven by an oncology and rare disease pipeline featuring blockbusters like Tagrisso and Farxiga.
Strategic drivers reshaping the leaderboard
The competition for the number-one spot is no longer just about maintaining legacy cash cows; it is defined by three core structural pillars:
The GLP-1 and Cardiometabolic Supercycle: The race to address obesity, type 2 diabetes, and associated cardiometabolic conditions has fundamentally re-architected top-line growth. Companies dominating this space have rewritten historical sales velocities.
The Patent Cliff and M&A Replenishment: As first-generation biologics and small-molecule blockbusters face generic and biosimilar erosion, market leaders routinely deploy tens of billions of dollars in "bolt-on" mergers and acquisitions to acquire promising early-stage biotech assets.
R&D Intensity: The modern pharma leader invests heavily in scientific platforms, ranging from antibody-drug conjugates (ADCs) and cell therapies to RNA interference and precision oncology, ensuring that pipelines remain resilient against future market shifts.
Who truly rules?
Declaring a single "biggest" pharma company depends entirely on the lens of the observer:
Look at Stock Market Valuation, and Eli Lilly leads the pack.
Look at Total Corporate Revenue (Including Devices), and Johnson & Johnson takes the crown.
Look at Pure Prescription Drug and Vaccine Sales, and the race among Eli Lilly, Merck, Pfizer, AbbVie, and Roche remains a razor-thin contest that shifts with every quarterly earnings report.
As the industry races toward a projected multi-trillion-dollar global market over the next decade, innovation velocity will dictate which of these giants holds the crown tomorrow.