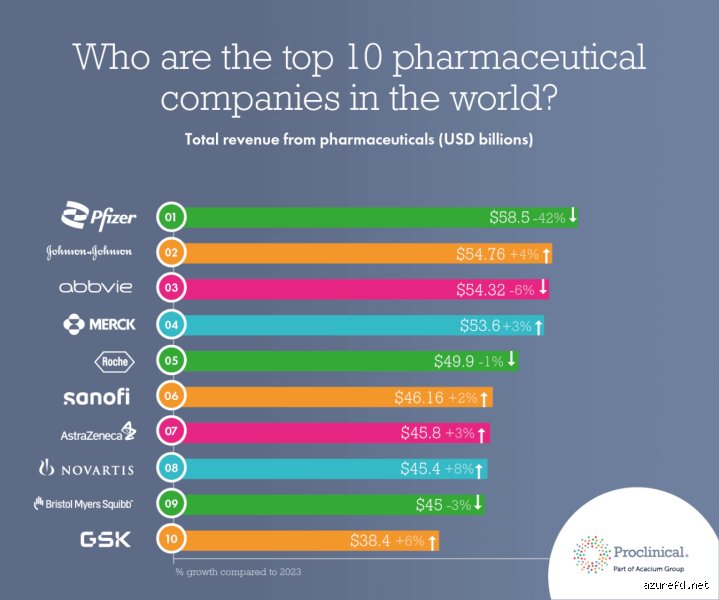
The titans of modern medicine
Understanding what constitutes the top tier of pharmaceutical powerhouses requires looking far beyond simple balance sheets. These multinational entities operate at the intersection of advanced molecular science, high-stakes global economics, complex regulatory frameworks, and geopolitical strategy. They hold the financial keys to curing rare genetic disorders, managing chronic global pandemics, and driving multi-billion-dollar mergers that can reshape the medical landscape overnight.
In this comprehensive first part of our expert analysis, we will deconstruct the concept of elite pharmaceutical dominance, examine how market leaders are categorized, and explore the foundational pillars that elevate certain corporations into the upper echelons of global healthcare.
Defining "Big Pharma" and the elite tier
The phrase "Big Pharma" is a broad umbrella term used to describe the world's largest publicly traded pharmaceutical corporations. These companies are characterized by massive global footprints, sprawling supply chains, multi-billion-dollar R&D budgets, and immense lobbying and market influence. However, within Big Pharma itself, a distinct hierarchy exists.
While dozens of major players inhabit the global top 20, a smaller vanguard—frequently tracked as the top tier or the leading cluster—captures a disproportionate share of global innovation, market value, and revenue. Because pharmaceutical portfolios change rapidly due to patent expirations (often called the "patent cliff"), regulatory hurdles, and blockbuster drug discoveries, the exact composition of the leading group is dynamic. Yet, companies like Eli Lilly, Pfizer, Johnson & Johnson, Merck & Co. (MSD), AbbVie, and Roche continually rotate through the absolute apex of the sector.
To properly evaluate these giants, industry experts typically break down their dominance using several core criteria:
Pure Pharmaceutical Revenue: Sales derived exclusively from therapeutic drugs and vaccines, stripping away consumer health, medical devices, or animal health divisions.
Blockbuster Portfolio Strength: The presence of flagship, multi-billion-dollar drugs that maintain market exclusivity and drive steady corporate expansion.
R&D Capital Investment: The sheer volume of financial capital funneled back into clinical trials, early-stage biotech acquisitions, and laboratory research.
Global Market Penetration: The logistical capability to distribute life-saving medications simultaneously across North America, Europe, Asia-Pacific, and emerging markets.
The core pillars driving elite Pharmaceutical status
What elevates a pharmaceutical company from a regional player to an undisputed global titan? The journey requires navigating a uniquely high-risk, high-reward business model. Unlike standard consumer goods companies, pharmaceutical innovators face an average development cycle of 10 to 15 years and an average cost exceeding two billion dollars per successfully commercialized drug.
1. The Blockbuster Drug phenomenon
The engine of any elite pharmaceutical company is the "blockbuster", a medication that generates over $1 billion in annual sales. Companies sitting at the top of the industry do not rely on a single blockbuster; they cultivate diversified portfolios of multiple mega-blockbusters. For instance, recent industry shifts have seen companies skyrocket up the revenue rankings purely on the back of revolutionary breakthroughs in metabolic disorders, immunology, and oncology. When a company successfully transitions from an aging blockbuster to a fresh generation of market-leading therapies, its elite status is cemented for another decade.
2. Aggressive mergers, acquisitions (M&A), and licensing
Internal research laboratories alone are rarely enough to sustain top-tier status. The elite giants operate sophisticated venture-capital-like apparatuses, constantly scanning the biotechnology landscape for promising early-stage assets. When a small biotech firm discovers a novel monoclonal antibody or gene-editing platform, top-tier pharmaceutical companies leverage their immense cash reserves to acquire the firm or license the technology. This constant cycle of external acquisition is vital for replacing revenue lost when older drugs lose their patent protection.
3. Navigating complex regulatory and Global Supply networks
Discovering a molecule in a laboratory is only half the battle. The elite pharmaceutical class possesses institutional expertise in dealing with stringent regulatory bodies such as the U.S. Food and Drug Administration (FDA) and the European Medicines Agency (EMA). Maintaining a global supply chain that can manufacture billions of sterile, temperature-sensitive doses under Good Manufacturing Practice (GMP) guidelines requires infrastructure that smaller competitors simply cannot replicate.
The modern shift: Therapeutic specialization and changing titans
The landscape of pharmaceutical leadership has undergone a dramatic evolution. Historically, companies that balanced consumer products, medical devices, and pharmaceuticals side-by-side held an advantage through diversification. Today, however, pure-play biopharmaceutical focus has become the gold standard.
Major structural realignments, such as massive corporate spin-offs separating consumer health divisions from core prescription drug operations, have allowed top companies to hyper-focus on high-margin, high-science therapeutic areas. Oncology (cancer therapies), immunology (autoimmune conditions), neuroscience, and metabolic diseases (such as advanced treatments for obesity and type 2 diabetes) have emerged as the primary battlegrounds where the elite fight for supremacy.
As we look deeper into the structural mechanics of these global healthcare giants, the lines between traditional small-molecule chemistry and advanced biological engineering continue to blur. The modern pharmaceutical leader must master cell therapies, RNA-based interventions, and artificial intelligence-driven drug discovery just to maintain its standing at the top.
This concludes the first part of our expert analysis on the upper echelons of the pharmaceutical industry. In Part 2, we will examine the specific balance sheets, pipeline strategies, and competitive advantages of the individual corporations currently leading global drug sales and innovation.
Navigating the future: Strategic horizons for industry leaders
The evolution of R&D and clinical development pipelines
As the pharmaceutical landscape moves past traditional chemical synthesis, the core engine driving the heavyweights of the industry has fundamentally shifted. Modern drug discovery is heavily anchored in complex biologics, gene therapies, precision oncology, and ribonucleic acid (RNA) interference platforms. To maintain their dominance, top-tier pharmaceutical entities no longer rely solely on internal laboratories. Instead, they function as master orchestrators of global scientific ecosystems, continually scanning biotech incubators, academic institutions, and startup hubs for breakthrough innovations.
This shift has drastically altered how clinical trials are designed and executed. Decentralized trials, real-world evidence (RWE) integration, and advanced biomarker-driven patient stratification have shortened development timelines for high-priority indications. However, navigating regulatory pathways remains fiercely competitive. Market leaders must balance aggressive pipeline expansion with rigorous risk management, ensuring that safety profiles match the high efficacy demanded by modern global health authorities.
Digital transformation, artificial intelligence, and Big data
The integration of artificial intelligence (AI) and machine learning (ML) into drug discovery has transitioned from an experimental novelty to a baseline operational requirement. The industry's leading players harness vast data lakes encompassing genomic sequencing, electronic health records, and high-throughput screening metrics to predict molecular behavior long before physical synthesis begins.
Target Identification: AI algorithms uncover hidden correlations in cellular pathways, identifying novel disease targets that human researchers might overlook.
Predictive Toxicology: Advanced computational models simulate toxicity and metabolic interactions, significantly reducing animal testing and early-stage clinical attrition rates.
Supply Chain Resilience: Predictive analytics optimize manufacturing footprints, safeguarding against global logistics disruptions and ensuring continuous distribution of life-saving therapeutics.
Beyond the laboratory, digital health tools, such as companion diagnostics, wearable remote-monitoring devices, and digital therapeutics, are increasingly bundled with traditional pharmacotherapy. This convergence of hardware, software, and molecular science creates closed-loop ecosystems that improve patient adherence and generate continuous longitudinal data.
Patent cliffs, generic pressures, and strategic M&A
One of the most defining realities for pharmaceutical titans is the perpetual shadow of the "patent cliff." When exclusivity periods for blockbuster drugs expire, generic manufacturers and biosimilar competitors rapidly erode revenue streams. To counteract these inevitable cliffs, industry leaders rely heavily on aggressive mergers and acquisitions (M&A) strategies, corporate venture capital, and licensing agreements.
Acquiring mid-sized biotechnology firms with de-risked Phase II or Phase III pipeline assets allows industry powerhouses to instantly replenish revenue pipelines. Simultaneously, portfolio pruning has become common practice. Corporations routinely divest non-core divisions, such as consumer health or animal health, to refocus capital entirely on high-margin, high-innovation specialty care areas like oncology, immunology, and rare genetic disorders.
Global Market access, pricing pressures, and sustainability
Sustaining commercial leadership requires navigating an increasingly complex web of global market access hurdles, pricing regulations, and geopolitical tensions. Payers across both public and private sectors are implementing strict value-based pricing models, requiring manufacturers to prove not just clinical efficacy, but long-term cost-effectiveness over traditional standards of care.
Simultaneously, environmental, social, and governance (ESG) metrics have taken center stage. Stakeholders, ranging from institutional investors to patient advocacy groups, demand transparent supply chains, aggressive carbon-reduction targets, and equitable global health initiatives that ensure low- and middle-income countries have sustainable access to essential medicines.
Maintaining a position at the pinnacle of the pharmaceutical sector requires an agile equilibrium: balancing relentless scientific daring with rigorous fiscal discipline, digital modernization, and an unwavering commitment to global patient outcomes.