The Prestige paradox: Dissecting the mythos of the Big Four accounting and professional Services giants
The Allure of the Shield
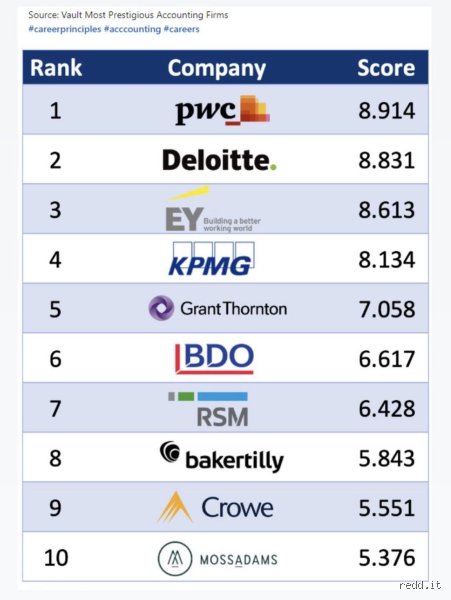
Yet, despite their shared oligopolistic dominance over the global professional services landscape, a persistent, intensely debated question haunts watercoolers, university career centers, and executive boardrooms across the globe: Which Big 4 firm is most prestigious?
The answer is deceptively complex. Unlike investment banking—where firm-specific prestige hierarchies (such as the traditional "Bulge Bracket" ranking of Goldman Sachs, Morgan Stanley, and JPMorgan) are entrenched and widely accepted—the Big Four occupy a fuzzier, more multi-dimensional continuum. Prestige in this context is not a monolithic score; it is a fragmented mosaic shaped by geography, service line, historical legacy, cultural mythology, and individual career ambitions. A firm hailed as the undisputed king of prestige in London’s financial district might play second fiddle in a regional U.S. market, just as a titan in global management consulting advisory might face fierce competition from a powerhouse known for elite tax and audit execution.
To truly understand which firm wears the crown, we must dissect the anatomy of Big Four prestige. We must move beyond superficial brand recognition and examine the structural pillars that build these reputations: market share, revenue generation, historical lineage, service-line dominance (Audit, Tax, and Advisory/Consulting), and the elusive, highly subjective realm of cultural perception.
The historical genesis: From local partnerships to Global oligopoly
To evaluate contemporary prestige, one must first trace the evolutionary roots of the Big Four. Modern professional services are the product of a century-long wave of mergers, regulatory shifts, and the relentless globalization of capital markets. Understanding where these firms came from explains why their brand identities differ so sharply today.
Throughout the 20th century, the accounting landscape was governed first by the "Big Eight," which gradually consolidated into the "Big Six" through a series of mega-mergers in the late 1980s and 1990s (including the creation of PricewaterhouseCoopers in 1998 and EY via the merger of Ernst & Whinney and Arthur Young). The defining shockwave arrived in 2001 with the collapse of Enron and the subsequent implosion of Arthur Andersen, then one of the Big Five.
The fall of Arthur Andersen was a watershed moment that permanently reshaped the psychology of prestige in the industry. Overnight, an elite institution synonymous with gold-standard auditing vanished due to ethical failures. The remaining firms absorbed Andersen’s talent and client rosters, crystallizing into the current Big Four. This historical trauma instilled a deep-seated institutional obsession with risk management, regulatory compliance, and brand protection that underpins the culture of every firm today.
However, each firm retained a distinct DNA derived from its heritage:
Deloitte (historically rooted in Haskins & Sells and Touche Ross) leaned heavily into management consulting and operational advisory early on, cultivating an aggressive, growth-oriented culture.
PwC (tracing its lineage through Price Waterhouse and Coopers & Lybrand) established an early reputation as the quintessential "blue-chip" auditor of the British establishment and Wall Street banking giants.
EY (built on Ernst & Young) forged a strong identity in entrepreneurial advisory, tax services, and a notoriously client-centric, relationship-driven culture.
KPMG (formed from Peat Marwick Mitchell and Klynveld Main Goerdeler) cemented its reputation as a powerhouse in middle-market assurance, tax, and a deeply analytical, methodical approach to professional services.
This historical divergence means that when industry insiders debate prestige today, they are often unconsciously projecting these historical strengths onto current market realities.
Quantitative metrics: Revenue, scale, and market share
While prestige is often discussed in abstract, qualitative terms, such as brand cachet or exclusivity, it is fundamentally anchored to raw economic gravity. In the corporate world, size matters. The ability to deploy tens of thousands of professionals across continents, secure multi-million-dollar retainers from multinational conglomerates, and absorb macroeconomic shocks directly feeds a firm’s market perception.
To evaluate the current standing of the Big Four through a quantitative lens, we examine their global aggregate revenues and market footprints:
| Firm | Approximate Global Revenue (Recent Fiscal Years) | Global Headcount | Primary Global Footprint Strengths |
|---|---|---|---|
| Deloitte | ~$65 Billion+ | ~450,000+ | North America, Global Consulting, Public Sector Advisory |
| PwC | ~$55 Billion+ | ~360,000+ | EMEA, Financial Services Audit, Deal Advisory |
| EY | ~$50 Billion+ | ~395,000+ | Tax, Emerging Markets, Transaction Advisory |
| KPMG | ~$35 Billion+ | ~270,000+ | Middle-Market Assurance, Tax, European Footprint |
Looking strictly at top-line revenue, Deloitte consistently claims the throne as the largest professional services network in the world. This massive financial scale affords Deloitte unmatched budgetary muscle to invest in emerging technologies, artificial intelligence integration, and aggressive lateral hiring. In the eyes of corporate executives looking for a one-stop-shop vendor capable of handling enterprise-wide digital transformations alongside statutory audits, Deloitte’s sheer size translates directly into institutional confidence and market prestige.
PwC, however, closely rivals, and in many key financial hubs, surpasses, Deloitte in the sheer prestige of its client roster within the banking, insurance, and asset management sectors. If prestige is measured by the percentage of FTSE 100 or Fortune 500 audit mandates held, PwC frequently commands a dominant share. For an auditor, auditing commercial banking titans like JPMorgan Chase or multinational giants like Unilever carries an elite cachet that money cannot easily buy.
The Service-Line schism: Audit vs. Tax vs. Consulting
One of the greatest fallacies in discussions of Big Four prestige is treating each firm as a homogenous entity. In reality, a firm’s prestige varies wildly depending on the specific service line being evaluated. A candidate or client looking at Audit & Assurance experiences a completely different brand hierarchy than someone looking at Tax Services or Management/Strategy Consulting (such as Deloitte's Monitor Deloitte or PwC's Strategy&).
1. Audit and Assurance: The traditional pillar
Audit is the foundational bedrock of the Big Four. Historically, it is the most regulated, standardized, and traditional service line.
The Perception: Audit is often viewed by external observers as the ultimate badge of rigorous accounting discipline, but within elite student circles, it is sometimes stereotyped as traditional, compliance-driven, and lower-margin.
The Prestige Leader: PwC traditionally holds a slight psychological edge in global audit prestige, particularly in Western Europe and the United States financial markets, owing to its deep historical dominance in auditing major financial institutions. Close behind is Deloitte, which commands massive audit market share across diverse industrial sectors.
2. Tax Services: The complex engine
Tax advisory and compliance represent a massive, highly lucrative revenue engine for all four firms, involving intricate international tax planning, transfer pricing, and M&A tax structuring.
The Perception: Tax professionals require deep, specialized legal and quantitative knowledge. It is fiercely intellectual work that offers phenomenal exit opportunities into corporate tax departments, Big Law, and private equity.
The Prestige Leader: EY has historically carved out a reputation as a powerhouse in tax services, frequently winning industry awards and ranking exceptionally high among tax professionals for its structured career progression and specialized training programs. However, Deloitte and PwC match EY dollar-for-dollar in major tax advisory mandates.
3. Advisory, Consulting, and Strategy: The modern battleground
The most dramatic shifts in prestige over the past two decades have occurred in the consulting and advisory domains. Following the post-Enron regulatory separation of auditing and consulting (culminating in the Sarbanes-Oxley Act of 2002), the Big Four spent two decades aggressively rebuilding their consulting practices through organic growth and multi-billion-dollar acquisitions.
The Prestige Factor: The acquisition of boutique strategy firms, most notably PwC’s acquisition of Booz & Company (rebranded as Strategy&) and Deloitte’s integration of Monitor Group, fundamentally altered the competitive landscape. These moves allowed Big Four consulting arms to compete directly with elite traditional strategy houses like McKinsey & Company, Boston Consulting Group (BCG), and Bain & Company (collectively known as MBB).
The Prestige Leader: in consulting and advisory prestige, Deloitte stands out as the undisputed heavyweight champion among the Big Four. Deloitte Consulting is a massive enterprise that operates on a scale approaching traditional strategy firms in certain sectors, offering clients an end-to-end continuum from high-level digital strategy down to complex systems implementation (e.g., SAP, Salesforce, and enterprise cloud architecture). Meanwhile, Strategy& carries immense cachet for candidates seeking pure-play strategy consulting within a Big Four umbrella, bridging the gap between traditional management consulting and accounting firm stability.
(This concludes the first part of the analysis on Big Four prestige. The subsequent part will explore geographical variations, institutional culture, campus recruiting dynamics, exit opportunities, and the final verdict on which firm ultimately holds the crown.)
Evaluating market standing across the global professional services networks requires examining distinct operational pillars. Each organization maintains separate strongholds built over decades of regulatory work, corporate advisory engagements, and large-scale enterprise transformations. Regional dominance often dictates how external observers measure market value, shifting the perception of leadership between North American markets, European capitals, and fast-growing economies across the Asia-Pacific region.
Financial metrics frequently serve as a primary yardstick for institutional scale. Aggregate fee income highlights the sheer footprint of these enterprises, yet gross revenue tells only part of the story regarding brand cachet. The composition of service lines, ranging from statutory audit to specialized management consulting and tax advisory, shapes how corporate clients and university graduates perceive the elite tier of professional services. Leadership positions in specific sectors create distinct reputational advantages that persist across competitive recruitment cycles.
Audit operations remain the foundational anchor for the entire sector. Statutory requirements compel publicly traded corporations to retain external auditors, cementing a baseline of stability and continuous corporate interaction. Market share within the Fortune Global 500 heavily influences overall brand gravity. When an organization audits a high concentration of the world's largest enterprises, its institutional authority expands proportionally. This deep integration into core financial reporting processes creates a resilient barrier against market volatility, reinforcing long-term enterprise value.
Advisory and management consulting divisions operate under entirely different competitive dynamics. Strategy consulting practices, risk advisory teams, and digital transformation units compete directly with specialized boutique firms and elite management consultancies. Organizations that successfully integrated high-end strategy houses benefit from a distinct halo effect. This operational blending elevates their perceived sophistication among corporate boards and MBA graduates seeking complex advisory assignments rather than routine compliance tasks.
Recruitment pipelines and university branding reinforce these internal hierarchies year after year. Target school strategies ensure a steady influx of top-tier talent into advisory and financial auditing tracks. Alumni networks span leadership roles throughout private equity, corporate finance, and executive management. The strength of these professional diaspora networks acts as a self-fulfilling prophecy for institutional standing. Professionals exiting into industry carry the brand reputation forward, influencing future hiring decisions and corporate procurement strategies.
Geographic nuances further complicate any universal hierarchy. An organization viewed as the undisputed market leader in one jurisdiction may occupy a secondary position in another major financial hub. European regulatory frameworks emphasize different professional credentials compared to North American or Asian markets. Consequently, local leadership teams cultivate specialized areas of expertise to capture regional market share, leading to decentralized prestige rather than a single global consensus.
Public perception converges around a closely contested group where absolute dominance remains elusive. While survey data and market rankings regularly place specific networks at the forefront based on distinct criteria, the narrow margins separating the top contenders reflect intense competition across every major service line. Client preference typically depends on the specific nature of the engagement, whether it demands rigorous regulatory compliance or innovative digital strategy.