Zonal valuation serves as the financial baseline for government taxation and property assessment. However, land is not a monolith; a square meter of soil in a bustling central business district commands an entirely different valuation than the same area in an agricultural province or an industrial estate. To accurately navigate property taxes, capital gains, estate planning, and acquisitions, one must first understand the intricate taxonomy of land classifications that dictate these values.
1. The anatomy of Zonal Valuation: What it is and why it matters
Before diving into classifications, it is essential to establish a clear conceptual foundation of what zonal value actually represents.
Defining Zonal Value
Zonal value refers to the pre-determined valuation of real property, specifically land and, by extension, improvements, set by tax authorities (such as the Bureau of Internal Revenue in various jurisdictions) for each zone or street within a municipality or city. It represents the minimum benchmark price per square meter used to compute national and local internal revenue taxes.
Zonal Value vs. Fair Market Value vs. Assessed Value
It is common for property owners to confuse these three distinct financial metrics:
Fair Market Value (FMV): The price that a willing buyer would pay a willing seller in an open market transaction under normal conditions. FMV fluctuates dynamically based on supply, demand, economic trends, and localized development.
Zonal Value: A statutory baseline established by government agencies through periodic market studies. It is typically updated every few years to reflect general economic shifts, though it often lags behind real-time market fluctuations.
Assessed Value: The value of the property derived by multiplying the Fair Market Value or Zonal Value (whichever is higher, depending on local tax codes) by an assessment level percentage set by local government units (LGUs) for real property tax (RPT) purposes.
Tax authorities generally mandate that any transaction involving real property cannot be taxed at a value lower than the established zonal value or the selling price, whichever is higher. Consequently, understanding how your property is classified directly dictates your tax liabilities during a sale, donation, or inheritance.
2. The master framework: Primary land classifications
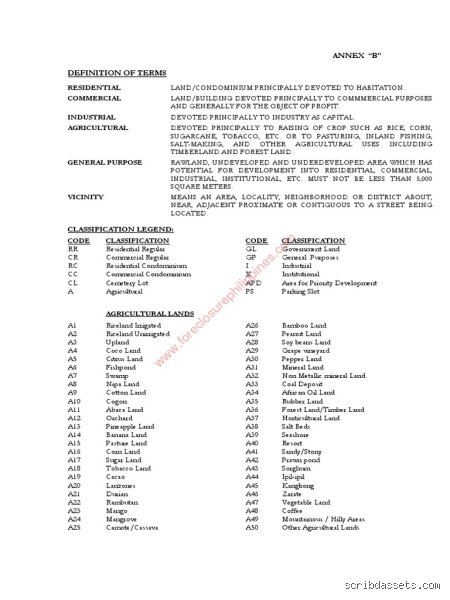
Government tax bureaus and municipal assessors categorize land based on its designated use, zoning ordinances, actual utilization, and potential economic output. While specific terminologies vary slightly across global jurisdictions, standard real estate tax frameworks generally partition land into several primary classifications:
RR (Residential): Lands primarily used or zoned for dwelling purposes.
CR (Commercial): Lands utilized for business, trade, and commercial enterprises.
I (Industrial): Lands dedicated to manufacturing, warehousing, heavy processing, and assembly.
A (Agricultural): Lands devoted to agricultural production, farming, horticulture, and livestock.
X (Institutional / Special): Lands used for schools, hospitals, government offices, religious institutions, and public utilities.
GP / Misc (General Purpose / Miscellaneous): Unclassified or raw lands awaiting development, or specialized tracts requiring individual appraisal.
Each of these primary categories is further broken down into sub-classifications that account for infrastructure access, proximity to commercial centers, density, and permitted structural development.
3. Deep dive into Residential land classifications
Residential land typically commands the largest volume of real estate transactions within urban and suburban areas. However, not all residential land is valued equally. Tax assessors utilize granular sub-classifications to differentiate between various types of residential developments.
A. Regular Residential (RR)
Regular residential zones cover standard subdivisions, neighborhoods, and individual parcels designated for single-family or low-density multi-family housing.
Valuation Factors: The zonal value of an RR parcel is heavily influenced by road network quality (e.g., paved concrete vs. gravel roads), distance to major thoroughfares, availability of utilities (water, electricity, high-speed fiber internet), and flood history.
Sub-Tiers: In many municipal schedules, RR properties are further stratified into:
Class A: Premium gated subdivisions and exclusive enclaves with high-end amenities.
Class B: Standard middle-class subdivisions and established residential barangays.
Class C / Depressed Areas: Low-income or informal settlement areas with limited infrastructure access.
B. Condominium units and townhouses (CR / condominiums)
With urban land becoming increasingly scarce, vertical living and high-density horizontal developments have reshaped zonal valuation tables.
The Undivided Interest Principle: For condominium developments, the zonal value is applied to the unit's share of the total land area (computed via the floor area ratio or condominium certificate of title ratio) combined with the floor area of the unit itself.
Townhouses: Unlike standard subdivision lots, townhouses share common walls and a fractional interest in the master lot. Zonal values account for both the footprint and the shared common areas (driveways, security gates).
C. Socialized housing (SH)
Recognized by governments to promote affordable housing access for low-income citizens, socialized housing projects enjoy preferential, significantly lower zonal values and tax exemptions or reductions under specific national housing laws. These zones are strictly monitored to ensure developers allocate a mandatory percentage of their portfolio to affordable housing units.
4. Deep dive into Commercial land classifications
Commercial land classifications represent properties where economic activity, commerce, and retail trade take place. Because commercial real estate generates higher revenue streams, rental yields, and business turnover compared to residential parcels, commercial zonal values are invariably higher, often multiplying residential values by a factor of two to ten within the same geographic corridor.
A. Central Business Districts (CBDs) and prime Commercial strips
The highest zonal values in any municipality are almost universally found in recognized Central Business Districts (e.g., major financial centers, prime retail districts, and metropolitan core corridors).
Foot Traffic and Accessibility: Zonal valuation boards analyze pedestrian foot traffic, proximity to mass transit systems (such as subway or light rail stations), highway interchanges, and corporate density.
Multi-Frontage Premiums: A commercial plot situated on a corner lot (having two or more street frontages) or facing a primary multi-lane avenue is often assigned an escalated zonal value multiplier because of superior visibility and access for retail customers and logistics.
B. Secondary and neighborhood Commercial zones
Outside the primary CBDs lie secondary commercial corridors, strip malls, and neighborhood commercial pockets. These areas cater to local retail demands, community services, small businesses, and localized office spaces. While their zonal values are lower than core CBDs, they still command a substantial premium over adjacent residential zones due to their commercial zoning license.
C. Mixed-Use and Special Commercial zones
Modern urban planning heavily favors mixed-use developments (live-work-play environments) where residential towers sit atop retail podiums and office spaces. Tax authorities handle mixed-use properties through composite valuation techniques, applying commercial zonal values to the ground-floor retail footprints and lower commercial tiers, while applying residential or office zonal rates to the upper vertical structures.
This concludes Part 1 of our guide on land classifications and zonal values. In Part 2, we will examine Industrial, Agricultural, and Institutional land classifications, explore how government assessors calculate periodic adjustments, and provide a strategic analysis of how zonal values impact property acquisition and tax planning.
Algorithmic Valuation models and Bureaucratic adjustments
Moving beyond basic statutory definitions, the actual computation of zonal values relies on sophisticated municipal algorithms and macroeconomic indicators. Tax authorities rarely rely on static figures; instead, they implement automated valuation models (AVMs) that ingest GIS (Geographic Information Systems) mapping data, historical registry transfers, and commercial density indices.
The primary metric driving these models is the comparable sales approach adjusted for statutory uniformity. When tax assessors evaluate a specific classification, such as Commercial-1 (C-1) versus Residential-Regular (RR), they aggregate recent notarized deeds of sale within a designated micro-market. However, because raw transaction prices frequently suffer from under-reporting or tax evasion, algorithms apply a correction factor based on regional inflation rates, infrastructure proximity scores, and zoning changes.
+------------------------------------------------------------+
| Zonal Value Computation Flow |
+------------------------------------------------------------+
| 1. GIS Mapping & Spatial Data Ingestion |
| 2. Historical Registry Transfers & Deed Analysis |
| 3. Application of Commercial Density & Inflation Factors |
| 4. Statutory Uniformity & Bureaucratic Review |
+------------------------------------------------------------+
Bureaucratic adjustments also account for structural shifts in municipal planning. For instance, if a municipality reclassifies a former agricultural belt into a mixed-use commercial hub, the zonal valuation framework triggers an immediate re-evaluation phase. This phase uses a gradient decay function, where properties situated closer to central transit hubs experience exponential zonal value appreciation, while peripheral parcels within the same classification tier see linear, muted adjustments. Understanding this algorithmic foundation allows property developers to anticipate tax revisions years before official government publication schedules.
Little-Known aspect: Overlooked encumbrances, Right-of-Way Servitudes, and Zonal discounting
While standard classifications dictate the baseline tax per square meter, property owners frequently miss legal mechanisms that mandate zonal discounting. Statutory frameworks often treat land classifications as uniform across an entire street or barangay, yet physical and legal encumbrances drastically alter the true economic utility of a parcel.
Easements and Servitudes: Parcels encumbered by legal easements, such as mandatory riverbank setbacks, electrical transmission right-of-ways, or public utility access roads, suffer a permanent reduction in usable footprint. Savvy tax practitioners can petition for an adjusted zonal valuation by demonstrating that a significant percentage of the classified land cannot support vertical or horizontal development.
Environmental and Heritage Overlays: Land classified as commercial or residential may fall under strict environmental protection laws or historical preservation mandates. These overlays restrict demolition, height limits, and material usage, effectively stripping the property of its highest and best use potential.
Topographical and Geotechnical Anomal