Will finance get replaced by AI? An architecture of transformation (part I)
To understand the trajectory of this transformation, we must dismantle the myth of total substitution and examine how automation, machine learning agents, and generative systems are actively rewriting the boundaries of corporate finance, investment banking, asset management, and regulatory compliance.
1. The anatomy of Exposure: Tasks versus jobs
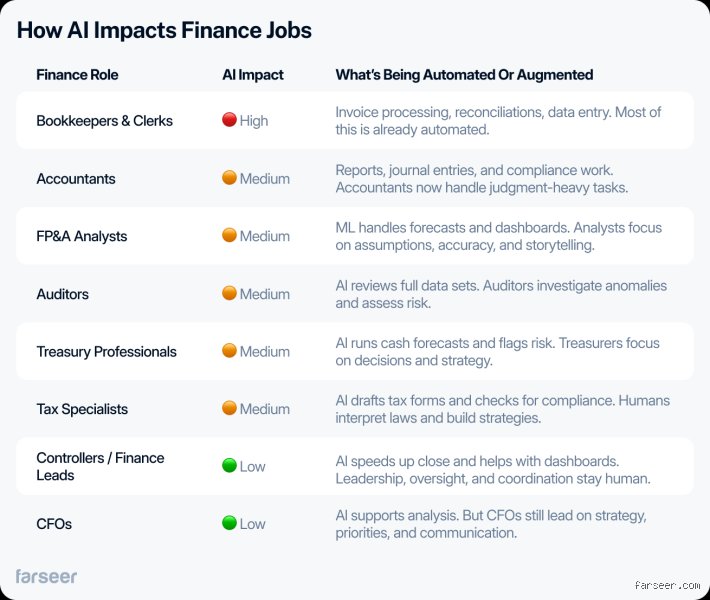
A foundational error in popular discourse is the conflation of task automation with job elimination. When labor market analyses indicate that over half of banking and financial operations possess high automation potential, headlines routinely translate this to mean that half of all bankers, accountants, and analysts will receive pink slips.
In practice, financial roles are bundles of discrete responsibilities. A corporate financial analyst does not spend forty hours a week executing a single monolithic function. Instead, their week is a patchwork of data ingestion, spreadsheet reconciliation, variance analysis, cross-functional meetings, slide deck generation, strategic synthesis, and executive counseling.
High-Exposure Tasks: Information gathering, initial data cleansing, repetitive transactional bookkeeping, first-pass financial modeling, compliance document checks, and routine reporting are highly susceptible to algorithmic execution. Large language models and specialized financial neural networks can process these workflows with near-zero marginal cost and unprecedented speed.
Low-Exposure Domains: Relationship management, nuanced risk judgment, structural negotiation, ethical accountability, complex stakeholder alignment, and strategic capital allocation remain intensely human-centric.
Consequently, the primary friction point in modern finance is not that entire job categories are vanishing overnight, but that the internal composition of those jobs is mutating radically.
2. The great compression: From Month-End closes to continuous intelligence
For decades, the rhythm of corporate finance has been dictated by the calendar. The month-end close, quarterly earnings preparations, and annual budget cycles have consumed thousands of human hours in mechanical verification, error checking, and ledger reconciliation.
AI-driven enterprise resource planning (ERP) systems and autonomous finance agents are compressing these traditional workflows into continuous intelligence. Rather than waiting for a month-end hard stop to discover structural anomalies, real-time data pipelines coupled with anomaly-detection algorithms flag irregularities as they occur.
Variance Analysis at Scale: Explaining why a business unit missed its margin target traditionally required junior analysts to pull disparate logs, build pivot tables, and draft explanatory memos. AI agents now synthesize these variance reports instantly, linking operational telemetry directly to financial statements.
The Erosion of Friction: As routine data preparation approaches absolute automation, finance departments are shifting from backward-looking scorekeepers to real-time strategic advisors. However, this shift creates a secondary organizational crisis: if machines handle the foundational tasks that junior analysts historically used to build institutional competence, how do firms cultivate senior judgment?
3. Algorithm aversion and the trust deficit in capital markets
Despite the technical capability of modern AI systems to ingest and project complex financial data, institutional adoption faces a formidable psychological and governance barrier: algorithm aversion and the imperative of auditability.
Financial institutions operate under strict regulatory umbrellas where every material decision must be justifiable to boards, auditors, and state regulators. Empirical surveys of senior financial decision-makers reveal a striking consensus: absolute predictive accuracy alone is insufficient. Over 70% of finance leaders report that they would reject an AI tool boasting extreme accuracy if the model functions as a "black box" and cannot explicitly explain its computational pathway.
The Explainability Imperative: In credit scoring, anti-money laundering (AML), and high-stakes portfolio management, regulatory frameworks (such as the EU AI Act and global banking standards) mandate algorithmic transparency. If an AI agent denies a multi-million-dollar credit facility or reallocates systemic capital reserves, the institution must be able to articulate the exact causal chain.
The Risk of Hallucination: While creative writing tolerances permit occasional factual drift, financial accounting tolerates a zero-error margin. Generative hallucinations in ledger entries or tax calculations present existential legal risks, ensuring that human-in-the-loop validation remains mandatory for mission-critical workflows.
4. Redefining the competitive moat in banking and investment
Historically, traditional banking and asset management institutions maintained competitive moats through physical branch networks, proprietary data silos, high customer switching friction, and entrenched brand loyalty. Customers stayed with legacy institutions largely due to the administrative burden of moving accounts, processing recurring bills, and untangling complex credit relationships.
AI agents are systematically eroding these protective moats.
Frictionless Switching: Intelligent consumer agents can continuously monitor deposit yields, loan interest rates, and fee structures across the entire financial ecosystem, automatically repositioning liquid capital to maximize returns. When finding and executing a better financial product becomes frictionless, institutional inertia ceases to guarantee customer retention.
Democratized Sophistication: Sophisticated quantitative screening, bespoke portfolio hedging, and personalized wealth advisory—once luxury services reserved for institutional players or ultra-high-net-worth individuals—are being automated and scaled down to retail investors via algorithmic interfaces.
As efficiency gains become table stakes across the industry, financial firms cannot rely on cost-reduction alone to generate sustainable shareholder value. The true winners of the AI transition will be those institutions that successfully redirect computational efficiencies into hyper-personalized financial engineering, ironclad risk governance, and trusted advisory relationships.
(This concludes the first part of our exploration into the restructuring of finance under artificial intelligence. The subsequent part will examine granular shifts in asset management, quantitative trading algorithms, and the evolution of regulatory tech.)
The human catalyst: Orchestrating the AI transition
As routine transactional tasks, data consolidation, and preliminary financial modeling migrate seamlessly to autonomous agents and machine learning pipelines, the core architecture of the finance profession is undergoing a profound transformation. Rather than an outright replacement of human capital, the integration of artificial intelligence represents a shift from mechanical execution to high-value strategic orchestration.
This evolution redefines the daily reality for Chief Financial Officers (CFOs), financial analysts, and corporate accountants alike. The value proposition of a finance professional is no longer measured by how rapidly they can compile a variance report or reconcile a general ledger, but by how effectively they can interpret machine-generated insights, challenge algorithmic assumptions, and translate complex data streams into actionable corporate strategy.
Redefining the apprenticeship Model
One of the most pressing structural challenges facing modern finance departments is the disruption of the traditional career ladder. Historically, junior analysts and entry-level accountants spent their formative years immersed in repetitive data entry, transaction matching, and first-pass spreadsheet creation. Through these foundational chores, they gradually absorbed the mechanics of the business cycle.
With generative and agentic AI systems now executing these baseline duties in seconds, drastically shortening month-end closes and automating routine tax research, organizations face an urgent imperative: how to build deep institutional expertise when the entry-level tasks have been automated away.
To prevent a talent drain and avoid a future shortage of strategic leaders, forward-thinking enterprises are actively redesigning their professional development pathways:
Accelerated Exposure: New hires are introduced to multi-disciplinary problem-solving, cross-functional auditing, and operational consulting much earlier in their tenure.
AI Literacy as Core Competency: Proficiency in prompting, model validation, and identifying algorithmic hallucinations is taught alongside traditional corporate finance principles.
Mastery of Context: Professionals are trained to focus on data quality, semantic governance, and contextual nuance, areas where human judgment remains fundamentally irreplaceable.
The new pillars of competitive advantage
As AI democratizes speed and analytical horsepower, technical proficiency alone ceases to be a unique market differentiator. Instead, competitive advantage in corporate finance pivots on three distinct human-centric pillars:
Rigor in Model Governance and Validation: Because AI models are probabilistic rather than infallible, finance leaders must implement rigorous oversight frameworks. Knowing when to trust an algorithm and how to stress-test its underlying assumptions protects organizations from systemic risk and compliance failures.
Contextual Storytelling and Translation: Numbers generated by predictive models are inert without narrative context. The modern finance expert acts as a bridge between cold computational output and executive decision-making, framing financial metrics within broader market dynamics, ethical considerations, and human behaviors.
Accountability and Ethics: Machines can simulate thousands of macroeconomic scenarios and optimize capital allocation parameters, but they cannot legally, morally, or organizationally own a decision. Ultimate accountability remains a human burden, cementing the role of finance leaders as stewards of corporate integrity.
Augmentation over Elimination
Finance will not be replaced by artificial intelligence; rather, finance professionals who leverage AI will replace those who do not. The ongoing transition is less an apocalypse than an elevation, a purging of tedious administrative overhead in exchange for expanded cognitive bandwidth. By embracing machine efficiency while doubling down on uniquely human traits like critical thinking, empathy, and strategic intuition, the financial sector is poised to drive unprecedented levels of growth and innovation through the remainder of the decade and beyond.