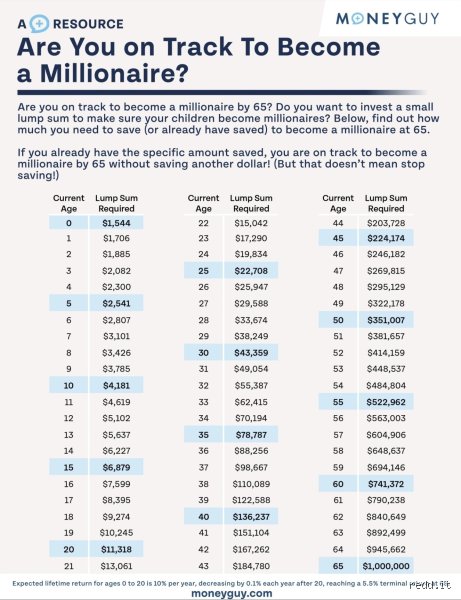
For generations, the figure of $1,000,000 has served as the ultimate financial North Star. It is the mythical summit of the personal finance journey—the iconic benchmark featured in novels, movies, retirement brochures, and cultural milestones. Hitting a net worth of one million dollars is traditionally viewed as the gateway to absolute freedom, early retirement, and effortless security.
Yet, as we navigate through an evolving economic landscape marked by shifting monetary policies, post-pandemic adjustments, and persistent inflation, a critical question arises: What will that exact same million dollars actually buy you two decades from now?
The short, sobering truth is that a dollar is a moving target, not a fixed anchor. When evaluated through the lens of a 20-year time horizon, the purchasing power of $1,000,000 undergoes a radical transformation. Without strategic deployment, growth, and structural protection, the seven-figure nest egg of today risks becoming the middle-class security blanket of tomorrow.
In this first part of our comprehensive expert analysis, we will deconstruct the mechanics of purchasing power degradation, explore historical and projected inflation models, and examine why viewing $1 million as a static lump sum is one of the most dangerous blind spots in modern financial planning.
1. The Psychology Versus the Reality of the Million-Dollar Milestone
To understand the future value of $1 million, we must first address the psychological weight the number carries. Human brains are prone to nominal anchoring—the cognitive bias where we fixate on the face value of money rather than its real economic utility.
When television shows or financial gurus from the late 20th century popularized the "million-dollar retirement goal," the economic ecosystem was radically different. A million dollars in 1985 or 1995 commanded an entirely different level of lifestyle provisioning than it does today. Housing markets, healthcare expenses, higher education tuition, and basic consumer goods have outpaced general consumer price index (CPI) measures by substantial margins.
Consequently, treating $1,000,000 as a universal finish line is an exercise in financial illusion. If you lock $1,000,000 away in a vault or a low-yield cash vehicle today, you are not preserving a lifestyle; you are passively participating in the systematic erosion of your future options.
To evaluate what your wealth will look like in 20 years, we must separate cash as a store of value from capital as an engine of productivity.
2. The Silent Thief: Demystifying Long-Term Inflation
At the heart of the 20-year depreciation problem is inflation. Often described as a silent tax, inflation represents the gradual increase in the prices of goods and services across an economy, which concurrently causes a decline in the purchasing power of a single unit of currency.
Over the long term, central banks typically target an annualized inflation rate of around 2.0%. However, historical realities often outpace targets. Over extended multi-decade periods, U.S. consumer price inflation has frequently averaged closer to 2.5% to 3.0% annually, with cyclical spikes occurring during global supply chain disruptions, energy crises, and major macroeconomic shifts.
Even under a conservative, steady-state assumption, the compounding mathematics of inflation are unforgiving. To visualize how purchasing power decays over a 20-year timeline, consider the following compounding inflation model formula:
Let's break down how different average annual inflation rates erode a static $1,000,000 cash balance over a 20-year window:
As this breakdown demonstrates, even at a relatively benign 2.5% average inflation rate, your million dollars will lose nearly 40% of its purchasing power in 20 years. In practical terms, what costs $1,000,000 today will require roughly $1,641,000 twenty years from now just to maintain the exact same standard of living. If inflation averages 3.0%, that same basket of goods will cost over $1,806,000.
3. Sector-Specific Inflation: Why Averages Can Be Deceiving
Relying solely on headline CPI figures can give investors a false sense of security. General inflation measures track a broad, homogenized basket of goods—everything from televisions and used cars to apparel and airline tickets. However, wealth preservation is rarely threatened by the rising cost of electronics; it is challenged by non-discretionary, high-velocity asset inflation in sectors essential for long-term survival and lifestyle stability:
Healthcare and Medical Costs: Historically, medical inflation outpaces general consumer inflation significantly. Long-term care, insurance premiums, pharmaceuticals, and out-of-pocket medical expenses compound at rates often exceeding 4% to 5% annually. For someone looking 20 years into the future, healthcare will consume a vastly larger percentage of net worth than it does today.
Higher Education: While college tuition inflation has experienced various regulatory and market pressures recently, its multi-decade trajectory has consistently outstripped standard wage and price growth.
Real Estate and Housing: Prime residential real estate in major metropolitan hubs or resilient suburban markets behaves as both a consumption good and an investment class. Supply constraints and zoning laws often push housing appreciation well above baseline inflation metrics.
When you factor in these sector-specific pressures, a static $1 million stash faces an even steeper uphill battle. The cost of living a comfortable, independent lifestyle in your later years will experience heavier upward pressure than standard macroeconomic indexes suggest.
4. The Opportunity Cost of Holding Cash
The most significant risk associated with projecting a $1 million net worth over 20 years is not just inflation itself—it is the opportunity cost of passive asset management.
If an individual accumulates $1,000,000 and leaves it sitting in low-yield savings accounts or static cash equivalents, they are fighting a two-front war:
Purchasing Power Erosion: Losing 2% to 3% of real value every single year to inflation.
Missed Compounding Growth: Forgoing the historical returns generated by productive asset classes like equities, commercial real estate, or business enterprises.
To put this in perspective, consider the alternative framework: capital deployed into diversified growth assets does not merely sit there; it works. While cash loses value over time, productive assets historically grow to outpace inflation, capturing corporate earnings growth, dividends, and real economic output.
Looking Ahead: Bridging the Gap in Part 2
We have established that a static $1,000,000 cash balance is a shrinking target over a 20-year horizon, heavily undermined by compounding inflation and structural cost increases in healthcare and housing.
However, recognizing these challenges is only the first step. The critical takeaway is not that $1 million is doomed to fail, but rather that how that wealth is structured, invested, and defended dictates its ultimate real-world worth.
In Part 2 of this expert analysis, we will transition from diagnostic modeling to strategic execution. We will explore:
How to construct a forward-looking wealth preservation framework that neutralizes 20-year inflation risks.
The role of asset allocation, tax efficiency, and cash-flow management in safeguarding long-term purchasing power.
Actionable financial modeling steps to calculate your personal target number, ensuring that your future million dollars retains its true economic power.
What steps are you currently taking to insulate your long-term savings from the invisible erosion of inflation over the next two decades?
The Growth Equation: Putting Your $1 Million to Work
While inflation acts as a silent tax on cash sitting idly in a checking account, investing transforms that same $1 million into an engine of compounding wealth. The value of $1 million in 20 years is not fixed by inflation alone; it is dictated entirely by where and how that capital is deployed.
To understand the 20-year horizon, we must look beyond mere preservation and examine how different asset classes compound over multi-decade periods. Historically, the long-term annualized return of the broader stock market (such as the S&P 500) has hovered around 7% to 10% nominally, or roughly 4% to 6% after adjusting for historical inflation. Conversely, conservative assets like cash equivalents and certificates of deposit (CDs) often lag behind or barely match the rate of inflation, resulting in a net-zero or negative real return once taxes are factored in.
Scenario Modeling: Three Possible Futures Over 20 Years
To see what $1 million can truly become, let us model three distinct financial strategies over a 20-year period, assuming a starting principal of $1,000,000 and a steady baseline inflation rate of 2.5% annually.
1. The Conservative Strategy (Cash & Short-Term Fixed Income)
Assumed Annual Return: 3.0% nominal
Projected Value After 20 Years: Approximately $1,806,111 nominal
Adjusted Purchasing Power (Real Value): Approximately $1,100,000 in today's dollars
The Reality: While your nominal dollar amount increases, after accounting for ordinary income taxes on interest and persistent inflation, your actual buying power remains virtually flat. You take on zero market volatility, but you pay a heavy opportunity cost by missing out on productive economic growth.
2. The Balanced Portfolio (60/40 Stocks and Bonds)
Assumed Annual Return: 6.5% nominal (mix of equities and fixed income)
Projected Value After 20 Years: Approximately $3,523,940 nominal
Adjusted Purchasing Power (Real Value): Approximately $2,145,000 in today's dollars
The Reality: This moderate approach outpaces inflation significantly. Your real purchasing power more than doubles. You experience intermediate market drawdowns along the way, but the ballast provided by fixed income softens the blow during economic downturns, making it a sustainable path for risk-averse growth investors.
3. The Growth-Focused Strategy (Equity-Heavy / Broad Market Indexing)
Assumed Annual Return: 9.0% nominal (historical equity average)
Projected Value After 20 Years: Approximately $5,604,411 nominal
Adjusted Purchasing Power (Real Value): Approximately $3,412,000 in today's dollars
The Reality: By accepting higher short-term volatility and multi-year market corrections, an equity-focused allocation multiplies your real purchasing power by more than threefold. This strategy demands emotional discipline, as sharp market drops will test your resolve, but it offers the most robust defense against long-term currency devaluation.
The Hidden Drag: Taxes, Fees, and Lifestyle Creep
Even the best investment models can be derailed by three invisible wealth-destroyers if they are not managed proactively:
Tax Drag: Capital gains, dividends, and ordinary income taxes chip away at your returns every single year in taxable brokerage accounts. Utilizing tax-advantaged structures—such as traditional or Roth IRAs, 401(k)s, or tax-efficient municipal bonds—can preserve hundreds of thousands of dollars over a 20-year timeline.
Investment Fees: High expense ratios, advisory fees, and hidden fund costs compound destructively over two decades. A seemingly minor 1% annual fee on a $1 million portfolio can siphon away over $250,000 in potential gains over 20 years due to the erosion of compounding.
Lifestyle Inflation: As your net worth grows, the temptation to expand your baseline living expenses increases. Protecting your core capital requires separating lifestyle growth from asset growth.
Strategic Action Plan: Maximizing Your Capital Over a 20-Year Horizon
If you are holding or managing a $1 million portfolio with a 20-year target, a passive approach is rarely optimal. Implementing a structured, disciplined framework will safeguard your purchasing power:
Audit Your Asset Allocation: Ensure your portfolio matches your actual risk tolerance and time horizon rather than sitting in cash. A blend of low-cost broad-market index funds and high-quality fixed income typically provides the optimal balance of growth and stability.
Optimize for Tax Efficiency: Move investments into tax-advantaged vehicles where possible, and harvest capital losses strategically in taxable accounts to offset gains.
Minimize Friction Costs: Switch from actively managed mutual funds with high expense ratios (above 0.50%) to low-cost exchange-traded funds (ETFs) or index funds to keep ongoing fees under 0.10%.
Establish a Rebalancing Schedule: Review your portfolio semi-annually or annually to lock in gains from outperforming asset classes and reallocate into undervalued sectors without triggering excessive tax events.
Conclusion
So, how much will $1 million be worth in 20 years? Mathematically, if you leave it under a mattress or in a zero-yield account, its purchasing power will shrink drastically under the persistent weight of inflation, leaving you with the real-world buying power of roughly $610,000 in today's terms.
However, if you treat that $1 million not as a static trophy, but as productive capital—invested wisely, shielded from excessive taxes and fees, and allowed to compound across diversified global markets—it can realistically grow into a powerhouse worth $3 million to $5.5 million in nominal value, more than doubling your true purchasing power. The future value of your wealth is ultimately decided not by macroeconomic forecasts, but by the intentional strategy you put into motion today.