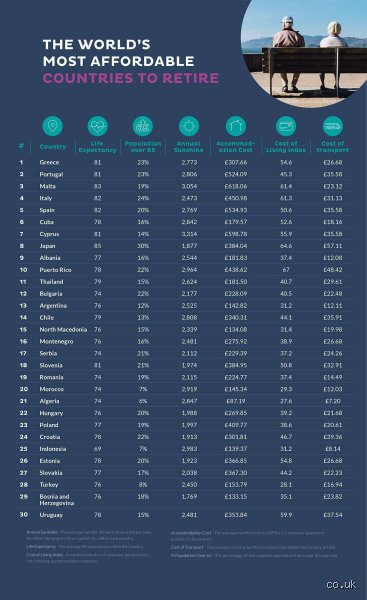
Yet, answering the core question—What is the cheapest and safest country to retire to?, is rarely as simple as pointing to a single dot on a map. "Cheap" and "safe" exist in a delicate, often tension-filled balance. The absolute cheapest places on earth often demand heavy compromises in political stability, legal protections for foreign property owners, or modern healthcare infrastructure. Conversely, the safest and most developed retirement havens often come with heavy tax burdens, high cost-of-living indexes, and strict bureaucratic visa hurdles.
Unlocking the ideal retirement destination requires looking past glossy travel brochures and examining the hard metrics: cost-of-living data, Global Peace Index rankings, healthcare accessibility, visa feasibility, and tax optimization.
The core dilemma: Balancing Financial economy with personal Security
When prospective expats begin crunching numbers, the allure of rock-bottom monthly budgets can easily overshadow the realities of local governance and safety. A destination where a couple can live on $800 a month sounds miraculous, but if that country suffers from civil unrest, weak property rights, or inadequate trauma care, a minor health emergency or legal dispute can quickly transform a dream retirement into a crisis.
To evaluate any country objectively, experts separate retirement suitability into four non-negotiable pillars:
Financial Sustainability (The "Cheap" Metric): This encompasses housing (renting versus buying), everyday groceries, dining out, utilities, and local transportation. Crucially, it also accounts for inflation and currency exchange rate fluctuations, which can erode a fixed pension over a span of twenty years.
Personal and Institutional Security (The "Safe" Metric): Safety extends far beyond low street-crime rates. It includes political predictability, low corruption indices, the protection of private property rights for foreign nationals, and reliable emergency services.
Healthcare Infrastructure: At age 60, 70, or 80, the proximity, cost, and quality of medical care matter more than scenic beaches or historic architecture. Access to English-speaking physicians, modern hospitals, and affordable health insurance can make or break a retirement choice.
Residency and Tax Friendliness: A country may be cheap and safe, but if its visa laws make long-term residency impossible, or if it taxes foreign pension income punitively, it fails the practical test.
Top contenders: Where low cost meets high safety
Synthesizing global indices, expat community feedback, and economic indicators highlights several standout regions that successfully bridge the gap between affordability and security.
1. The Mediterranean sweet spot: Greece and Cyprus
For retirees seeking European Union legal standards, political stability, and high safety rankings combined with a low cost of living, the Mediterranean has emerged as a powerhouse.
Greece, which has captured top spots in global retirement indexes, offers a relaxed lifestyle where a couple can live comfortably on $2,000 to $2,700 a month. Beyond its safety and climate, Greece features attractive tax incentives for foreign retirees, such as a flat 7% tax rate on foreign-source income for up to 15 years under specific residency setups, and world-class private healthcare networks in Athens and Thessaloniki.
Cyprus offers a similar English-friendly environment with robust legal frameworks, a low crime rate, and favorable tax treatment for pensioners, making it a favorite for those wanting European security without Western European price tags.
2. Latin America’s gold standards: Costa Rica and Panama
Latin America has long been a magnet for North American retirees, thanks to geographic proximity, favorable time zones, and established expat communities.
Costa Rica remains a beacon of peace in Central America. Lacking a standing army, the country prides itself on its Pura Vida philosophy, high literacy rates, and exceptional environmental safety. Through its Pensionado visa program, retirees with a modest, reliable lifetime pension income can easily secure residency and tap into both the public healthcare system (CAJA) and top-tier private clinics.
Panama offers a dollarized economy (eliminating foreign exchange risk for U.S. retirees), modern first-world infrastructure in Panama City, and the legendary Pensionado program, which grants deep discounts on everything from medical services to entertainment.
3. Southeast Asian value: Malaysia and Thailand
For retirees willing to look further east, Southeast Asia delivers staggering value for money alongside modern urban conveniences.
Malaysia consistently ranks high on peace indexes within the region and features vibrant, cosmopolitan hubs like George Town (Penang), where English is widely spoken and modern healthcare is remarkably inexpensive. While long-term visa requirements have evolved, the financial threshold for daily living remains remarkably low for those with private savings or pensions.
(This concludes Part 1 of our expert analysis. In Part 2, we will break down exact budget line items, hidden costs like international health insurance, visa application pitfalls, and a definitive verdict on which country best fits specific retirement profiles.)
Balancing cost and safety: The ultimate strategic matrix
When evaluating global retirement destinations, looking at cost-of-living indexes in isolation can be dangerously misleading. A country where you can live on $800 a month is of little use if you face systemic safety vulnerabilities, unreliable property title laws, or an underdeveloped healthcare infrastructure that forces you to fly back home for basic medical interventions.
The most successful international retirements depend on finding the exact intersection between affordability, personal security, legal stability, and accessible, high-standard healthcare.
Regional deep dive: Where low cost meets high Security
1. Southern Europe: Greece and Portugal
For retirees prioritizing robust legal frameworks, EU consumer protections, and low violent crime rates, Southern Europe remains a top-tier choice.
Greece: Emerging as a leading European haven, Greece combines a relaxed Mediterranean pace of life with monthly living costs for a couple ranging between $1,600 and $2,200. The country features exceptional private medical networks in Athens and Thessaloniki, alongside welcoming residency options such as the Financially Independent Person (FIP) visa route.
Portugal: Though coastal hotspots like Lisbon and the central Algarve have seen significant price increases, interior regions and the Silver Coast still offer peaceful, secure living on moderate budgets, backed by the stable D7 passive-income framework## Section 5: Healthcare Infrastructure and Quality of Life
When evaluating countries that offer an economical cost of living, prospective retirees often make the critical mistake of prioritizing low rent and inexpensive groceries while overlooking healthcare. As we age, access to reliable, high-quality, and affordable medical care becomes the single most important factor determining both longevity and financial security. A country can boast the cheapest housing in the world, but if a single medical emergency or chronic condition can bankrupt you or subject you to substandard care, the financial savings are entirely negated.
The nations that consistently rank at the top of affordability and safety indices, such as Portugal, Spain, Costa Rica, and Malaysia, do so largely because they have invested heavily in robust public healthcare networks while simultaneously offering exceptional, internationally accredited private medical systems at a fraction of Western costs. For instance, in Costa Rica, legal residents who contribute to the state social security system, known as the Caja Costarricense de Seguro Social (CCCA), gain access to universal healthcare for a monthly fee scaled to their declared income (typically ranging from 7% to 11% of reported monthly earnings). This covers everything from routine checkups to major surgeries and prescriptions, with zero out-of-pocket deductibles.
Similarly, Malaysia has quietly emerged as a global hub for medical tourism. Hospitals in Kuala Lumpur and Penang boast accreditation from the Joint Commission International (JCI), the gold standard for global healthcare quality, and are staffed by physicians who received their training in the United Kingdom, the United States, or Australia. A routine doctor's visit that might cost $200 in the United States often runs between $20 and $40 in Malaysia, while major procedures can be performed for 70% to 80% less than Western prices without compromising on sterile, modern facilities or English-speaking staff.
Beyond physical medicine, "quality of life" encompasses the intangible yet vital elements of daily existence: clean air, walkable communities, vibrant social opportunities, safety from violent crime, and cultural integration. Safety is a paramount pillar for retirees. Moving abroad to save money is counterproductive if you constantly have to look over your shoulder or live behind gated communities with private armed guards.
Portugal and Spain consistently occupy the top twenty spots on the Global Peace Index, offering remarkably low rates of violent crime, safe public transportation at all hours, and pedestrian-friendly historic city centers where older adults can walk evening promenades without fear. Costa Rica, while experiencing property crime in certain tourist zones, remains a politically stable democracy with no standing army, fostering a peaceful culture encapsulated by the local phrase pura vida (pure life), a daily ethos centered on community, low stress, and appreciation for the natural world.
Financial mechanics: Visas, taxes, and cost of living math
Moving abroad is ultimately a financial equation, and solving it requires understanding the complex interplay between foreign residency visas, local tax laws, and currency exchange risks. You cannot simply pack your bags and move permanently to another country; you must secure legal status through specific retirement or passive-income visa programs designed to attract foreign capital without threatening local job markets.
Most budget-friendly retirement destinations have tailored pathways for expatriates:
The Non-Lucrative Visa (Spain) / D7 Visa (Portugal): These European options require proof of a stable, passive income from pensions, rental properties, dividends, or remote work, typically around the local minimum wage multiplied by a factor (e.g., roughly €820 to €1,000 per month for the primary applicant). They grant legal residency and access to the Schengen Area, though they generally require you to spend a minimum number of months per year physically residing in the country to maintain status.
The Pensionado Visa (Costa Rica / Panama): These programs require applicants to prove a guaranteed lifetime monthly income from a retirement fund, pension, or social security (usually a minimum of $1,000 to $2,500 per month). In exchange, they offer streamlined residency processing, tax exemptions on the importation of household goods and vehicles, and swift pathways to permanent residency.
The Malaysia My Second Home (MM2H) Program: Though restructuring periodically with shifting financial thresholds, this initiative targets affluent retirees by requiring specific fixed-deposit sums in local banks alongside proof of monthly offshore income, granting long-term multi-year social visit passes.
Navigating tax liabilities is equally complex. Many retirees mistakenly believe that moving abroad frees them from their home country's tax obligations. If you are a U.S. citizen, for instance, you are taxed on your worldwide income regardless of where you live, though mechanisms like the Foreign Earned Income Exclusion (FEIE) and Foreign Tax Credits can mitigate double taxation. Destination countries have distinct tax treatments for foreign pensions. Portugal’s former Non-Habitual Resident (NHR) regime famously offered tax-free or heavily reduced rates on foreign-sourced pensions for a decade, and while the program has evolved, transitional rules and alternative incentives continue to attract retirees seeking favorable fiscal environments.
Currency fluctuation is the final wild card in the retirement math. When your pension is paid in U.S. Dollars, British Pounds, or Canadian Dollars, but your daily expenses are paid in Euros, Costa Rican Colones, or Malaysian Ringgit, a shifting exchange rate can suddenly increase your cost of living by 15% to 20% in a matter of months. Prudent financial planning requires maintaining diversified accounts, locking in rates when favorable, and building a buffer into your monthly budget to absorb macroeconomic volatility.
Overcoming culture shock and integration challenges
The physical relocation to a cheaper, safer country is only the first chapter of the retirement journey; the psychological and social transition is where many expatriates stumble. Uprooting your life to move thousands of miles away from your lifelong social support network, family, and cultural touchstones can trigger profound isolation and culture shock, even in paradise.
The most successful retirees are those who approach relocation not as an indefinite vacation, but as an active exercise in community building and cultural immersion. Language barriers, bureaucratic friction, and different societal norms can transform minor inconveniences into major sources of frustration if met with impatience. For example, bureaucratic processes in Latin America or Southern Europe often operate at a slower, more deliberate pace, frequently referred to as mañana culture or a more relaxed approach to time. Learning to embrace this slower rhythm rather than fighting it is essential for mental well-being.
Integration requires deliberate effort:
Language Acquisition: While you can easily survive in expat enclaves in Portugal, Costa Rica, or Panama speaking only English, true integration and independence require learning the local language. Even basic conversational proficiency in Spanish or Portuguese transforms your daily interactions, deepens relationships with locals, protects you from being overcharged, and grants you access to authentic cultural experiences.
Expat Communities vs. Local Immersion: Striking the right balance is crucial. Expat groups provide invaluable practical advice on navigating local healthcare, finding reliable mechanics, and dealing with tax paperwork. However, isolating yourself entirely within an insular expat bubble often leads to superficial living and amplified complaints about local infrastructure. Engaging with local volunteer organizations, sports clubs, or community classes bridges the gap.
Maintaining Ties Back Home: Modern communication technology makes it easier than ever to maintain close connections with children and grandchildren left behind. Establishing regular video call routines and setting clear plans for annual visits helps alleviate homesickness and maintains the vital multi-generational bonds that anchor our emotional health.
The "cheapest and safest" country to retire to is not a universal destination found on a spreadsheet; it is the country that best aligns with your personal values, medical needs, financial constraints, and psychological readiness for adventure. Whether it is the historic coastal charm of Portugal, the tranquil biodiversity of Costa Rica, or the modern, multicultural dynamism of Malaysia, the ultimate reward of an international retirement is the realization that reinvention has no age limit, and that a secure, fulfilling, and financially sustainable future is entirely within your grasp.