The context and evolution of machine learning systems
To fully appreciate modern machine learning, it helps to understand the shift from traditional rule-based programming to data-driven discovery. Early computing relied entirely on human-written rules to process inputs into outputs. Machine learning flips this paradigm by taking inputs and known outcomes to automatically derive the rules.
The shift from traditional programming
Traditional software development requires developers to explicitly define every logic branch and condition. While effective for predictable tasks, this approach collapses when dealing with complex, high-dimensional problems like computer vision, natural language processing, or complex financial forecasting. Machine learning addresses this limitation by letting algorithms discover correlations directly from historical datasets, reducing the burden of manual rule-creation.
Why robust architecture matters
As datasets scale into the petabyte range, the underlying structure of a machine learning system dictates its performance, maintainability, and cost-efficiency. A well-designed architecture ensures that data flows smoothly from storage systems through preprocessing pipelines, model training environments, and finally into production deployment. Without a solid structural foundation, models often suffer from data bottlenecks, slow training times, and poor generalization on unseen data.
How machine learning systems work
The operational workflow of machine learning follows a systematic lifecycle, moving from raw data collection to continuous model improvement. Each stage relies on specific technical processes to refine information and optimize predictive accuracy.
Data ingestion and preprocessing
Before any algorithm can learn, it requires clean, structured data. This phase involves gathering raw data from diverse sources, handling missing values, normalizing numerical ranges, and encoding categorical variables. Effective preprocessing prevents bias and ensures that the model trains on high-quality signals rather than noisy artifacts.
Model training and evaluation
During training, the algorithm analyzes the prepared data using mathematical optimization techniques to minimize errors. The dataset is typically split into training, validation, and test sets. The model learns from the training set, tunes its internal parameters using the validation set, and undergoes final unbiased performance evaluation on the test set to measure real-world reliability.
Inference and Deployment
Once trained and validated, the model moves from a development environment into production, where it performs inference on live incoming data. Deployment architectures must ensure low latency, high availability, and seamless integration with existing software applications so users can receive real-time predictions or recommendations.
Key components of model architecture
Beneath the surface of any machine learning pipeline lie core mathematical and structural building blocks that govern how data is represented and processed.
Features, weights, and biases
Features represent the measurable properties or characteristics of the data being analyzed. Inside the model, algorithms assign numerical weights and biases to these features to determine their relative importance. During training, the system iteratively adjusts these weights to strengthen correct predictions and minimize incorrect ones.
Loss functions and optimization algorithms
To know how well a model is performing, the architecture employs a loss function that quantifies the difference between predicted outputs and actual outcomes. An optimization algorithm—such as gradient descent—then uses this loss value to guide the adjustments of model parameters, steering the system toward optimal performance over multiple training iterations.
The mechanics of Corporate governance and the "hidden power"
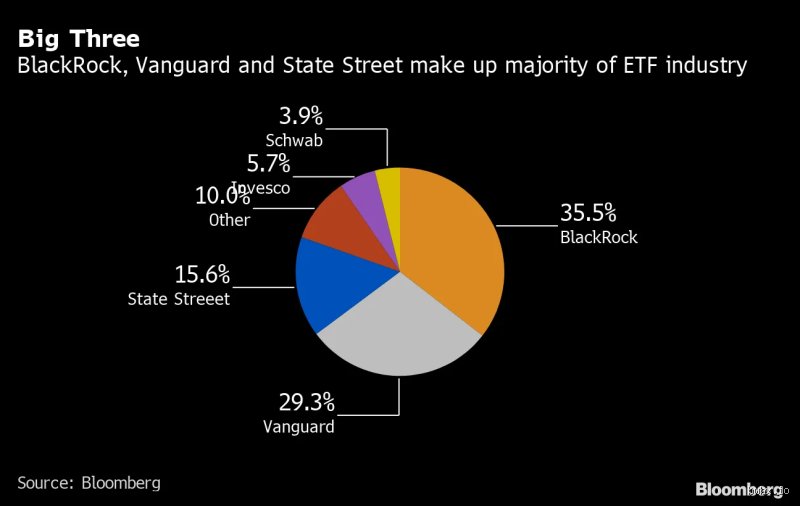
As Vanguard, BlackRock, and State Street Global Advisors (SSGA) accumulated unprecedented blocks of equity, collectively estimated to own roughly 20% to 25% of the average S&P 500 corporation, their role evolved from passive bystanders to the most influential power brokers in global capitalism.
This concentration of ownership sparks an urgent debate among economists, legal scholars, and regulators: How do asset managers who promise to passively mirror an index wield such active authority over corporate boardrooms?
The Stewardship Paradox
The traditional theory of index investing assumes that because funds are unmanaged, simply tracking a benchmark like the S&P 500 or Russell 2000 without trying to beat it, the fund managers have little incentive or desire to meddle in corporate affairs. However, the sheer size of the Big Three makes exit impossible.
If BlackRock or Vanguard dislikes the strategic direction of Apple, Microsoft, or ExxonMobil, they cannot simply "vote with their feet" and sell the stock. Because their core mandate is to track the entire index, they must hold these shares regardless of management performance.
Consequently, voice has entirely replaced exit. The Big Three maintain massive internal Investment Stewardship teams dedicated to meeting with corporate executives, reviewing proxy ballots, and voting on everything from executive compensation packages and environmental disclosures to board diversity and mergers and acquisitions.
The Persuasion Channel: Research from institutions like the Wharton School highlights that the Big Three’s influence is rarely exercised through overt, hostile threats. Instead, it operates through institutional access and persuasion. When a stewardship officer from Vanguard or BlackRock requests a meeting, corporate boards listen immediately.
Standardized Expectations: Because they manage thousands of companies simultaneously, the Big Three establish universal governance templates. Issues like carbon transition plans, cybersecurity oversight, and board independence are codified into proxy voting guidelines that corporate America ignores at its peril.
Systemic risks and the Anti-Competitive debate
While the democratization of investing through low-cost index funds has saved retail investors billions of dollars in fees, the structural dominance of the Big Three introduces complex systemic vulnerabilities.
1. Common ownership and market competition
A major academic critique centers on the phenomenon of "horizontal shareholding" or common ownership. When the same three entities hold top-five stake positions across competing firms within the same industry, such as major airlines, pharmaceutical giants, or mega-banks, incentives for aggressive price competition can theoretically be dampened.
If BlackRock, Vanguard, and State Street own simultaneous stakes in Delta, United, and American Airlines, economic models suggest that management teams may face muted pressure to engage in destructive price wars, knowing that their largest institutional shareholders prefer industry-wide stability and aggregate profit maximization over cutthroat market share battles.
2. Operational and market infrastructure vulnerabilities
The concentration of trillions of dollars under three corporate umbrellas creates single points of failure in financial plumbing. For instance, BlackRock’s proprietary risk-management and trading software platform, Aladdin (Asset, Liability, Debt and Derivative Investment Network), manages tens of trillions of dollars in assets globally, not just for BlackRock, but for competing asset managers, pension funds, and central banks.
While Aladdin provides unmatched visibility into risk and market shocks, its widespread adoption means that a systemic software glitch, cyber-attack, or correlated miscalculation within the platform could propagate instantaneously across international financial markets.
The Regulatory horizon: Pass-Through Voting and the future
In response to growing concerns over market concentration and political pushback regarding corporate social priorities, the regulatory landscape surrounding the Big Three is shifting rapidly.
+-----------------------------------------------------------------+
THE EVOLVING BIG THREE ECOSYSTEM
+-----------------------------------------------------------------+
[ Retail & Institutional Investors ] (Capital Providers)
│
▼
[ BlackRock | Vanguard | State Street ] (The Big Three)
│
├──> Owns ~20-25% of S&P 500 Equities
├──> Controls trillions in passive index assets
│
▼
[ Corporate Boardrooms ] (Influence via Stewardship & Voting)
│
▼
[ Regulatory Pressures ] ──> Push toward "Pass-Through Voting"
+-----------------------------------------------------------------+
Policymakers have increasingly scrutinized whether asset managers should retain absolute authority to cast proxy votes on behalf of millions of everyday investors who may hold conflicting personal, political, or economic values.
The Rise of Pass-Through Voting: Legislative proposals and voluntary industry shifts, such as the expansion of pass-through voting options, aim to empower individual retirement savers and pension participants to direct how their proportional share of stock is voted. By allowing underlying investors to choose whether proxy votes align with environmental goals, traditional growth metrics, or neutral economic stewardship, the industry seeks to decentralize the immense voting power currently concentrated in the hands of the Big Three executives.
Fee Compression and Margin Pressures: As passive investing becomes a commodity market dominated by a fierce race to zero-fee structures, the Big Three are continuously forced to innovate. BlackRock leverages its technological edge via Aladdin and active ETF expansions, Vanguard relies on its unique client-owned mutual structure to continually slash expense ratios, and State Street anchors its dominance in institutional custody and foundational liquidity products like the SPY ETF.
Conclusion
The Big Three, BlackRock, Vanguard, and State Street, are no longer mere financial intermediaries; they are the foundational architectural pillars of modern global capitalism. By routing the collective savings of hundreds of millions of everyday workers into centralized index funds, they have fundamentally altered corporate governance, price discovery, and market liquidity.
As they navigate intensifying regulatory scrutiny, political crosswinds, and the transition toward personalized, pass-through voting structures, their influence over the destiny of public corporations will remain the single most defining dynamic of twenty-first-century financial markets.