The Trillion-Dollar elephant in the room
When artificial intelligence (AI) exploded onto the global economic stage, propelling Nvidia—the powerhouse designer of graphics processing units (GPUs) powering the generative AI revolution—into the stratosphere of market capitalization, onlookers naturally wondered: What is Buffett doing? Why isn’t Berkshire Hathaway buying Nvidia?
The short answer is both strikingly simple and deeply nuanced: Warren Buffett has never owned a direct, material stake in Nvidia. To grasp why the world’s most famous investor has bypassed the defining technological titan of the 2020s, we must examine the intersection of his core investment tenets, economic moats, technological predictability, long-term capital allocation, and risk management, with the meteoric, high-stakes evolution of the semiconductor industry.
Part I: The unyielding power of the "circle of competence"
To decode Buffett’s stance on Nvidia, one must look at his foundational rule: the circle of competence. Buffett has frequently repeated that an investor does not need to understand every business, nor do they need to be right about every hot industry. What they need to do is correctly evaluate the economic future of companies within their defined circle.
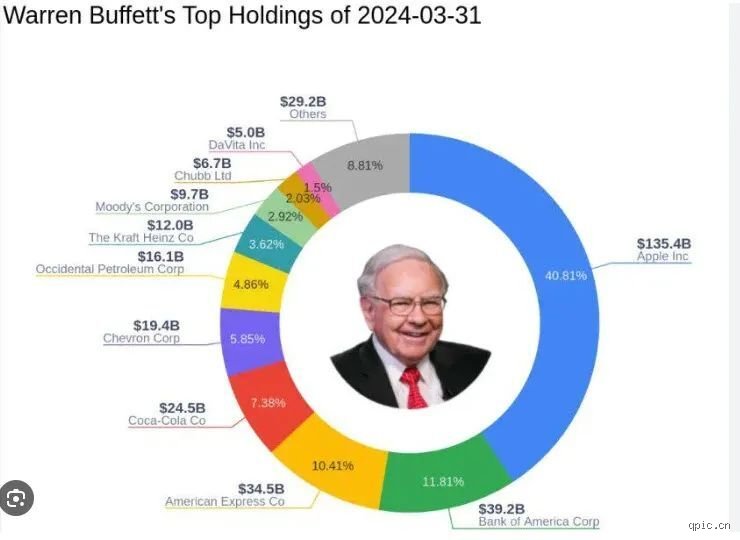
For Buffett, his circle has historically included insurance, railroads, energy utilities, consumer staples (like Coca-Cola and Kraft Heinz), and selective financial institutions or large-scale consumer brands (like Apple, though Apple itself represents a multi-decade evolution in Buffett's thinking regarding consumer habit formation and ecosystem lock-in). Semiconductors, hardware architecture, and cutting-edge artificial intelligence infrastructure, however, sit comfortably outside the boundaries of what Buffett considers predictable.
Why complexity breeds unpredictability
Semiconductor manufacturing and design represent some of the most capital-intensive, hyper-competitive, and rapidly shifting technological environments on earth. Moore’s Law dictates relentless advancement, where billions of transistors are packed onto silicon wafers with microscopic tolerances, and architectural shifts can render a market leader obsolete in a matter of years.
Buffett has often noted that he looks for businesses with enduring competitive advantages that can be easily understood by a layperson. When evaluating a business, he asks: What will this company look like in ten or twenty years?
Can a disruptive startup erode its market share?
Will an alternative architecture, such as application-specific integrated circuits (ASICs), custom tensor processing units (TPUs) built by hyperscalers like Google, or quantum computing breakthroughs, dismantle the necessity of the general-purpose GPU?
Because the technological half-life of advanced microprocessors is notoriously difficult to forecast with absolute certainty, Nvidia fails Buffett’s core test of long-term operational visibility. Even if a business is extraordinarily profitable today, boasting industry-leading gross margins, multi-billion-dollar backlogs, and an effective monopoly on training frontier large language models, the rapid pace of innovation introduces a degree of structural vulnerability that makes long-term discounted cash flow (DCF) modeling inherently speculative. Buffett does not speculate; he invests based on visibility.
Part II: Evaluating Nvidia through the lens of the "economic moat"
While Buffett may bypass complex hardware companies, he is an obsessive student of "economic moats", the structural features that allow a company to sustain high returns on capital over long horizons. By several conventional metrics, Nvidia possesses one of the widest and most formidable economic moats in corporate history.
The Hardware-Software ecosystem moat
Nvidia’s dominance is not merely a function of manufacturing lightning-fast silicon. Its true genius lies in CUDA (Compute Unified Device Architecture), a proprietary software ecosystem released by the company nearly two decades ago. CUDA allowed developers to harness GPUs for general-purpose parallel computing long before the generative AI boom materialized.
Consequently, virtually every major artificial intelligence framework, machine learning library, and software developer toolkit has been optimized for the CUDA programming model. This creates a powerful network effect: researchers and enterprises write software for Nvidia hardware because that is where the tools work best, and Nvidia sells more hardware because all the software is written for it.
If Buffett were to analyze Nvidia’s moat purely through an operational lens, he would undoubtedly admire it. In many ways, CUDA functions like an invisible, high-switching-cost tollbooth across the entire digital economy, reminiscent of the network effects that protect payment processors like Visa and Mastercard, or the operating system dominance of early Microsoft.
The Cyclicality Paradox
Yet, a wide moat does not automatically insulate a company from cyclical volatility, a factor that has historically troubled value-focused capital allocators. Historically, the semiconductor and hardware infrastructure sectors are intensely cyclical. Demand tends to surge during infrastructure build-out super-cycles, followed by periods of overcapacity, inventory digestion, and sharp corrections.
While the artificial intelligence wave introduced unprecedented enterprise urgency, transforming GPUs into mission-critical corporate assets rather than discretionary data center upgrades, the underlying capital expenditure (capex) cycle remains tied to the balance sheets of a handful of mega-cap technology oligopolies (such as Microsoft, Meta, Alphabet, and Amazon). If these hyperscalers decide to rein in their data center spending, or if alternative silicon solutions (like custom internal accelerators) successfully siphon away market share, Nvidia’s staggering growth rates could experience sharp normalization. Buffett has historically avoided businesses whose earnings power is fundamentally tethered to the aggressive, lumpy capital expenditure cycles of third-party customers.
Part III: Management, culture, and the human element
Beyond financial statements and balance sheets, Buffett places immense emphasis on corporate leadership, shareholder alignment, and corporate culture. He prefers managers who are rational, conservative with capital allocation, focused on long-term shareholder value, and beyond reproach when it comes to institutional integrity and corporate governance.
The leadership of Jensen Huang, Nvidia’s long-time co-founder and visionary architect, has been instrumental in transforming the company from a niche gaming-graphics provider into the nerve center of global artificial intelligence. Huang’s willingness to bet the company’s balance sheet on parallel computing decades before the market recognized its utility is a masterclass in visionary entrepreneurship, traits that Buffett deeply respects in founders like Jeff Bezos or Bill Gates.
However, corporate governance and leadership stability are paramount in Berkshire Hathaway’s universe. Recent corporate turbulence, unexpected executive shifts, and the high-stakes drama surrounding high-profile leadership changes in the broader tech ecosystem serve as reminders of why Buffett prefers boring, decentralized conglomerates over high-flying, personality-driven technology darlings. When a company’s valuation and identity are deeply intertwined with a single charismatic leader, the key-person risk becomes an existential factor that conservative long-term investors must carefully price in.
Part IV: The valuation question, price vs. Value
Even if a business possesses a wide moat and brilliant leadership, Buffett’s philosophy is governed by the famous maxim taught by his mentor, Benjamin Graham: "Price is what you pay; value is what you get."
The arithmetic of Hyper-Growth valuations
During phases where Nvidia’s market capitalization oscillated near historic peaks, surpassing multi-trillion-dollar valuations, the fundamental math required to justify the stock price demanded continuous, flawless execution against astronomical expectations. To generate a satisfactory investment return on a multi-trillion-dollar enterprise, a company must sustain extraordinary cash flow generation over decades.
Buffett and his late business partner, Charlie Munger, frequently cautioned against buying great businesses at silly prices. Even wonderful companies can become poor investments if the initial purchase price bakes in decades of uninterrupted perfection. Berkshire Hathaway’s massive cash pile, frequently reaching record highs in recent quarters, reflects Buffett’s disciplined refusal to deploy capital into assets where the margin of safety is thin or nonexistent. For Berkshire, sitting on cash yielding safe short-term returns is vastly preferable to chasing speculative momentum in over-extended equity sectors.
Conclusion of part I: The philosophical divide
In summary, Warren Buffett’s perspective on Nvidia is not one of dismissal, but rather of disciplined detachment. He recognizes Nvidia as a monumental engineering triumph with an extraordinarily wide economic moat and a transformative role in global technology. Yet, because the underlying semiconductor ecosystem falls outside his circle of competence, carries high cyclical and technological obsolescence risks, and frequently trades at valuations that leave little room for error, the Oracle of Omaha remains on the sidelines, leaving the AI hardware trade to those whose risk frameworks and forecasting models are built for the fast-paced, volatile world of frontier technology.
Navigating the tech horizon: The Buffett test for Nvidia
When evaluating high-growth market powerhouses, financial analysts and retail investors alike frequently return to the philosophy of Warren Buffett. While Berkshire Hathaway has famously expanded its horizons into select technology giants like Apple in past decades, the Oracle of Omaha’s overarching investment framework remains anchored in enduring principles: predictable cash flows, understandable business models, an unassailable economic moat, and pristine corporate governance.
Applying this rigorous lens to Nvidia (NASDAQ: NVDA) reveals a fascinating dichotomy. On one hand, Nvidia represents the quintessential modern monopoly, a company commanding immense market share in accelerated computing, driving the global artificial intelligence revolution with profit margins that traditional manufacturers envy. On the other hand, it challenges nearly every traditional risk parameter that Buffett has preached to shareholders for over half a century.
1. The core tension: Moats vs. Technological velocity
Buffett’s primary hesitation regarding fast-moving technology sectors has never been a disbelief in innovation itself. Rather, it stems from the difficulty