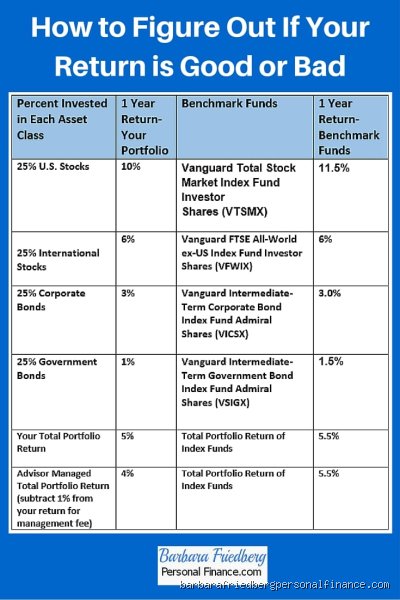
...Having established the baseline definition of investment returns and the crucial divergence between nominal and real gains, we must now examine how different asset classes perform across various economic cycles. Understanding what constitutes a "good" return requires looking beyond a single arbitrary percentage and contextualizing your expectations within the specific vehicle you are using to grow your wealth.
Asset class benchmarks: What to expect where
Different investment vehicles carry vastly different risk profiles, and their historical benchmarks reflect that reality. When evaluating your portfolio, use these asset-specific benchmarks rather than applying a blanket standard across the board:
The Stock Market (Equities): Historically, the broad stock market (as measured by indexes like the S&P 500) has delivered an average nominal return of roughly 9% to 10% per year over long periods. Once you adjust for an average historical inflation rate of 2% to 3%, the real return sits comfortably around 7%. Therefore, a long-term equity portfolio returning 7% to 10% annually is performing in line with historical market averages. Anything significantly higher consistently over the long term is exceptional, while anything consistently lower may indicate an inefficient asset allocation or excessive fees.
Fixed Income (Bonds): Bonds are designed for capital preservation and income generation rather than aggressive growth. Historically, aggregate bond indexes have returned around 4% to 6% annually. In periods of higher interest rates, yields on government and high-grade corporate bonds may creep higher, but they rarely match the long-term growth potential of stocks. A good return for a bond portfolio is one that outpaces inflation while providing a stable cushion against stock market volatility.
Real Estate: Real estate investments can generate returns through two distinct mechanisms: rental cash flow (yield) and property appreciation. Traditional residential or commercial real estate investments often target total returns (cash flow plus appreciation) in the 8% to 12% range. However, real estate requires active management, maintenance costs, and liquidity considerations that stocks do not.
High-Yield Savings Accounts and Certificates of Deposit (CDs): These are cash equivalents. Because they carry virtually no market risk (up to insured limits), their returns are tied closely to central bank interest rates. In a normal economic environment, a good return here simply means keeping pace with inflation to preserve your purchasing power.
The core drivers of a "good" return
When determining whether your personal investment strategy is yielding a "good" return, three foundational pillars must be factored into your evaluation: Inflation, Time Horizon, and Risk Tolerance.
1. The Inflation reality check
As touched upon earlier, a nominal return is not the same as a real return. If your investment account grows by 5% in a year, but the inflation rate is 4%, your actual increase in purchasing power is a meager 1%.
A truly good return is one that beats inflation by a comfortable margin. If your investments are not outstripping the rising cost of everyday goods, services, and housing, your wealth is effectively stagnating or shrinking in real terms. Always calculate your net return after accounting for inflation, taxes, and investment management fees. High expense ratios or advisory fees can quietly siphon off 1% to 2% of your returns every single year, turning an otherwise good investment into a mediocre one.
2. The Time Horizon factor
Your timeline dictates your risk capacity and, consequently, what constitutes a successful return.
Short-Term Goals (1 to 3 years): If you are saving for a down payment on a house or an emergency fund, you cannot afford high volatility. In this scenario, a 4% to 5% safe return in a high-yield savings account or short-term treasury bill is an excellent outcome because safety of principal is your top priority.
Long-Term Goals (10 to 30+ years): If you are investing for retirement decades away, short-term market drops do not matter as much. Your benchmark should be aligned with long-term equity growth (7% to 10% nominal). A conservative 4% return over a 30-year horizon is actually a poor outcome for a retirement portfolio, as it leaves massive amounts of potential compounding growth on the table.
3. Risk Tolerance and volatility
It is easy to look at a high-flying asset class that returned 30% in a single year and feel like your 8% portfolio is underperforming. However, risk and reward are inextricably linked.
To achieve higher returns, you must expose yourself to higher volatility—the emotional and financial rollercoaster of seeing your portfolio drop significantly during market corrections. A "good" return must be evaluated on a risk-adjusted basis. If Investor A achieves a 12% return by taking reckless, concentrated gambles that could wipe out their principal at any moment, and Investor B achieves a steady 9% return through a globally diversified, low-cost index fund portfolio, Investor B's strategy is far superior for long-term financial health. Consistency and peace of mind hold immense value.
Common pitfalls in evaluating returns
Investors often fall into psychological traps when tracking their performance. Avoiding these mistakes will help you maintain a realistic and healthy perspective on your wealth-building journey:
Chasing Past Performance: Selecting a mutual fund, stock, or cryptocurrency simply because it had an incredible return last year is a classic investing fallacy. Markets are cyclical; sectors that outperform one decade often lag the next.
Comparing Yourself to Others: Social media is filled with hyper-concentrated success stories or exaggerated claims of overnight crypto and trading fortunes. True wealth building is quiet, systematic, and gradual. Comparing your diversified portfolio's steady 8% return to a viral outlier online will only lead to dangerous speculation.
Ignoring Costs and Taxes: A 10% gross return can easily become a 7% net return once capital gains taxes, dividend taxes, and management fees are deducted. Always focus on what ends up in your pocket, not just the headline number on your brokerage statement.
Crafting your personal definition
What is considered a "good" percentage return on an investment is deeply personal. It is not a fixed mathematical constant, but rather a dynamic target tailored to your individual circumstances.
A good return is one that successfully bridges the gap between where you are today and the financial goals you have set for your future—whether that means funding a comfortable retirement, buying a home, or achieving financial independence. By focusing on low-cost diversification, beating inflation, aligning your strategy with your time horizon, and keeping your emotions in check, you set yourself up for long-term financial success that transcends short-term market noise.