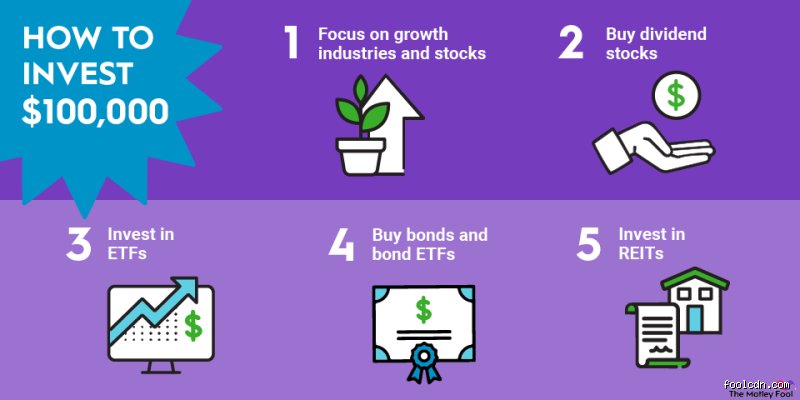
However, the psychological gravity of a lump sum this size often induces paralysis. The modern financial media landscape is saturated with conflicting prescriptions. Cryptocurrency maximalists promise generational wealth through high-beta digital assets; real estate syndicators advocate for physical bricks and mortar; growth-stock evangelists point toward artificial intelligence innovators; and conservative traditionalists preach safety in municipal bonds and certificates of deposit.
The fundamental truth—and the starting point of any sophisticated financial plan, is that there is no single "best" investment for $100,000. The optimal allocation is entirely a function of your personal time horizon, risk capacity, tax jurisdiction, liquidity requirements, and overarching life objectives. What constitutes an exceptional portfolio for a 25-year-old software engineer saving for a 35-year retirement horizon would be disastrous for a 62-year-old pre-retiree needing capital preservation to fund an upcoming transition.
This comprehensive guide serves as the first part of an expert-level exploration into deploying a $100,000 capital block. We will deconstruct the psychological traps of lump-sum investing, evaluate foundational baseline prerequisites, and examine the core asset classes through a rigorous, analytical lens.
Part I: The baseline audit, preparing capital before Deployment
Before a single dollar of your $100,000 is allocated to equities, real estate, or alternative assets, you must conduct a rigorous baseline audit of your broader financial ecosystem. Deploying capital into growth assets while ignoring structural vulnerabilities is akin to building a luxury home on a shifting foundation.
1. The liquidity shield (Emergency reserves)
A common mistake among investors receiving a lump sum is deploying 100% of the funds into illiquid or volatile markets. If your $100,000 represents your entire net worth outside of primary retirement accounts, a portion of it, typically three to six months of essential living expenses (or six to twelve months for freelancers, business owners, or single-income households), must be ring-fenced as an emergency fund.
Even though this cash will yield a lower nominal return than equities, it acts as structural insurance. Without it, an unexpected job loss, medical emergency, or major home repair could force you to liquidate your investment portfolio during a cyclical market downturn, locking in permanent capital losses. If your baseline living expenses total $4,000 a month, parking $15,000 to $24,000 in a high-yield savings account or Treasury bill ladder is not "dead money"; it is the risk-mitigation anchor that allows you to take calculated risks with the remaining balance.
2. High-Interest debt eradication
In personal finance, paying down high-interest debt is mathematically identical to earning a risk-free, tax-equivalent return equal to the interest rate on that debt.
If you hold credit card debt, personal loans, or auto loans charging 12% to 24% annual interest, paying them off with a portion of your $100,000 guarantees an immediate, risk-free economic return that far outperforms historical equity market averages (which hover around 7% to 10% nominal, before inflation and taxes).
Conversely, low-interest debt, such as a fixed-rate mortgage secured at 3% or 4% during historical low-rate environments, presents a different calculus. With risk-free savings rates and short-term government bonds yielding over 4% to 5%, paying off a low-interest mortgage early destroys arbitrage value. You are better off maintaining the mortgage and deploying capital into higher-yielding instruments.
Part II: The three pillars of wealth Allocation for 0,000
Once your emergency reserves are secured and toxic debt is eliminated, you can categorize your remaining capital deployment into three primary architectural frameworks. Depending on your risk profile, your $100,000 will typically be distributed across one or a combination of these pillars.
+-----------------------------------------------------------------+
| $100,000 CAPITAL DEPLOYMENT |
+-------------------------------------+---------------------------+
|
+----------------------------+----------------------------+
| | |
v v v
+------------------+ +------------------+ +------------------+
| PILLAR I: | | PILLAR II: | | PILLAR III: |
| Passive Public | | Real Estate | | Alternative & |
| Markets & ETFs | | & Tangible | | Growth Assets |
| (Core Growth) | | (Cash Flow) | | (Strategic) |
+------------------+ +------------------+ +------------------+
Pillar I: Passive Public Markets & Broad-Market indexing
For the vast majority of investors, the most efficient, cost-effective, and historically reliable destination for a significant portion of a $100,000 portfolio is the public equity and fixed-income markets via low-cost, broadly diversified exchange-traded funds (ETFs) or mutual funds.
The academic consensus, backed by decades of empirical data from Nobel laureates like Eugene Fama and William Sharpe, demonstrates that active stock picking consistently underperforms passive market indexing over long investment horizons, especially after accounting for transaction fees, management expense ratios (MERs), and tax inefficiencies.
Core-Satellite asset Allocation framework
With a $100,000 portfolio, you can construct a robust Core-Satellite portfolio:
The Core (70–80% of capital): Allocated to broad-market index funds that capture entire economies. Examples include total world stock index funds (e.g., VT) or a combination of S&P 500 funds (e.g., VOO/IVV) and international developed/emerging market funds. This provides instant diversification across hundreds or thousands of underlying corporations spanning technology, healthcare, financials, energy, and consumer goods.
The Satellites (20–30% of capital): Reserved for tactical, thematic, or factor-based allocations that align with your personal convictions, such as small-cap value tilts (which historically exhibit a size and value premium), dividend-growth equities for cash flow, or short-term fixed-income allocations to stabilize volatility.
Lump-Sum Investing vs. Dollar-Cost Averaging (DCA)
A perennial debate for individuals receiving a lump sum of $100,000 is whether to deploy the entire amount immediately (Lump-Sum Investing, or LSI) or phase it in incrementally over several months (Dollar-Cost Averaging, or DCA).
Financial research conducted by Vanguard and numerous academic institutions consistently reveals that lump-sum investing outperforms dollar-cost averaging approximately two-thirds of the time. Because global stock markets trend upward over long horizons, keeping cash on the sidelines waiting for a market correction exposes you to opportunity cost.
However, behavioral finance introduces a critical nuance. If the prospect of deploying $100,000 today causes you severe anxiety, leading to panic selling if the market dips 5% next month, then a structured 3-to-6-month DCA schedule is justified. The optimal strategy is the one you have the psychological discipline to execute and maintain through market volatility.
Pillar II: Real Estate and property investments
Real estate represents the second major asset class accessible to a $100,000 capital base. Unlike public equities, real estate offers a unique trifecta of financial benefits: capital appreciation, regular cash flow (rental income), and powerful tax advantages (depreciation, mortgage interest deductions, and 1031 exchanges).
However, $100,000 occupies an interesting threshold in real estate. It is generally insufficient to purchase a desirable residential investment property outright in major metropolitan areas, but it is more than adequate as a leveraged down payment or for alternative real estate structures.
1. Direct residential Real Estate (leveraged ownership)
In many suburban or secondary real estate markets, a $100,000 sum can comfortably cover a 20% down payment, closing costs, and initial working capital reserves for a single-family home or duplex valued between $350,000 and $400,000.
By utilizing a conventional investment property mortgage, you deploy your $100,000 to control a $400,000 appreciating asset. If the property appreciates by 4% annually, your nominal gain is calculated on the $400,000 total asset value, not merely your $100,000 equity stake, magnifying your return on equity (ROE) through leverage. Concurrently, tenant rental payments amortize the mortgage principal over time.
The Trade-Off: Direct real estate ownership is not passive. It introduces operational drag: tenant management, maintenance liabilities, property taxes, insurance premiums, and vacancy risks. It also concentrates your net worth into a single illiquid asset, violating the core diversification principle.
2. Real Estate Investment Trusts (REITs) and Syndications
If you prefer real estate exposure without the headaches of midnight plumbing repairs or tenant vetting, public REITs (traded on stock exchanges like individual equities) or private real estate syndications/crowdfunding platforms offer alternative pathways.
Public REITs provide instant liquidity and professional management, though they correlate more closely with broader equity markets during systemic shocks.
Private Syndications pool capital from accredited investors to acquire large multi-family apartment complexes, commercial retail centers, or industrial logistics hubs. While requiring higher capital minimums (often $50,000 to $100,000) and locking up capital for 3 to 7 years, syndications can generate attractive quarterly cash distributions and tax-advantaged depreciation write-offs.
Pillar III: Alternative Assets, entrepreneurship, and human capital
When deploying $100,000, investors frequently overlook the highest-returning asset class available: themselves and their earning power.
1. Investing in human capital and skill acquisition
For younger investors or mid-career professionals whose primary wealth engine is earned income rather than investment returns, deploying $5,000 to $20,000 of the $100,000 pool into advanced certifications, specialized technical training, or executive education can yield an internal rate of return (IRR) that eclipses any public market portfolio.
If acquiring a new credential allows you to negotiate a $15,000 salary increase or transition into a higher-growth industry, that human capital investment pays compounding dividends for decades.
2. Small Business acquisition and side ventures
A $100,000 equity injection, when combined with Small Business Administration (SBA) loan financing or seller financing, can be sufficient to acquire an existing, cash-flowing small business (such as an established e-commerce brand, a localized service franchise, or a business-to-business enterprise).
While entrepreneurship carries severe execution risk and operational demands, owning a profitable small business provides direct control over revenue generation and value creation that passive equity investing cannot match.
Part III: Tax Strategy and optimization
Regardless of whether your $100,000 is directed toward public markets, real estate, or alternative assets, the net return on your investment is dictated not merely by gross performance, but by tax drag.
1. Maximizing Tax-Advantaged Accounts
Before taxable brokerage accounts are utilized, investors should systematically evaluate tax-advantaged vehicles available in their jurisdiction:
Retirement Accounts (e.g., Traditional/Roth IRAs, 401(k)s, or international equivalents): Shield capital gains, dividends, and interest from annual taxation. Utilizing a Roth structure allows capital to compound tax-free and be withdrawn tax-free in retirement, a powerful vehicle for growth-oriented assets within your $100,000 portfolio.
Health Savings Accounts (HSAs): Where available, HSAs offer a "triple tax advantage" (tax-deductible contributions, tax-free growth, and tax-free withdrawals for qualified medical expenses), making them exceptional long-term wealth accumulation vehicles.
2. Tax-Loss harvesting and asset location
In taxable accounts, strategic asset placement matters. Income-generating assets (such as corporate bonds or high-dividend stocks that trigger ordinary income tax rates or dividend taxes) are best sheltered inside tax-advantaged accounts. Conversely, tax-efficient equity index funds, which generate minimal capital gains distributions until sold, are ideally suited for taxable brokerage accounts, where investors can utilize tax-loss harvesting to offset capital gains against ordinary income.
This concludes the first part of our comprehensive expert analysis. In the upcoming continuation of this guide, we will examine specific portfolio blueprint models categorized by life stage and risk tolerance, explore macro-economic hedging strategies against inflation and interest rate cycles, and outline the behavioral traps that derail six-figure investors.
Synthesizing your Core Strategy: The Multi-Pillar framework
When managing a six-figure lump sum, the single biggest mistake is treating it as a monolith. Putting all $100,000 into a single asset class, whether that is aggressive growth stocks, real estate, or conservative cash, leaves you dangerously exposed to sequence-of-returns risk, inflation, or missed opportunity cost.
Instead, elite wealth managers approach a $100,000 portfolio through a tiered allocation framework. By segmenting your capital based on liquidity needs, time horizon, and risk tolerance, you construct a resilient financial engine capable of weathering market cycles.
Pillar 1: The foundation, liquidity & capital preservation (,000 – ,000)
Before seeking alpha, you must secure your baseline. Financial stability is the prerequisite for aggressive compounding because it prevents you from being forced to liquidate long-term assets during a market downturn.
The Emergency Reserve: Allocate 3 to 6 months of essential living expenses into a high-yield savings account (HYSA) or a short-duration money market fund. With competitive yields continuing to hover around attractive levels, your cash will earn meaningful interest while remaining instantly accessible.
The Psychological Buffer: Knowing that unexpected medical bills, car repairs, or employment transitions will not derail your financial plan gives you the emotional fortitude to leave your risk assets untouched during market corrections.
Pillar 2: The Core Growth engine, Broad-Market index funds (,000 – ,000)
For the vast majority of investors, the most reliable vehicle for long-term wealth accumulation is the broad-market index fund. Rather than attempting to time the market or pick individual winning stocks, anchoring your portfolio in low-cost total market or S&P 500 ETFs ensures you capture the collective productivity of global enterprise.
The Power of Low Fees: Expense ratios matter immensely over time. Choosing funds with minimal management fees ensures that compounding returns work entirely in your favor rather than leaking out through administrative costs.
Deployment Strategy: If you are hesitant about market volatility, consider dollar-cost averaging (DCA). Splitting your core allocation into 3 to 6 equal monthly tranches removes the anxiety of putting a lump sum to work on a single day, smoothing out short-term price fluctuations.
Pillar 3: Tactical diversification & Alternative yield (,000 – ,000)
To round out a robust $100,000 strategy, allocate your remaining capital toward diversification vectors that behave differently than equities:
Tax-Advantaged Vehicles: Maximize contributions to IRAs, Roth accounts, or workplace retirement plans (such as a 401(k)) to shield your capital and dividends from annual tax drag.
Fixed Income & Real Estate Exposure: Incorporating short-term Treasury bills, investment-grade bond funds, or publicly traded Real Estate Investment Trusts (REITs) can provide a steady stream of passive income while dampening portfolio volatility.
Action plan: Bringing it all together
To help visualize how a balanced, multi-tier approach divides a $100,000 lump sum across conservative safety nets and growth drivers, examine the target asset distribution below:
Balanced $100k Allocation Strategy
Discipline over perfection
The "best" thing to invest in with $100,000 is not a single hot stock or a secret asset class, it is a repeatable, disciplined system aligned with your personal timeline. By combining an emergency cash buffer, low-cost core index funds, and smart tax management, you transform a lump sum of cash into a permanent engine for financial independence. Take your time, automate your contributions, and let the mathematics of compounding do the heavy lifting.