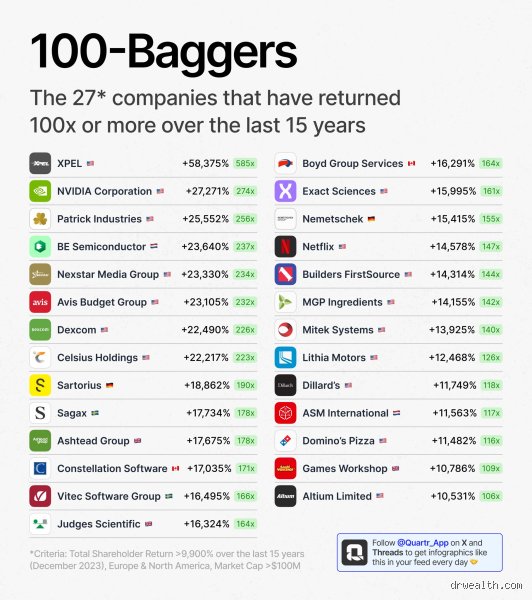
However, embarking on the search for 100x candidates demands a rigorous analytical framework rather than speculative gambling. The market is littered with speculative penny stocks and corporate flash-in-the-pans that promise astronomical gains but ultimately lead to total capital loss. True 100x potential is rarely found in mature mega-cap giants whose valuations already price in global dominance; instead, it originates in the shadows of the market, among overlooked small-cap and micro-cap innovators quietly building dominant economic moats.
This first installment of our expert analysis explores the foundational anatomy of 100x equities, dissecting the quantitative thresholds, structural prerequisites, and market psychology required to identify these rare market outliers before Wall Street takes notice.
1. The mathematics of 100x: Understanding Market Capitalization
To understand how a stock achieves a 100x return, one must first master the arithmetic of market capitalization. Market capitalization, calculated by multiplying a company's total outstanding shares by its current share price, dictates the physical ceiling and velocity of a stock's potential movement.
Market Capitalization=Share Price×Total Outstanding Shares ext{Market Capitalization} = ext{Share Price} imes ext{Total Outstanding Shares}Market Capitalization=Share Price×Total Outstanding Shares
Consider the starting point:
If a company starts with a market capitalization of $500 million, a 100x expansion brings its valuation to $50 billion, a stature comfortably within the large-cap tier, comparable to a stable, established industry leader. This is entirely feasible within a 10-to-20-year economic cycle for an exceptional disruptor.
Conversely, if a company already commands a $10 billion valuation, a 100x expansion requires reaching $1 trillion, putting it in the ultra-exclusive league of global mega-corporations like Apple, Microsoft, or NVIDIA. While trillion-dollar giants can continue to compound, multiplying a $10B enterprise by 100 requires capturing an unprecedented share of global GDP, making true 100x velocity mathematically improbable from that starting line.
Consequently, nearly all historical 100x candidates share a humble genesis: they begin as small-cap ($250M to $2B) or micro-cap (<$250M) equities. They are small enough to experience exponential growth phases yet substantial enough to possess institutional viability and audited accounting structures.
2. The core pillars of multibagger DNA
A low market cap alone is merely a recipe for bankruptcy if unaccompanied by world-class underlying fundamentals. Companies capable of compounding capital at hyper-rates for over a decade exhibit specific, non-negotiable structural traits.
A. Immeasurably large Total Addressable Market (TAM)
A small company cannot grow into a behemoth if its sandbox is too small. Potential 100x stocks operate in industries undergoing secular, paradigm-shifting transformation, such as artificial intelligence infrastructure, next-generation biotechnology, decentralized financial architecture, or global resource scarcity solutions.
Crucially, the company's current revenue must occupy only a microscopic fraction of this Total Addressable Market (often less than 1%). This leaves a multi-decade runway where the company can double its market share year after year without bumping into absolute market saturation.
B. Scalable business models with operating Leverage
True compounding requires revenue to grow faster than operational costs. Software-as-a-Service (SaaS), specialized semiconductor design, proprietary biotech platforms, and asset-light digital marketplaces exhibit exceptional operating leverage. Once the heavy initial research, development, or infrastructure costs are absorbed, every additional unit of revenue drops straight to the bottom line gross margins expand dramatically.
Avoid capital-heavy, low-margin businesses burdened by heavy manufacturing overhead or commodity price exposure unless they possess an ironclad technological monopoly.
C. The economic moat (competitive advantage)
Without a durable competitive moat, high initial growth invites aggressive competition, crushing pricing power and compressing profit margins. A 100x contender must possess at least one of Warren Buffett’s classic moats:
High Switching Costs: Once integrated into a client's workflow, replacing the product is prohibitively expensive or risky.
Network Effects: The platform becomes exponentially more valuable with every new user who joins.
Intangible Assets: Ironclad patents, proprietary algorithms, regulatory approvals, or irreplaceable brand equity.
Cost Advantages: Proprietary supply chains or manufacturing efficiencies that competitors cannot replicate.
3. Financial health and Capital efficiency
Many retail investors mistakenly equate high growth with burning cash recklessly. While early-stage disruptors may operate at a loss initially to fund rapid expansion, historical 100x winners demonstrate exceptional capital efficiency long before they reach maturity.
Return on Equity (ROE) & Return on Invested Capital (ROIC): Consistently generating ROE and ROIC well above 15% to 20% signals that management deploys retained earnings into high-yielding projects rather than burning cash on low-return vanity expansions.
Prudent Capital Structure & Low Leverage: Companies burdened by heavy debt-to-equity ratios (>0.5>0.5>0.5 or high interest-expense burdens) are exquisitely vulnerable during macroeconomic downturns or credit crunches. True multi-baggers typically fund their growth through organic operating cash flows or clean equity issuance rather than crippling debt obligations.
Reinvestment Runway: The best compounding machines do not pay dividends early in their lifecycle; instead, they reinvest 100% of their earnings back into high-ROI internal growth initiatives, compounding shareholder value exponentially.
4. Visionary, Owner-Operator management
Behind every legendary stock chart is an exceptional leadership team. In small-cap companies destined for greatness, management quality is the single most critical variable.
Investors should actively hunt for owner-operators, founders or executive teams who own a substantial percentage of the company’s common stock (ideally 10% to 30%). When executives have tens or hundreds of millions of dollars of their own net worth tied directly to the long-term share price, their incentives align flawlessly with minority shareholders. They think in decades, not quarterly earnings reports, and are immune to short-term Wall Street pressure.
Capital allocation skill separates good CEOs from legendary ones. A great leader knows precisely when to aggressively acquire complementary technologies, when to divest non-core assets, and how to allocate capital to maximize per-share intrinsic value over long horizons.
Looking ahead to part II
Identifying a potential 100x stock is only half the battle; the psychological fortitude required to hold an asset through 50% drawdowns, bear markets, and multi-year consolidation phases is what truly separates successful growth investors from the crowd. In the second part of this analysis, we will examine specific quantitative screening filters, qualitative red flags to avoid, and the portfolio management strategies necessary to capture generational wealth without incurring catastrophic ruin.
Scaling the mountain: Translating High-Conviction research into Long-Term Multi-Bagging success
Finding a stock capable of multiplying your investment by one hundred times requires looking far beyond standard large-cap equities. It demands a deliberate descent into the micro-cap and small-cap investment universe, where companies possess tiny market capitalizations, often ranging from $50 million to $500 million, giving them the crucial mathematical runway needed for exponential expansion.
However, identifying these rare corporate gems is only half the battle. The true test for any long-term investor lies in navigating the volatility, weathering multi-year consolidation phases, and understanding the precise operational inflection points that transform a speculative micro-cap into a dominant industry titan.
The anatomy of a 100x journey: Execution and inflection points
A stock does not move in a straight line from a $100 million valuation to a $10 billion valuation. The path is characterized by distinct phases of corporate evolution, each carrying unique risks and reward profiles.
1. The Validation Phase (1x to 5x)
At this initial stage, the company is usually unproven or deeply misunderstood by the broader market. Institutional ownership is low, and Wall Street equity research analysts cover the stock sparingly or not at all. The primary catalyst for moving out of this phase is product-market fit validation.
What to look for: Accelerating organic revenue growth, early signs of customer retention (such as high net revenue retention rates in software or repeat order velocity in hardware/biotech), and a management team that under-promises while consistently over-delivering.
The trap: Value traps masquerading as cheap stocks. Many micro-caps look inexpensive on a trailing basis because their core business is declining. True 100x candidates are growing their top line aggressively even if short-term earnings are suppressed by heavy reinvestment.
2. The scaling & expansion phase (5x to 25x)
Once a company proves its unit economics work on a local or regional scale, the challenge shifts from survival to replication. This is where capital allocation becomes paramount.
What to look for: Successful geographic expansion, entry into adjacent product verticals, and increasing gross margins driven by economies of scale. Crucially, look for a widening "economic moat", whether through proprietary intellectual property, high switching costs, or powerful network effects that prevent larger competitors from crushing the newcomer.
The trap: Premature dilution. Immature growth companies often rely on secondary share offerings to fund expansion, which can severely dilute existing shareholders. Look for businesses that are either self-funding through operating cash flow or raising capital at rapidly ascending share price valuations.
3. The Dominance Phase (25x to 100x+)
By the time a company reaches this tier, it is no longer an obscure micro-cap; it has graduated into a mid-cap or large-cap leader. Wall Street analysts have initiated coverage, and institutional funds are mandated to buy shares.
What to look for: Pricing power, market share dominance, and platform optionality (the ability to leverage an existing customer base to sell entirely new categories of high-margin services).
The trap: Complacency and multiple contraction. As growth inevitably decelerates from 50% year-over-year to 15%, the valuation multiple investors are willing to pay will compress. To achieve the final stretch to a 100x return, the underlying earnings power of the business must expand enough to offset any multiple contraction.
Key financial filters for High-Potential screening
While qualitative narratives about visionary founders and massive addressable markets capture the imagination, hard quantitative filters separate lottery tickets from disciplined investments. Historical multi-bagger studies highlight several non-negotiable financial characteristics:
High Return on Invested Capital (ROIC): Companies that generate high returns on the capital they reinvest into the business compound intrinsic value exponentially faster than those requiring heavy, low-return capital expenditures.
Manageable Debt Profiles: High growth requires financial flexibility. Companies burdened by excessive debt loads face severe distress when macroeconomic conditions tighten or interest rates spike, often resulting in devastating equity wipeouts.
Significant Insider Ownership: Management teams whose personal wealth is deeply tied to the performance of the common stock are far more aligned with retail shareholders. Look for founders or executive teams holding greater than 10% to 20% of the outstanding shares.
The psychological discipline of holding Multi-Baggers
Perhaps the greatest barrier to achieving a 100-fold return is not finding the right stock, but rather holding it through extreme volatility.
Along a 10-year journey to a 100x valuation, a stock will routinely experience brutal drawdowns of 40%, 50%, or even 70% driven by broader market panics, macroeconomic recessions, or temporary quarterly earnings misses. Investors who panic-sell at the first sign of trouble routinely miss the exponential compounding phase that occurs once the business model matures.
Building a portfolio of high-conviction, asymmetric growth opportunities requires treating equities not as trading cards, but as fractional ownership stakes in living, breathing enterprises. By combining rigorous fundamental research, disciplined balance-sheet screening, and an ironclad long-term temperament, investors position themselves to capture the rare market anomalies that redefine lifetime wealth generation.