The mechanical foundation of consistent capital allocation
To comprehend the true power of investing $100 dollars every month, one must first look at the mechanics of regular capital allocation paired with market growth. Unlike keeping cash in a traditional savings account—where returns struggle to outpace inflation—directing funds into a diversified portfolio introduces your money to productive assets like equities and fixed-income securities.
Consider the historical precedent set by broad market indexes, such as the S&P 500. Over extended multi-decade periods, the stock market has historically delivered an average nominal return of roughly 9% to 10% per year, or about 7% to 8% when adjusted for inflation. When you contribute $100 dollars every month, you are practicing dollar-cost averaging. This technique automatically smooths out market volatility because your fixed contribution buys more shares when prices are low and fewer shares when prices are high.
To visualize this unexpected comparison: investing monthly is much like planting a bamboo grove. For the first few years, you see very little surface activity, and it might feel like nothing is happening beneath the soil. Yet, beneath the surface, an intricate root system is expanding exponentially. By year ten, fifteen, and twenty, the upward trajectory accelerates dramatically, fueled by the relentless engine of compound interest, what Albert Einstein reportedly called the eighth wonder of the world.
Breaking down the 30-Year timeline and growth trajectories
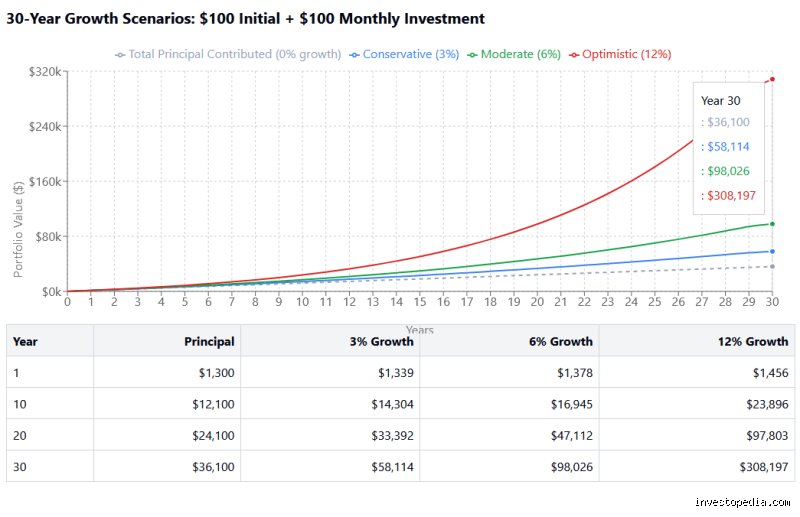
A thirty-year horizon is exceptionally long in human terms, spanning entire career phases, major life milestones, and generational shifts. To ground this in reality, let us examine how a monthly commitment of $100 dollars every month behaves over three distinct decades, breaking down the numbers into clear phases.
Phase One (Years 1–10): During the first decade, your total out-of-pocket principal contribution amounts to $12,000 (120 months multiplied by $100). In the early years, the growth is driven almost entirely by your own deposits rather than investment returns. While the portfolio value will grow, the psychological test of patience is highest here, as absolute dollar gains appear modest.
Phase Two (Years 11–20): Entering the second decade, the cumulative principal reaches $24,000. However, the portfolio balance begins to pull away from your total contributions. Because previous earnings are now generating their own returns, the compounding effect visibly kicks into gear, often surprising investors with sudden accelerations during strong market years.
Phase Three (Years 21–30): By the final decade, your total lifetime contributions stand at $36,000. Yet, this is where the curve turns parabolic. Depending on the exact annualized rate of return, ranging conservatively from 6% to an optimistic 10%, the total portfolio value can swell into six figures, transforming a modest $36,000 of personal savings into a substantial financial cushion.
For instance, looking at concrete historical milestones, an investor who began putting funds into a broad index fund in January 1996 and continued through December 2025 would have witnessed monumental economic shifts, including the dot-com bubble burst of 2000, the 2008 global financial crisis, and the 2020 pandemic volatility. Despite these harrowing market crashes, sticking rigidly to the plan of $100 dollars every month would have yielded a portfolio worth well over $110,000 to $150,000, demonstrating how time in the market consistently triumphs over timing the market.
Navigating Market volatility and Dollar-Cost averaging
While the raw mathematical projections of compound interest provide a compelling baseline, real-world investing happens in fluctuating markets rather than straight lines. Committing to a consistent monthly contribution of $100 implements a strategy known as dollar-cost averaging (DCA). Instead of attempting to time the market, which history shows is an unreliable strategy even for professionals, regular monthly investing automates your purchasing behavior.
When the stock market experiences a downturn, your $100 automatically buys more shares of a fund or stock because prices are lower. Conversely, during a bull market expansion, that same $100 buys fewer shares. Over a 30-year horizon, this systematic approach removes emotional decision-making, such as panic selling during a correction or buying out of excitement during a peak.
Practical example of Market cycles
Imagine you invest in a broad-market index fund over three consecutive months:
Month 1: Share price is $10. Your $100 buys 10 shares.
Month 2 (Market Drop): Share price falls to $5. Your $100 buys 20 shares.
Month 3 (Market Recovery): Share price rises to $20. Your $100 buys 5 shares.
In this scenario, you accumulated 35 total shares with a total investment of $300, giving you an average cost per share of roughly $8.57, while the average market price over those three months was $11.67. Over three decades, this mechanism smooths out volatility and lowers your average cost basis.
Factoring Real-World friction: Inflation, taxes, and fees
Raw future value projections often look staggering, but three primary factors reduce your purchasing power over thirty years: inflation, investment fees, and taxes. Accounting for these variables provides a realistic expectation of your net wealth.
1. The Impact of Inflation
A dollar thirty years from now will not buy what a dollar buys today. Assuming an average annual inflation rate of 2.5%, the purchasing power of your money diminishes over time. Therefore, financial analysts typically look at real returns (nominal return minus inflation). If your portfolio grows at an average nominal rate of 8% per year, your real return after a 2.5% inflation adjustment is approximately 5.5%. At a 5.5% real rate of return, your $100 monthly investment over 30 years translates to roughly $91,000 in today's purchasing power, rather than the unadjusted nominal figure of nearly $150,000.
2. Expense ratios and management fees
Choosing high-fee mutual funds can severely erode long-term gains. If a fund charges an annual management fee of 1% compared to a low-cost index fund charging 0.05%, that 0.95% difference compounds aggressively over 30 years. Minimizing investment costs to fractions of a percent preserves thousands of dollars of your lifetime returns.
3. Tax Efficiency
Where you hold your investments matters significantly. Utilizing tax-advantaged accounts, such as a Roth IRA or a traditional retirement account, protects your gains from annual dividend taxes and capital gains taxes. For instance, in a Roth IRA, your contributions are made with after-tax dollars, but all growth and withdrawals in retirement are entirely tax-free, maximizing the full power of your compounding returns.
Choosing the right Investment vehicles
Executing a $100-per-month strategy requires selecting appropriate financial instruments that match your risk tolerance and time horizon. For a 30-year timeline, investors typically focus on asset classes that offer long-term growth potential.
| Investment Vehicle | Typical Asset Focus | Risk Level | Primary Benefit |
|---|---|---|---|
| S&P 500 Index Funds | Large-cap US equities | Moderate | Instant diversification across 500 leading companies with minimal fees. |
| Total Stock Market Funds | Entire US stock market (large, mid, and small cap) | Moderate-High | Broadest possible exposure to domestic economic growth. |
| Target-Date Retirement Funds | Mix of global stocks and bonds adjusted over time | Low-Moderate | Completely hands-off asset allocation that becomes more conservative as you age. |
| Global All-Cap Equity Funds | International and domestic developed/emerging markets | Moderate-High | Geographical diversification reducing reliance on a single national economy. |
A Step-by-Step blueprint to execution
Turning a long-term financial goal into reality depends on execution discipline rather than complex financial maneuvering.
Automate Everything: Set up an automatic transfer from your checking account to your brokerage account or retirement platform every month, ideally aligned with your payday. Automation removes the friction of manual transfers.
Select a Core Holding: Direct your monthly contribution into a single, low-cost broad-market index fund or ETF. Avoid the temptation to trade individual speculative stocks, which introduces unnecessary risk and high transaction costs.
Ignore Short-Term Noise: Financial news networks and social media feeds focus on daily market swings. A 30-year strategy requires zooming out and treating market drops as standard operating conditions rather than emergencies.
Increase Contributions Over Time: As your career progresses and your income grows, increase your monthly contribution from $100 to $200, $500, or more. Scaling your savings rate accelerates your timeline to financial independence far more effectively than trying to squeeze higher percentages out of a static $100 base.
By combining disciplined automation, low-cost broad-market indexing, and a long-term mindset, a modest monthly commitment transforms into a substantial financial foundation over three decades.