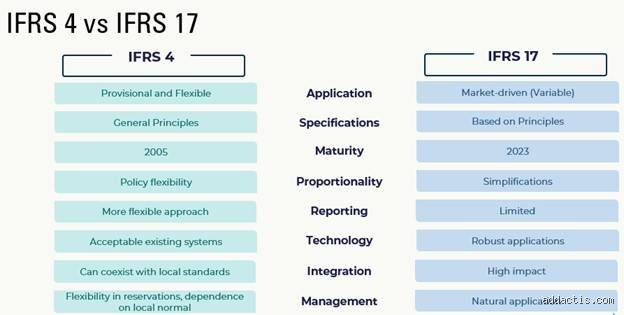
At the heart of IFRS 17 is the mandatory transition from retrospective and historical cost accounting to a current-value measurement model. Under this modern paradigm, insurance liabilities are no longer evaluated using outdated metrics; instead, they are calculated using updated, explicit estimates of future cash flows, adjusted continuously for the time value of money and the financial risks specific to those cash flows. This forward-looking orientation ensures that the financial statements of an insurance enterprise reflect real-time economic realities rather than historical artifacts. By incorporating current discount rates and risk adjustments for non-financial risk, the standard provides financial statement users with a clear and accurate reflection of an insurer’s current obligations and financial position. This alignment with contemporary economic principles bridges the historical gap between the insurance sector and other financial services industries, such as banking and investment management, where current-value reporting has long been the norm.
IFRS 17 fundamentally revolutionizes how and when insurers recognize profit. Under previous frameworks, practices varied widely, with some jurisdictions allowing companies to recognize the entirety of expected profits from a long-term contract upfront upon the collection of the initial premium. This practice distorted periodic financial reporting by masking future risks and potential operational downturns behind an initial surge of recognized income. IFRS 17 eradicates this practice through the introduction of the Contractual Service Margin (CSM). The CSM represents the unearned profit that an insurance entity will systematically recognize as it provides services over the duration of the contract. If a group of contracts is expected to be onerous—meaning that they will generate a net loss rather than a profit—the standard mandates that the loss be recognized immediately in the profit or loss statement. This mechanism prevents companies from masking unprofitable portfolios behind successful ones, offering a granular and realistic view of underlying operational profitability.
The introduction of the CSM and the strict categorization of insurance revenue also brings much-needed clarity to the composition of an insurer’s top-line growth. Historically, gross written premiums were often treated as the primary indicator of an insurer's business volume, despite the fact that premiums frequently combine investment components, deposit elements, and true insurance service fees. IFRS 17 requires the clear separation of investment components from insurance service revenue, ensuring that insurance revenue reflects only the consideration for the delivery of actual insurance services. This structural change eliminates the potential distortion caused by large inflows of investment-type funds, allowing investors to distinguish between a company’s financial investment performance and its core underwriting profitability. Consequently, financial analysts can perform meaningful, apples-to-apples comparisons between traditional insurers, asset managers, and financial conglomerates.
Achieving this level of consistency requires unprecedented operational and structural rigor from insurance organizations. IFRS 17 imposes strict grouping constraints, requiring insurers to aggregate contracts into portfolios based on similar risks and profitability profiles, and prohibiting the combination of contracts issued more than one year apart. This level of granularity demands sophisticated data management systems, advanced actuarial modeling, and seamless cross-functional collaboration between finance, actuarial, and IT departments. While the transition to IFRS 17 presents substantial implementation challenges and requires significant technological investments, its ultimate objective remains transformative: establishing a single, globally understood accounting language that enhances market confidence, rationalizes capital allocation across international borders, and provides a faithful representation of the economic substance of insurance contracts.
</body>...This brings us to the operational reality that continues to define the post-adoption landscape for global insurers. Transitioning to this framework has required organizations to bridge deep structural divides between traditionally siloed departments. Actuarial teams, who spend decades mastering stochastic modeling and risk adjustments, now find themselves working side-by-side with finance and IT units to map granular cash flows down to individual portfolios. I've seen firsthand how this convergence shatters old corporate habits, forcing companies to rebuild data architecture from the ground up just to track the elusive Contractual Service Margin (CSM). What started as a compliance mandate has evolved into a comprehensive stress-test of data maturity, exposing legacy systems that were never built to handle the rigorous demands of modern, transparent financial metrics.
Beyond the immediate mechanics of data pipelines, the standard reshapes how leadership evaluates long-term product profitability and strategic growth. Under older regimes, opaque revenue recognition often masked the true economic trajectory of a policy until decades down the line. Today, the explicit separation of investment components from insurance service revenue creates a sharper, unblinking mirror of underwriting health. While this level of disclosure can initially introduce volatility into reported earnings, causing temporary friction with market analysts accustomed to smoother, traditional metrics, it ultimately rewards disciplined underwriting. Insurers are discovering that transparency, though painful to implement, acts as a powerful catalyst for more resilient capital allocation and smarter risk management.
Viewing this accounting shift merely as a regulatory hurdle misses its profound strategic value to the global financial ecosystem. By forcing a universal language built on current values and explicit risk tracking, the framework elevates the entire sector's credibility in the eyes of investors and rating agencies. Companies that embrace this complexity not as a box-checking exercise, but as an integrated lens for decision-making, position themselves to navigate future economic turbulence with confidence. The transition path has been steep, but the destination is a more honest, comparable, and robust insurance market prepared for the realities of modern risk.