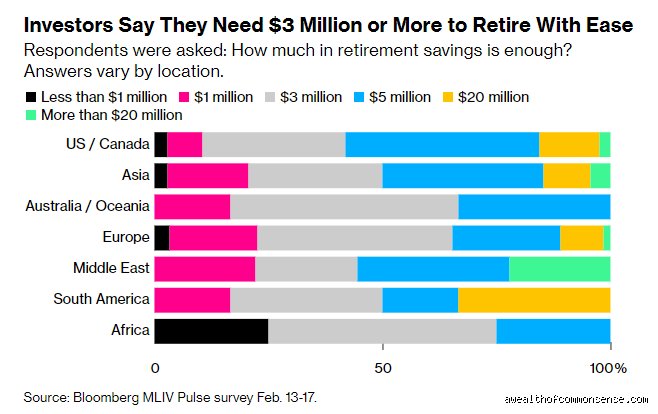
Yes, $20 million is typically enough to retire at 50, provided you manage your spending and investment strategy carefully. The key challenge is not the initial wealth but making it last for 40 to 50 years. By adopting a conservative withdrawal rate and structuring your portfolio for longevity, you can sustain a high standard of living without running out of funds.
Why the standard 4% rule may not work
Traditional retirement advice often cites the 4% rule, which assumes a 30-year retirement starting at age 65. Retiring at 50 extends your horizon by 15 years or more. This increased duration exposes your savings to greater market volatility over time. To mitigate this risk, financial planners often recommend lowering the initial withdrawal rate to between 3% and 3.5%.
| Withdrawal Rate | Annual Income | Longevity Risk |
|---|---|---|
| 3.0% | $600,000 | Extremely Low |
| 3.25% | $650,000 | Very Low |
| 3.5% | $700,000 | Low-Moderate |
| 4.0% | $800,000 | Elevated |
Generating $600,000 to $700,000 annually before taxes provides substantial flexibility. This income level covers most lifestyles without requiring aggressive growth, reducing the pressure to take on excessive investment risk in later years.
Healthcare costs before age 65
One of the most significant financial gaps for early retirees is healthcare. In the United States, Medicare coverage begins at age 65. This means you must fund 15 years of private health insurance and out-of-pocket medical expenses entirely from your portfolio. These costs can be substantial, especially if you have pre-existing conditions or require specialized care. Budgeting for this "bridge" period is essential to avoid depleting your principal prematurely.
Tax planning and account structure
How your $20 million is held matters as much as how much you have. If most of your wealth is in pre-tax accounts like traditional IRAs or 401(k)s, you may face penalties or high tax rates if you tap those funds before age 59.1/2. To manage this, consider a mix of taxable brokerage accounts, Roth IRAs, and pre-tax accounts. Strategic Roth conversions during your early retirement years can help smooth out your tax burden and reduce future required minimum distributions (RMDs).
Portfolio allocation for a 50-year horizon
Your investment mix should balance growth with stability. A common approach involves:
- 50-60% Global Equities: Provides long-term growth to keep pace with inflation.
- 15-20% Real Assets: Includes REITs or infrastructure funds to add diversification and inflation protection.
- 10-15% Cash and Bonds: Acts as a buffer to cover living expenses during market downturns, preventing you from selling stocks at a loss.
This structure helps protect your capital during volatile periods while still allowing for growth. It reduces the risk of "sequence-of-returns risk," where poor market performance early in retirement has a disproportionate negative impact on your portfolio's longevity.
Lifestyle management
Spending habits play a critical role. Early retirement often coincides with peak travel and hobby years, which can drive up expenses. However, unchecked lifestyle inflation can erode your principal. It is wise to establish a spending baseline that feels comfortable but sustainable. Adjusting expenses as you age, particularly during the "slow-go" and "no-go" years, helps preserve wealth for later decades when healthcare costs typically rise.