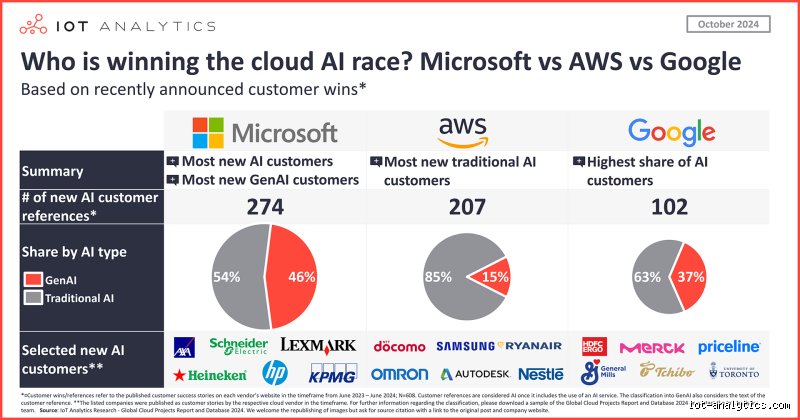
The artificial intelligence revolution has long outgrown its origins as a niche academic pursuit, transforming into a high-stakes, multi-trillion-dollar geopolitical and commercial competition. As the landscape matures, answering the question of who is leading the AI race requires looking beyond simple metrics like model parameters or hype. Instead, leadership must be evaluated across multiple dimensions: foundational model capabilities, compute hardware infrastructure, sovereign state strategies, and enterprise application integration.
1. The Corporate Frontier Labs: OpenAI, Anthropic, and Google DeepMind
At the bleeding edge of artificial intelligence research, a small cluster of private labs and tech giants command the primary development of frontier models.
OpenAI and Anthropic: Pushing aggressive multi-billion-dollar commercial growth and scaling targets, OpenAI (creators of the GPT series) and Anthropic (developers of the Claude ecosystem) remain locked in a neck-and-neck commercial and technical rivalry.
Both labs continue to push the boundaries of reasoning speed, multi-modality, and context windows, commanding staggering valuations and unprecedented commercial revenue run-rates. Google DeepMind: Backed by Alphabet's immense computing resources and decades of pioneering research history, Google DeepMind remains a formidable superpower. Through the iterative advancement of the Gemini architecture, deep cloud integration (Vertex AI), and deep consumer integration across Android, Search, and Workspace, Google leverages a massive distribution network that few startups can match.
Other Major Players: Meta has heavily disrupted the proprietary model ecosystem by championing powerful open-weight releases (such as the Llama series), democratizing advanced capabilities for developers worldwide. Meanwhile, specialized contenders like xAI (with the Grok model family) and France-based Mistral AI continue to carve out massive enterprise footprints through regional alignment and optimized efficiencies.
2. The Hardware Backbone: The Silicon Monopoly
No discussion of AI leadership is complete without examining the underlying physical infrastructure. The software intelligence driving modern models cannot exist without massive training clusters powered by specialized semiconductors.
Nvidia’s Dominance: Nvidia commands an overwhelming share of the AI training and inference market. Through architectures like the H100 and the newer Blackwell lineup, Nvidia has acted as the literal picks-and-shovels provider for the entire gold rush, propelling its market capitalization to historic heights.
The Rise of Custom Silicon: To mitigate dependency and manage astronomical operating costs, major cloud hyperscalers—including Amazon Web Services (Trainium/Inferentia), Microsoft (Maia), and Google (TPUs)—have aggressively designed and deployed their own proprietary AI accelerators. Alternative hardware players like AMD (with its MI series) are also expanding their foothold to capture secondary market share.
3. Geopolitical Superpowers: The US-China Duopoly
On a macro level, global analysis by organizations like Stanford University and specialized geopolitical indexes confirms a distinct two-horse race between the United States and China.
The United States: The U.S. firmly leads in total private capital investment, absolute density of premier data centers, and the creation of frontier consumer-facing foundation models.
American tech ecosystems continue to attract massive venture backing, though structural bottlenecks around domestic tech talent pipelines and regulatory compliance remain points of ongoing friction. China: China has demonstrated exceptional resilience and output, particularly following strategic export controls on Western hardware. Chinese labs—propelled by state-backed supercomputing centers and a dominant share of global AI patent grants and academic publications—have closed the performance gap with Western models to a razor-thin margin.
Furthermore, China has emerged as a powerhouse for open-weight model deployment and rapid industrial robotics integration.
This concludes Part 1 of this analysis. Subsequent sections will explore the explosive growth of specialized software tooling, enterprise agentic workflows, and the emerging regional leaders shifting the global balance of power.
This video provides a helpful overview of the top technology companies leading the market capitalization race driven by artificial intelligence advancements.
(We stare into glowing rectangles for hours, hunting ghosts.) Let's be clear: our screens own us.
We traded physical friction for frictionless isolation, expecting a utopia. Yet, reality intruded. Why do we keep scrolling? The problem is simple. We mistake connectivity for community.
The Architecture of Noise
Notifications chime constantly.
As a result: attention spans shatter into dust. We consume headlines like snacks.
Frictionless Illusion
Algorithms feed your deepest insecurities.
The issue remains that rebellion feels exhausting. You swipe anyway.
Silent Consensus
Everyone pretends to be fine.
Which explains the hollow feeling in your chest. We curate perfection.
The Human Cost
Authenticity died quietly in a server rack.
Because we worship speed above all else. In short, we built a cage and called it freedom.