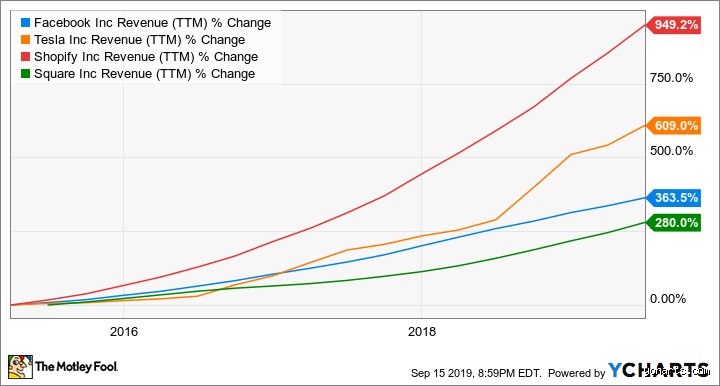
In global equity markets, few endeavors captivate institutional and retail investors alike quite as intensely as identifying shares that compound value at breakneck speeds. High-growth shares—often referred to as growth stocks—represent companies expanding their top line, cash flows, and market presence significantly faster than the broader economy or their industry benchmark.
To build a rigorous framework for identifying fast-growing equities, investors must analyze three foundational pillars: structural industry tailwinds, unit economics paired with scalable business models, and explicit quantitative metrics.
1. Structural Industry Tailwinds and Market Horizons
A company cannot sustain rapid growth in a stagnant environment. Shares that experience sustained, compounding expansion are almost universally positioned at the intersection of powerful secular tailwinds and expanding market horizons.
Total Addressable Market (TAM) & Market Expansion
The upper bound of any firm’s growth velocity is determined by its Total Addressable Market (TAM). A dominant firm capturing 80% of a $1 billion niche market has far less room to run than an emerging player capturing 2% of an expanding $500 billion sector. Fast-growing shares typically exhibit one of two TAM dynamics:
Market Creation / Secular Shift: The company creates an entirely new category or benefits from a technological paradigm shift (e.g., enterprise cloud migration, artificial intelligence hardware, advanced biotechnology platforms).
Market Disruption: The company leverages a technological or operational advantage to aggressively dismantle traditional incumbents within a massive existing sector.
 [ Total Addressable Market (TAM) ]
 │
 ┌───────────────┴───────────────┐
 ▼ ▼
 [ Market Creation / Shift ] [ Industry Disruption ]
 • Secular Trend Alignment • Superior Cost / Experience
 • Expanding Macro Runway • Rapid Market Share Gain
 └───────────────┬───────────────┘
 ▼
 [ High Top-Line Velocity ]
Secular Acceleration vs. Cyclical Rebound
Distinguishing true structural growth from cyclical recovery is critical. Semiconductor design firms supplying infrastructure for long-term automation represent secular growth. Conversely, energy producers or commodity miners experiencing brief earnings surges due to temporary supply shocks represent cyclical fluctuations. Shares that compound rapidly over multi-year horizons are fueled by secular demand that persists regardless of short-term macroeconomic hiccups.
2. Scalable Business Models and Economic Moats
High revenue potential alone does not guarantee that a company's share price will grow rapidly. The underlying business engine must be structurally capable of handling exponential volume without incurring proportional cost increases.
Zero-Marginal-Cost Scalability
The fastest-growing equity stories of the modern era consistently share a common trait: high operational leverage. Software-as-a-Service (SaaS), platform ecosystems, and proprietary digital IP can often onboard millions of additional users at near-zero incremental marginal cost.
High Operating Leverage: When revenues surge while fixed costs remain stable, operating margins expand rapidly. This creates a compounding effect where net income grows substantially faster than top-line sales.
Capital Efficiency: High-growth leaders maintain high Return on Invested Capital (ROIC) and Return on Equity (ROE), generating substantial internal funds to reinvest into sales, marketing, and research & development without diluting shareholders or taking on toxic leverage.
Economic Moats That Protect Expansion
A fast-growing firm inevitably attracts fierce competition. Without a durable competitive advantage (an economic moat), rapid profit margins quickly erode as rivals copy products or undercut prices.
3. Quantitative Criteria: Identifying Growth on the Balance Sheet
Investors looking for shares with rapid growth potential rely on quantitative screens to separate genuine market leaders from speculative traps.
The Core Growth Metrics Checklist
Accelerating Top-Line Growth (Revenue): Look for continuous year-over-year revenue expansion exceeding 20–25% annually, with ideal setups showing quarter-over-quarter growth acceleration.
Earnings Per Share (EPS) Trajectory: High-growth shares often transition rapidly from unprofitable to profitable. Sustained double-digit EPS expansion demonstrates operational execution.
Net Revenue Retention (NRR): For subscription and platform models, an NRR above 120% indicates that existing customers spend 20% more each year, providing growth even before accounting for new customer acquisition.
Price/Earnings-to-Growth (PEG) Balance: Standard P/E ratios often fail to evaluate fast-growing companies accurately. The PEG ratio divides the Price-to-Earnings ratio by the expected annual EPS growth rate. A PEG near or below 1.0–1.5 suggests that market pricing still leaves room for growth-driven upside.
4. Key Metrics Comparison Matrix
Evaluating potential growth investments requires comparing financial criteria across maturity stages:
(End of Part 1. Part 2 will address tactical timing, valuation traps, macroeconomic risk factors, and building a high-growth equity portfolio.)
Common Mistakes and Misconceptions About Fast-Growing Shares
Navigating high-growth investing requires distinguishing between true commercial momentum and unsustainable market noise. Investors frequently fall into psychological and analytical traps when searching for the next high-flyer.
Confusing Revenue Growth with Value Creation
A company can rapidly expand its top line simply by overspending on customer acquisition or offering products below cost. Unprofitable growth that lacks a path to scale operating leverage destroys capital over time. True high-growth shares maintain healthy gross margins, showing that customers value the underlying product enough to pay a premium. Without strong margin structure, expanding revenue merely scales losses rather than long-term equity value.
Falling for the "Cheap Stock" Fallacy
Investors often mistake a low share price ($2 per share versus $200 per share) for a bargain, or assume a beaten-down company is poised for a rapid rebound. True growth drivers—such as secular tailwinds, proprietary technology, and network effects—rarely trade at deep value multiples during their active expansion phase. Buying low-quality businesses solely because their price appears "cheap" frequently traps capital in declining industries or structurally impaired operations.
Overestimating TAM Without Assessing Moats
A massive Total Addressable Market (TAM) attracts intense competition. Pitching an industry worth hundreds of billions of dollars is common, but growth shares succeed only if they possess defensible competitive moats—such as high switching costs, brand power, or proprietary IP. Lacking these barriers, earlyCommon Mistakes and Misconceptions When Hunting for Fast-Growing Stocks
Identifying high-growth equities requires separating sustainable business performance from market noise. Investors frequently confuse price momentum with underlying enterprise expansion, leading to critical capital allocation errors.
Confusing Revenue Growth with Scalable Profitability
A rapid increase in top-line revenue often masks underlying structural defects. High top-line expansion driven by aggressive customer acquisition costs, unsustainable discounts, or unprofitable product lines does not translate into long-term enterprise value.
When evaluating high-growth candidates, examine unit economics alongside top-line figures. A company expanding revenue at 40% annually while its sales and marketing expenses grow at 60% is eroding capital efficiency. Sustainable growth occurs when operating leverage takes hold, allowing operating income to grow faster than total revenues once fixed costs are covered.
Overreliance on Historical Performance Metrics
Past financial performance reflects historical market conditions, competitive landscapes, and capital efficiency—none of which are guaranteed to persist. Assuming a stock that grew its earnings by 30% per year over the last three years will maintain that trajectory is a common source of value destruction.
Companies face natural scaling headwind, often referred to as the law of large numbers. As an enterprise grows, maintaining high percentage growth rates requires exponentially larger absolute gains. Evaluating growth potential requires analyzing forward-looking total addressable market (TAM) penetration rather than trailing revenue figures.
Overpaying for Hype and Ignoring Valuations
The fastest-growing companies frequently trade at elevated valuation multiples, such as high Price-to-Sales (P/S) or Enterprise Value-to-EBITDA (EV/EBITDA) ratios. While market leaders command premiums, paying excessive multiples leaves no margin of safety.
If valuation multiples compress due to a minor quarterly guidance miss or broader macroeconomic shifts, share prices can plummet even while the underlying business continues to expand. Growth strategy must balance fundamental operational growth against the entry multiple paid.
While mainstream analysis focuses on headline market trends and immediate earnings beats, expert stock selection hinges on structural efficiency metrics that signal hyper-growth before it manifests on primary balance sheets.
Identifying Structural Operating Leverage Early
Operating leverage measures how revenue growth translates into operating income expansion. Companies with high fixed costs and low variable costs experience dramatic margin expansion once revenue passes the breakeven threshold.
Low Revenue Phase: High Fixed Costs -> Compressed Margins
Breakeven Point: Fixed Costs Covered
High Revenue Phase: Incremental Revenue -> Exponential Margin Expansion
To identify high-growth candidates before the broader market prices them in, track the delta between incremental gross profit and incremental operating expenses over successive quarters:
When this ratio exceeds 1.5 consistently, the business is demonstrating high scalability, signaling that future revenue gains will flow straight to the bottom line.
Evaluating R&D Yield and Capital Reinvestment
High-growth companies rarely payout dividends; instead, they reinvest capital into Research & Development (R&D) and capital expenditures (CapEx). However, raw expenditure does not guarantee results. Evaluating the Return on Invested Capital (ROIC) relative to the Weighted Average Cost of Capital (WACC) reveals whether reinvestment generates real enterprise value.
Look for a high R&D Yield, defined as the percentage of current revenues derived from products or features launched within the past three to five years. Companies that achieve high output per dollar spent on development maintain competitive moats, allowing them to capture market share rapidly while defending pricing power.
What financial indicators best signal that a stock is about to enter a high-growth phase?
Key indicators include accelerating quarter-over-quarter revenue growth, expanding gross margins, and an increasing ROIC. Watch for operational metrics like customer acquisition cost (CAC) reduction relative to lifetime value (LTV), alongside inventory turnover improvements for product-based models.
How does company size impact potential growth velocity?
Small-cap and mid-cap companies generally possess greater operational scope for high percentage growth compared to mega-cap enterprises. Due to the law of large numbers, a company with $100 million in annual revenue finds it significantly easier to double its business than a company generating $100 billion.
Can dividend-paying stocks qualify as fast-growing stocks?
While fast-growing companies typically reinvest all earnings into operational expansion rather than paying dividends, mature tech and healthcare enterprises can exhibit both growth and dividend increases. However, pure high-growth stocks generally prioritize capital reinvestment over cash distributions.
What role do macroeconomic environments play in stock growth rates?
Interest rates, inflation, and liquidity directly affect high-growth stocks. Low interest rate environments lower the discount rate applied to future earnings, boosting valuations for growth equities. Conversely, rising interest rates increase capital costs and compress valuation multiples, making execution quality far more critical.