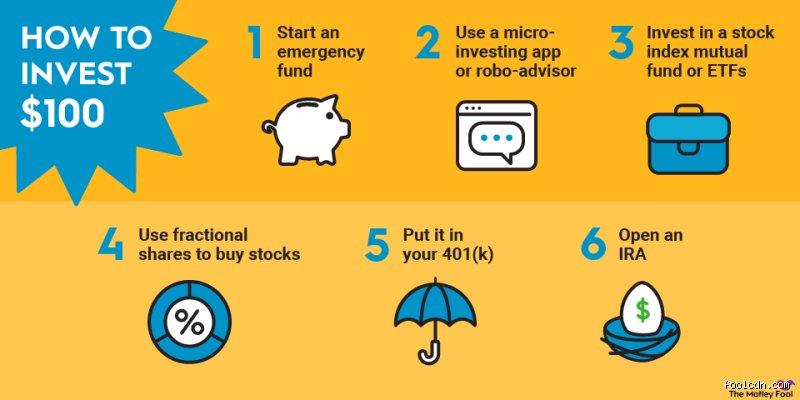
Decoding the myth: Can You really build wealth starting with just a single Benjamin?
Today, that landscape has shifted fundamentally. With the rise of zero-commission digital brokerages, automated micro-investing platforms, and the revolutionary mechanics of fractional shares, the barriers to entry have virtually vanished. A single $100 bill is no longer a trivial sum dismissed by financial institutions; it is an entirely viable, practical, and psychologically powerful launching pad.
However, answering the question—Is $100 enough to start investing in stocks?—requires looking past a simple "yes." While technically you can start with a single dollar, understanding how that $100 behaves, what it can realistically achieve, and how it serves as a foundation for lifelong financial habits is what separates successful investors from frustrated speculators.
The Mechanics of Small-Capital investing: How fractional shares changed everything
To understand why $100 is enough, you first need to understand how modern stock purchasing works. Historically, if a juggernaut company like Apple, Microsoft, or Amazon traded at $300 or $400 per share, having a $100 bill meant you couldn't buy a single piece of the pie. You were forced to look for cheap "penny stocks", which are frequently volatile, speculative, and risky, or wait months just to save enough capital for one share of a stable company.
Fractional shares completely eliminated this friction. Modern brokerages allow you to purchase slices of a single share rather than requiring the whole unit.
If a premier stock or exchange-traded fund (ETF) costs $250 per share, your $100 will comfortably buy you 0.4 shares.
You receive the exact same percentage-based gains or losses as someone holding a full share.
If the stock climbs 10%, your 0.4 shares grow in value by 10% just like theirs.
This breakthrough means your $100 is not relegated to second-tier investments. You can instantly diversify across top-tier market segments, owning a piece of the entire S&P 500 or blue-chip corporations that form the backbone of the global economy.
The psychological and educational dividend
While a one-time injection of $100 will not instantly buy you financial freedom or fund a luxury retirement villa on its own, its greatest immediate return is educational and psychological.
Most beginners freeze up. They read books, watch tutorials, and analyze charts, but they never actually pull the trigger because of "analysis paralysis" or the fear of losing money. Risking $100, an amount that stings slightly if lost entirely, but will not ruin your livelihood, acts as an incredible psychological vaccine.
Learning to Handle Market Volatility: When you have skin in the game, your relationship with market news changes. Red days on the ticker stop being abstract concepts and become visceral experiences. Learning how you personally react when your portfolio dips 5% or 10% is a critical rite of passage. It teaches you emotional discipline before you are managing thousands or tens of thousands of dollars.
Mastering the Platform Mechanics: Opening a brokerage account, funding it via a bank transfer, navigating order types (market orders vs. limit orders), and tracking dividends look intimidating on paper. Doing it once with $100 builds muscle memory.
Shifting from Consumer to Owner: Putting money into the stock market fundamentally alters your worldview. Instead of just buying products from a brand, you start viewing yourself as a fractional owner of the enterprise.
The power of the habit: From 0 once to 0 monthly
To view $100 as a static event is to miss the entire engine of wealth accumulation. The true magic of starting with $100 is that it forces you across the psychological starting line. Once the account is open, the machinery is in place to transform a one-time experiment into a powerful systematic habit.
Consider the math of consistency. If you invest $100 once and never touch it again, assuming a historical average annualized stock market return of roughly 8% to 10%, it will grow into a modest sum over decades. But if you treat that initial $100 as the anchor for a monthly recurring contribution of $100, the trajectory changes dramatically:
After 10 years: Consistent monthly additions begin building a robust mid-four-figure cushion.
After 20 to 30 years: Thanks to the compounding effect, earning returns on your returns, that steady cadence snowballs into a substantial asset base capable of supplementing major life goals or retirement.
The $100 bill is the catalyst; consistency is the fuel. Without the catalyst, the fuel is never poured.
Essential guardrails: What NOT to Do with Your first 0
Because $100 is a limited amount of capital, beginner mistakes can wipe it out instantly. If you want your starting capital to survive and teach you the right lessons, avoid these major traps:
Do Not Gamble on Penny Stocks or Meme Hype: Tempted by stories of penny stocks multiplying overnight? Treat that temptation with extreme caution. Low-priced, highly speculative stocks are frequently subject to severe manipulation, sudden crashes, and high trading fees relative to your small balance.
Do Not Ignore Fees: If a platform charges a $5 trading commission to buy or sell, a $100 investment instantly loses 5% of its value before it even enters the market. Stick strictly to zero-commission platforms and low-cost index funds or ETFs.
Do Not Invest Money You Need Tomorrow: Never invest your last remaining cash. If that $100 represents your grocery money or your only emergency buffer, keep it in a safe savings account instead. Invest only surplus funds that you can comfortably leave untouched for years.
Understanding the Stock Market This video provides a helpful visual walkthrough of how beginner investors can deploy small starting amounts into sensible, long-term assets like index funds and ETFs.
The Mechanics of growth: How 0 compounds over time
When starting with a modest capital base, your primary advantage is not the magnitude of your initial deposit, but the runway of time. Understanding the mathematics of compounding is essential for any retail investor, especially when managing a compact $100 starting budget.
The Rule of 72 in Action
To grasp how a single $100 bill, or a monthly $100 contribution, transforms over decades, financial planners often rely on the Rule of 72. By dividing 72 by your expected annual rate of return, you can estimate how many years it will take for your investment principal to double.
Assuming a historical stock market average return of roughly 8% to 10% annually (adjusted for inflation or looking at broad-market index trends):
At an 8% return, your money doubles approximately every 9 years (72÷8=972 \div 8 = 972÷8=9).
Over a 36-year horizon, an initial lump sum of $100 would theoretically double four times: from $100 to $200, to $400, to $800, and finally to $1,600.
While $1,600 might not sound life-changing on its own, it illustrates a fundamental principle: compounding requires momentum. The true power of a $100 start is not letting that single bill sit in isolation, but using it as the psychological and mechanical catalyst to build a consistent habit of regular contributions (dollar-cost averaging).
Dollar-Cost averaging (DCA) vs. Lump sums
When you only have $100, the debate between lump-sum investing and dollar-cost averaging is largely answered for you: you are deploying your capital all at once. However, your strategy moving forward will determine your success.
Dollar-cost averaging involves investing a fixed amount of money at regular intervals, such as $100 on the first of every month, regardless of whether the market is up or down.
Behavioral Benefits: DCA removes the emotional paralysis of trying to "time the market." Beginners often wait for the "perfect dip," letting cash sit idle while inflation erodes its purchasing power.
Mathematical Mechanics: When asset prices are high, your $100 buys fewer shares. When a market correction occurs and prices drop, your $100 automatically buys more shares. Over long periods, this lowers your average cost per share.
Crafting Your initial 0 portfolio strategy
With $100, you cannot realistically build a diversified portfolio of 20 individual stocks. Transaction friction, minimum purchase requirements, and the sheer lack of capital make individual stock-picking inefficient and dangerously undiversified. Instead, your strategy should focus on maximum diversification with minimum friction.
Strategy 1: The single Broad-Market ETF (the simplest path)
For most beginners starting with $100, the most mathematically sound approach is allocating the entire sum into a single, low-cost broad-market Exchange-Traded Fund (ETF) that tracks a major index, such as the S&P 500 or a total world stock index.
Why it works: By purchasing one share of an S&P 500 ETF, your $100 is instantly distributed across the 500 largest publicly traded companies in the United States, spanning technology, healthcare, finance, consumer goods, and energy.
Risk Mitigation: If a single company in that index goes bankrupt or faces severe scandal, your portfolio absorbs a negligible fraction of the impact because your risk is pooled.
Strategy 2: The fractional share hybrid
If your chosen brokerage supports fractional shares and offers zero commissions, you can split your $100 across two or three distinct assets to target specific goals. For example:
$60 in a Broad U.S. Market ETF (Core growth)
$20 in an International Developed Markets ETF (Global diversification)
$20 in a Sector-Specific or Thematic ETF (Optional satellite allocation, such as technology or clean energy)
Note: Keeping things simple is usually superior for small accounts. Avoid over-diversifying a tiny portfolio into ten different $10 holdings, as managing micro-allocations adds unnecessary cognitive load.
Navigating Fees, taxes, and hidden traps
When investing small amounts of money, structural costs can quietly devour your returns if you aren't vigilant. A $5 transaction fee on a $100 investment represents an immediate 5% loss before the market even moves a fraction of a percent.
1. Eliminating Commissions
Ensure your brokerage operates on a zero-commission model for stocks and ETFs. Fortunately, nearly all major modern digital brokerages have eliminated standard trading commissions, making micro-investing viable. Always double-check the fee schedule before funding an account.
2. Expense Ratios
Every ETF charges a small annual management fee known as an expense ratio, expressed as a percentage of your assets under management.
Look for funds with expense ratios under 0.10% (e.g., 0.05% means you pay 5 cents annually for every $100 invested).
Avoid actively managed mutual funds or niche thematic ETFs with high expense ratios (0.50% to 1.5% or higher), as high fees severely erode long-term compounding.
3. Tax Efficiency
Depending on your jurisdiction and age, look into tax-advantaged accounts (such as an IRA in the United States or equivalent structures globally). While starting with $100 means capital gains taxes will initially be minimal, developing the habit of utilizing tax-sheltered accounts early protects your future gains as your portfolio scales.
Psychological hurdles: Overcoming the "Small Money" mindset
The biggest barrier to investing $100 isn't mathematical, it's psychological. Many beginners fall into cognitive traps that paralyze their financial growth.
The "Too Small to Matter" Fallacy: It is easy to look at $100 and think, "What's the point? Even if it doubles, it's only another hundred dollars." This mindset ignores the compounding timeline. Every legendary investor started with their first small deposit. The primary goal of the initial $100 is not immediate wealth generation; it is behavioral conditioning. It teaches you how to open an account, link a bank transfer, execute a trade, and emotionally tolerate market volatility without panicking.
The Trading Illusion: Because $100 feels insignificant, beginners are frequently tempted to treat it like "play money," gambling on high-risk penny stocks, speculative cryptocurrencies, or leveraged options contracts hoping for a quick 10x return. Treat your first $100 with the exact same seriousness and discipline you would apply to a $100,000 retirement portfolio. Speculation destroys capital; disciplined investing builds it.
The blueprint: Your Step-by-Step action plan
If you currently have a crisp $100 bill or a digital balance ready to deploy, execute this roadmap to begin your investing journey today:
Select a Reputable Brokerage: Choose a regulated, low-cost platform that supports fractional shares and zero-fee ETF trading.
Fund Your Account: Transfer your $100. Set up a recurring monthly transfer, even if it's just $10 or $20 more, to automate your habit.
Choose Your Asset: Select a globally diversified, low-cost index ETF.
Execute the Trade: Place your market or limit order.
Close the App and Wait: Resist the urge to check your portfolio value daily. Market fluctuations over days and weeks are noise; multi-year trends are signal.
Final Verdict
Is $100 enough to start investing in stocks? Unequivocally, yes.
The financial markets are no longer gated behind high institutional minimums or expensive broker floor fees. With fractional shares, zero commissions, and instant digital access, $100 is more than enough to claim your stake in the global economy. The most critical variable is not the size of your first deposit, it is the decision to start.