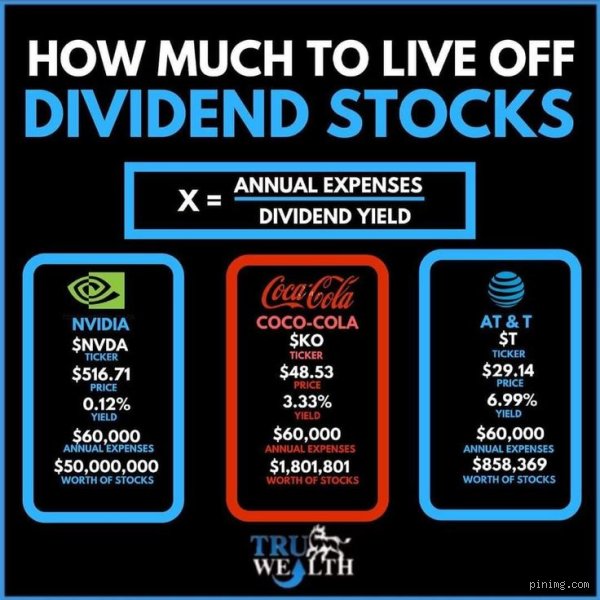
At its core, a dividend payment represents a direct share of corporate profits distributed to investors. When mature, stable companies generate substantial free cash flow beyond what is necessary to reinvest in research, development, or physical expansion, they return that capital to their owners. For the income-focused investor, this mechanism replaces the traditional paycheck. Instead of relying on a traditional employer, your portfolio of businesses works on your behalf, depositing cash directly into your brokerage account every single month or quarter. Understanding the mechanics of how these cash distributions operate is essential for anyone aiming to replace their earned income with portfolio yields. The journey begins by evaluating the reliability of corporate earnings and identifying companies equipped with enduring competitive advantages that protect their profit margins across decades.
Evaluating potential income holdings requires looking far beyond a high headline yield. Novice investors frequently make the critical mistake of chasing the absolute highest yields available on the market, unaware that an abnormally high yield often signals a distressed business or a looming dividend cut. When a company's stock price plummets due to fundamental operational flaws, its historical dividend yield automatically spikes on paper. Purchasing these value traps can quickly lead to decimated capital and eliminated distributions. A truly resilient dividend portfolio prioritizes companies with manageable payout ratios, consistent earnings growth, and proven histories of navigating economic recessions without interrupting their payment schedules. Examining metrics such as free cash flow coverage, debt-to-equity ratios, and historical payout growth provides a clearer picture of whether a company can maintain and grow its distribution over the long run.
The concept of dividend growth introduces another vital dimension to a successful income strategy. Inflation steadily erodes the purchasing power of fixed cash flows over time, meaning a static dividend that looks sufficient today might fall short of covering basic living expenses ten or twenty years down the line. To combat this reality, successful income investors target companies that routinely increase their dividend payments year after year. Corporations boasting decades of consecutive annual increases, frequently referred to as Dividend Aristocrats or Dividend Kings, demonstrate exceptional operational resilience and shareholder alignment. When a business consistently grows its payout at a rate that outpaces inflation, your personal stream of passive income expands organically, ensuring that your lifestyle remains fully protected against the rising cost of living.
Sector selection plays a monumental role in shaping the stability and yield of an income-oriented portfolio. Certain industries naturally lend themselves to steady cash generation due to the essential nature of their products and services. Regulated electric and gas utilities, major consumer staples conglomerates, healthcare giants, and select real estate investment trusts form the traditional backbone of any serious dividend strategy. These sectors benefit from steady, predictable demand that remains largely insulated from economic shocks. People will continue to purchase household goods, heat their homes, take necessary medications, and pay rent regardless of broader macroeconomic conditions. By anchoring your portfolio in these foundational sectors, you establish a reliable baseline of cash flow capable of weathering severe market corrections and financial panics.
Diversification across industries and individual equities acts as an essential safeguard against unexpected corporate headwinds. Even the most established, dominant enterprises can occasionally face unforeseen regulatory challenges, technological disruptions, or management missteps that threaten their business models. Spreading capital across dozens of distinct companies spanning multiple defensive sectors ensures that the temporary stumble of a single enterprise will not derail your entire financial ecosystem. Balancing ultra-reliable lower-yield growers with selective higher-yield opportunities optimizes the portfolio's overall cash production while preserving long-term capital appreciation potential. This balanced architecture provides the psychological comfort necessary to stay invested during turbulent market cycles without panicking.
The mathematical reality of living off dividends requires accumulating a substantial asset base before total financial independence becomes feasible. Determining your target portfolio size involves calculating your annual living expenses and dividing that figure by your portfolio's aggregate dividend yield. For instance, achieving an annual passive income stream of forty thousand dollars from a portfolio yielding an average of four percent requires a total invested capital base of one million dollars. Recognizing this mathematical framework helps investors set realistic milestones and emphasizes the importance of a multi-year accumulation phase characterized by aggressive saving, disciplined capital allocation, and the continuous reinvestment of early dividend distributions to accelerate the compounding process.
Reinvesting dividends during the accumulation phase unleashes the full power of financial compounding. In the early stages of building an income portfolio, every cash distribution received is automatically used to purchase additional shares of the underlying stock or fund. These newly acquired shares subsequently generate their own dividends, which are then added back into the pool to purchase even more shares. This self-sustaining loop creates an exponential growth curve over long investment horizons, dramatically expanding your share count and boosting your ultimate income capacity long before you actually turn off the drip and begin collecting cash for living expenses. Mastering this accumulation cycle transforms ordinary savers into independent wealth builders capable of sustaining themselves entirely through market returns.
Strategic sector allocation and defensive moats
Building a sustainable dividend income stream requires examining the foundational sectors that consistently return cash to shareholders through economic cycles. Consumer staples, regulated utilities, and healthcare giants possess robust economic moats, characterized by entrenched brand loyalty, high switching costs, and inelastic demand. These structural advantages allow businesses to maintain pricing power during inflationary periods, directly protecting and growing their distributions over multi-decade horizons.
A disciplined equity selection framework prioritizes enterprises with manageable debt profiles, stable free cash flow conversion rates, and prudent capital allocation policies. When evaluating potential holdings, investors analyze the interest coverage ratio, ensuring operating earnings comfortably exceed debt servicing obligations. Capital expenditure requirements must leave ample liquidity to fund ongoing operations and incremental dividend increases without resorting to external debt financing.
Dividend growth versus initial yield
A common pitfall in income investing is chasing high current yields without assessing the underlying business trajectory. A stock yielding eight percent with a stagnant or declining payout often signals financial distress, commonly known as a value trap. Conversely, a company offering a modest initial yield of two and a half percent backed by a twelve percent compound annual growth rate frequently outpaces high-yield alternatives within five to seven years due to the compounding effect of regular payout increases.
The dividend growth rate acts as a natural hedge against purchasing power erosion. When management consistently increases distributions at a rate exceeding core inflation, the yield on cost expands substantially over time. This dynamic transforms a modest initial cash flow into a robust income stream, securing long-term purchasing power parity without requiring portfolio liquidation.
Constructing a diversified income portfolio
Risk mitigation within an income-focused portfolio relies on cross-sector diversification and rigorous position sizing guidelines. Concentrating capital exclusively within traditional high-yield sectors, such as telecommunications or domestic banking, exposes the portfolio to regulatory shifts and structural sector headwinds. Balancing defensive stalwarts with selective exposure to technology and industrial leaders provides exposure to structural secular growth trends while maintaining income stability.
Reinvestment mechanics and compound growth
During the accumulation phase, utilizing a dividend reinvestment plan allows shareholders to acquire additional fractional shares automatically without incurring transaction fees. This continuous compounding mechanism accelerates portfolio growth significantly during market downturns, as fixed cash distributions purchase a greater number of shares at discounted valuations. Transitioning from accumulation to the distribution phase involves redirecting these cash flows into a designated settlement account to fund living expenses, while maintaining the core principal intact.
Tax efficiency and account architecture
Optimizing the net cash flow generated by an equity portfolio requires strategic asset location across taxable and tax-advantaged account structures. Qualified dividends benefit from preferential tax rates in standard taxable brokerage accounts, reducing the drag of annual tax liabilities on cash flow generation. Conversely, holding higher-turnover or non-qualified distribution vehicles within tax-deferred or tax-exempt structures preserves capital efficiency over long accumulation horizons.
Minimizing transaction costs and avoiding unnecessary capital gains realizations further enhances net portfolio performance. Long-term holding periods align with the philosophy of partnering with durable, cash-generative enterprises, reducing friction and preserving capital for continuous compounding and distribution.