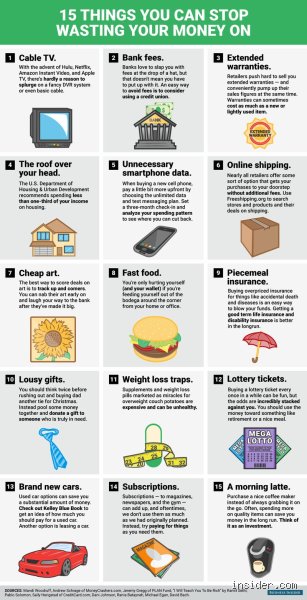
Money rarely leaves a bank account in a dramatic, catastrophic fashion. People rarely wake up to find their life savings vanished because of a single, catastrophic error in judgment. Instead, financial health bleeds out slowly, drop by drop, through a series of normalized, socially reinforced expenditures that slip beneath our cognitive radar. When financial experts analyze household budgets, they consistently find that the greatest threat to long-term wealth is not high taxation or volatile markets, but rather the silent accumulation of small, recurring financial inefficiencies. These are the habits, purchases, and subscriptions that promise convenience, status, or fleeting comfort, yet deliver a staggeringly low return on investment.
To understand where wealth actually goes, one must look past the obvious expenses—rent, mortgages, insurance, and basic utilities. Those are fixed, visible, and generally negotiated with a degree of deliberate thought. The real financial leakage happens in the discretionary margins, in the gray areas of daily routine where marketing meets human psychology. Modern consumer culture has perfected the art of making waste feel like a necessity, transforming luxury into baseline expectation and convenience into a recurring monthly toll.
This article examines the structural anatomy of financial waste, focusing on the first five of the top ten things people routinely waste money on. By dismantling these habits and examining the psychological drivers behind them, it becomes possible to plug the leaks and redirect capital toward assets that genuinely compound in value over time.
1. The subscription ecosystem and ghost memberships
The shift from a ownership economy to a subscription economy represents one of the most brilliant marketing triumphs of the twenty-first century. Corporations quickly realized that charging a lower, recurring monthly fee is far more lucrative—and far less frictionless, than asking for a large, one-time payment. As a result, consumers now rent access to almost every aspect of modern life: entertainment streaming, software, cloud storage, meal kits, fitness apps, coffee delivery, and curated box services.
The financial danger of this model lies in human psychology and billing automation. Once a subscription is linked to an auto-renewing credit card, it bypasses conscious decision-making. Consumers consistently underestimate the total number of active subscriptions they maintain. Market research frequently shows that individuals believe they spend a fraction of what they actually do on recurring digital services.
Consider the anatomy of a typical subscription audit. A household might subscribe to three different video streaming services, a premium music platform, a cloud storage upgrade, an online gaming pass, two productivity apps, a newsletter bundle, and a monthly grooming box. Individually, each charge looks modest, ranging from five to fifteen dollars. Combined, they easily eclipse a hundred and fifty dollars every month, translating to nearly eighteen hundred dollars a year.
More insidious than the forgotten Netflix account is the gym membership paradox. Millions of people pay for annual or monthly fitness facility memberships they rarely or never use. Gym business models depend entirely on this behavioral quirk; if every paying member actually showed up at the same time, the facilities would instantly exceed capacity. People use the subscription as a financial proxy for virtue, convincing themselves that paying for the potential workout is equivalent to doing the work. Breaking this cycle requires a ruthless audit: canceling every recurring charge that has not been actively used in the past thirty days, with the clear rule that a service can always be re-subscribed to later if a genuine need arises.
2. Convenience pricing in food and beverage
Few areas of personal finance bleed capital quite as efficiently as the food and beverage sector, specifically through the multiplier effect of convenience. The modern schedule is demanding, and corporations have commercialized exhaustion by offering pre-packaged, pre-prepared, and delivery-based alternatives to home cooking.
The most common manifestation of this is the daily coffee habit and routine dining out. Purchasing a specialized coffee drink and a pastry every workday might seem like a harmless ritual, a small reward for navigating the stresses of daily employment. However, when calculated across an annual horizon, that five-to-seven-dollar daily habit balloons into fifteen hundred to two thousand dollars of after-tax income. Because money used for daily consumption is money that cannot be invested, the true cost of that coffee includes decades of missed compound growth.
Beyond beverages, the delivery app economy has transformed meal acquisition into a luxury experience disguised as a utility. Ordering a meal through a third-party delivery platform introduces a cascade of hidden costs: inflated menu prices, service fees, delivery fees, and mandatory tips. A meal that costs fifteen dollars at the restaurant counter can easily double in price by the time it arrives on a doorstep.
Convenience pricing extends to the grocery store. Buying pre-chopped vegetables, single-serving snack packs, pre-marinated meats, and bottled water means paying a massive premium for someone else's labor. The grocery store markup for convenience packaging often ranges from one hundred to three hundred percent. Reclaiming control over this category does not require a ascetic lifestyle devoid of pleasure; it requires recognizing the exact points where laziness or poor planning is being heavily monetized by third parties.
3. The new car depreciation trap
Automobiles represent the single largest consumer purchase most people will ever make, outside of real estate. They are also, almost without exception, catastrophic financial depreciators. Despite being widely understood as a depreciating asset, vehicles are routinely purchased with emotional criteria rather than rational economic calculation.
The financial error typically begins with the desire for a brand-new vehicle. The moment a new car is driven off the dealership lot, it suffers a steep drop in market value, often losing ten to twenty percent of its value within the first year alone. Dealerships exploit this by offering low monthly payments through extended loan terms, stretching financing agreements to six, seven, or even eight years.
Stretching a car loan is an effective way to mask the true cost of a vehicle, allowing buyers to purchase more car than they can genuinely afford. A long loan term means that for the first several years, the owner owes more on the vehicle than it is actually worth on the open market, a precarious position known as being "upside down" on the loan. Coupled with the high cost of full-coverage insurance, specialized maintenance, and rapid depreciation, a new car functions as a wealth-destruction machine for the average earner.
Purchasing a reliable, three-to-five-year-old vehicle with cash or a short-term, low-interest loan bypasses the steepest portion of the depreciation curve. Yet, status signaling often overrides financial common sense. Society trains people to view cars as extensions of personal identity and success, leading individuals to tie up a significant portion of their net worth in an asset that sits idle ninety-five percent of the time.
4. Impulse retail therapy and fast fashion
Modern commerce is engineered to induce spontaneous purchasing. From targeted social media advertisements that track user behavior across the web to algorithmically curated shopping feeds, consumers are constantly bombarded with stimuli designed to trigger immediate acquisition impulses.
Fast fashion and low-cost online retail hubs have accelerated this cycle. Items are manufactured so cheaply and priced so aggressively that buying them feels consequence-free. A twenty-dollar shirt or a fifteen-dollar gadget purchased on a whim requires virtually no deliberation. Yet, this low barrier to entry results in accumulation of clutter and continuous micro-spending.
The true waste in fast retail is not just the initial purchase price, but the utility extraction rate. Many impulse purchases are worn once, used a few times, or left in their packaging entirely before being discarded or pushed to the back of a closet. This behavior is often driven by emotional regulation, using shopping as a temporary fix for boredom, stress, or anxiety.
Overcoming this requires implementing friction in the purchasing process. Simple psychological barriers, such as a mandatory forty-eight-hour waiting period for any non-essential purchase over fifty dollars, give the rational part of the brain time to override the emotional impulse. When forced to wait, the vast majority of impulse desires evaporate entirely, revealing how fleeting the perceived value of the item actually was.
5. Bank fees, interest charges, and financial laziness
Perhaps the most frustrating category of financial waste is the money paid directly to financial institutions simply due to lack of attention or administrative inertia. Banks, credit card companies, and lenders generate billions of dollars annually through penalty fees, maintenance charges, and high interest rates levied on inattentive consumers.
This waste manifests in several distinct ways. First is the maintenance fee on checking and savings accounts that fail to meet arbitrary minimum balance requirements. Second, and far more damaging, is credit card interest. Carrying a balance from month to month on a high-interest credit card effectively neutralizes any budget optimization elsewhere. Paying twenty percent interest or more on consumer debt while simultaneously trying to save money is the financial equivalent of running on a treadmill with the incline cranked to maximum.
Consumers frequently overpay for insurance policies, utility plans, and telecommunications services simply because they have not shopped around or renegotiated their rates in years. Companies routinely rely on customer inertia, gradually raising prices on loyal, long-term subscribers who assume that switching is too difficult.
Eliminating this form of waste requires treating personal finance administration as a necessary maintenance chore. Setting up automated alerts, consolidating accounts, paying credit card balances in full every billing cycle, and conducting an annual review of all recurring utility and insurance providers will immediately stop the outflow of hard-earned money to corporate bottom lines.
Hello!