Anatomy of a meltdown: Understanding the timeline of the 2008 Financial Crisis Recovery
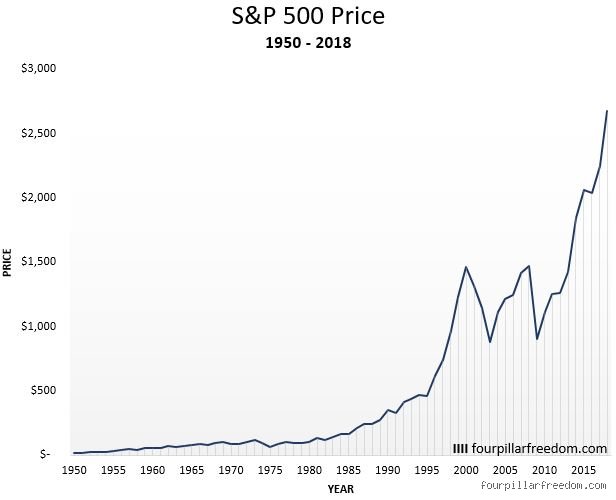
Evaluating the recovery timeline requires moving beyond a simple single-date answer. The duration of the rebound depends heavily on whether one measures by price recovery alone, total return including reinvested dividends, or the timeline calculated from the absolute market trough versus the pre-crisis peak. Generally speaking, the S&P 500 took approximately 5.5 years (or roughly 65 months) to fully climb back to its previous all-time high purely on a price basis, while factoring in dividends reduced that recovery window to roughly 4 to 4.5 years.
This comprehensive first part of our expert analysis breaks down the prelude, the depth of the crash, the nuances of the recovery mathematics, and the critical structural variables that dictated how long portfolios remained underwater.
The Pre-Crisis Peak and the long descent
To understand the recovery, one must first understand the depth of the fall. Prior to the crash, major equity indices experienced a prolonged bull market fueled by a housing bubble, loosely regulated derivatives, and widespread complacency.
The Peak: On October 9, 2007, the S&P 500 closed at an all-time record high of 1,565.15. Concurrently, the Dow Jones Industrial Average (DJIA) reached a peak of 14,164.53. At this moment, market sentiment remained largely optimistic, oblivious to the systemic risks festering within subprime mortgages and collateralized debt obligations (CDOs).
The Slow Erosion (Late 2007 to Summer 2008): The downturn did not happen overnight. It began as a slow bleed. Throughout late 2007 and the first half of 2008, financial stocks began to buckle. Notable early casualties included the collapse of Bear Stearns' internal hedge funds in mid-2007 and its eventual emergency buyout in March 2008. By June 2008, a formal bear market was declared as economic indicators worsened.
The Freefall (Fall 2008): The crisis shifted from a severe correction into an existential financial panic in September 2008. On September 15, 2008, Lehman Brothers—a 158-year-old global financial services firm—filed for Chapter 11 bankruptcy protection. This event froze global credit markets, triggered runs on money market funds, and sparked unprecedented market volatility. During this phase, daily moves of 5% to 9% (in both directions) became routine, and panic selling swept institutional and retail portfolios alike.
The Trough: The bleeding finally stopped on March 9, 2009. At its lowest point, the S&P 500 closed at 676.53, representing a staggering 56.78% peak-to-trough decline. The Dow suffered a similarly devastating drop of roughly 54%.
The mathematics of Recovery: Why downside is harder than upside
A fundamental principle of market economics dictates that losses require disproportionately larger gains to break even. This mathematical asymmetry is precisely why the 2008 crash took years to unwind.
When an asset portfolio drops by 50%, it requires a 100% gain just to return to the original starting balance. Because the S&P 500 plummeted by nearly 57% during the GFC, the market required a massive 131% cumulative rally from its March 2009 lows simply to reach breakeven.
+-----------------------------------------------------------------+
| THE RECOVERY MATH |
| |
| Peak (Oct 2007): 1,565.15 ======> Trough (Mar 2009): 676.53 |
| (-56.78% Drop) |
| |
| Trough (Mar 2009): 676.53 ======> Recovery (Mar 2013): 1,565 |
| (+131% Rally Required) |
+-----------------------------------------------------------------+
Financial analysts divide the recovery timeline into two distinct perspectives depending on the investor's entry point:
Measured from the Peak (October 2007): For an unfortunate investor who deployed a lump sum right at the market peak and never added another dollar, the journey back to even took 5 years and 5.5 months (reaching a decisive, sustained recovery by late March 2013).
Measured from the Trough (March 2009): For investors who had cash on the sidelines and bought aggressively at the bottom, or for those whose portfolios were established post-crash, the market doubled and fully recovered its prior milestone in 4 years (by March 2013).
The dividend factor: Price Return vs. Total Return
A critical nuance often overlooked in casual discussions of the 2008 crash is the role of dividends. The figures cited above typically reference the standard price-only index, which tracks exclusively the stock valuations of the S&P 500 companies.
However, when examining a total-return index (which assumes all quarterly dividend payouts are automatically reinvested back into the index), the recovery narrative shifts dramatically:
The Total Return Recovery: Due to the compounding effect of purchasing discounted shares via reinvested dividends throughout the bear market and early recovery phases, the S&P 500 total-return index reached its pre-crisis peak nearly a year earlier, by April to August 2012 (roughly 4.5 years after the October 2007 peak).
Dollar-Cost Averaging: Investors who maintained steady, periodic contributions to their retirement accounts (such as 401(k) plans) throughout 2008 and 2009 effectively bought equities at a deep discount, shortening their personal portfolio recovery timelines significantly compared to static lump-sum holders.
The long road to rebound: Breaking down the 2008 Recovery timeline
While the absolute bottom of the market occurred in March 2009, returning to the previous peak was a staggered, agonizingly slow journey depending on the specific asset class, index, and investment strategy. For the benchmark S&P 500, the complete price recovery, the point at which it formally crossed back over its October 2007 peak, did not happen until March 2013, roughly five and a half years after the initial downturn began, and nearly four years after the market bottomed.
However, looking strictly at the price return of major indexes tells only part of the story. Understanding the true duration of the 2008 recovery requires examining the critical differences between nominal price recovery, total return (incorporating dividends), and the psychological impact on everyday investors.
Price Return vs. Total Return: The dividend advantage
When people ask, "How long did it take to recover?" they are usually looking at the price index alone. But for long-term investors, dividends play an essential role in accelerating recovery times.
The S&P 500 Price Index: Took approximately 5.5 years (from October 2007 to March 2013) to reach its pre-crisis peak on a price-only basis.
The S&P 500 Total Return Index (Dividends Reinvested): Recovered significantly faster. Because companies continued to pay dividends, even amidst the carnage, investors who automatically reinvested their dividends bought heavily discounted shares during the depths of 2008 and 2009. Consequently, the total return recovery happened roughly a year earlier, shortening the pain window considerably.
This distinction highlights a core principle of modern portfolio management: cash flow generated during a bear market acts as a turbocharger for the eventual recovery.
Uneven Recovery across asset classes and sectors
Not all sectors experienced the same recovery timeline. The financial sector, which served as the epicentre of the crisis, faced a radically different reality than consumer staples or technology.
Financials and Real Estate: Many major financial institutions were either wiped out, nationalized, or forced into emergency mergers (e.g., Lehman Brothers, Bear Stearns, Merrill Lynch). For investors heavily concentrated in individual bank stocks, the "recovery" took decades, or never happened at all, as equity was completely wiped out.
Technology and Consumer Discretionary: Propelled by low interest rates, rapid corporate restructuring, and the dawn of mobile/cloud computing, growth sectors rebounded sharply after 2009, leading the bull market into the 2010s.
Real Estate (Housing Market): Residential real estate suffered alongside the stock market. While the stock market recovered by 2013, U.S. national home prices didn't return to their 2006 peak levels until roughly 2016–2017 in nominal terms, and even later when adjusted for inflation.
Behavioral lessons: Why time in the Market matters
The 2008 crash left psychological scars on a generation of investors, many of whom panicked and sold near the bottom in March 2009. Those who locked in their losses missed out entirely on the historic bull market that followed.
The data shows that a passive strategy involving dollar-cost averaging (DCA), continuously contributing fixed amounts of money into retirement accounts or index funds throughout 2008 and 2009, dramatically shortened the effective recovery timeline for individual portfolios. By purchasing equities at a 50% discount, regular contributors accumulated shares that multiplied rapidly during the subsequent economic expansion.
Conclusion
The 2008 financial crisis proved to be the most severe economic downturn since the Great Depression, with the S&P 500 shedding over 56% of its value from peak to trough. Yet, history demonstrates that resilient, diversified portfolios do recover given enough time.
For patient investors utilizing broad-based index funds and dividend reinvestment, the recovery window was roughly 4 to 5 years, a stark reminder that while market crashes are violent and deeply unsettling, long-term economic recovery remains the historical norm.