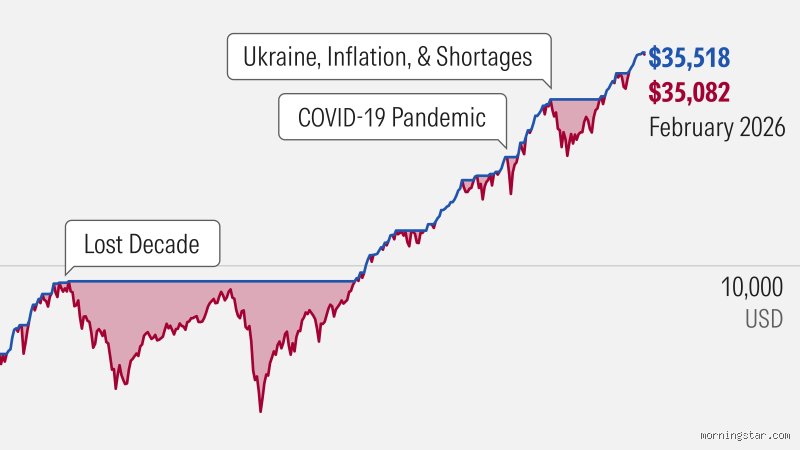
The perennial Fear of the great unwinding
For as long as public exchanges have existed, the specter of a market crash has haunted investors. Every generation believes that its unique combination of economic pressures, technological disruption, and financial innovation has set the stage for an unprecedented collapse. Today, as global markets navigate a complex landscape of shifting interest rates, post-pandemic economic adjustments, and rapid advancements in artificial intelligence, the whisper of "Is the big one coming?" has grown louder. Retail investors, institutional portfolio managers, and economic historians alike find themselves staring at charts that look eerily reminiscent of past pre-crisis peaks.
Yet, answering this question requires stripping away the sensationalist headlines and emotional panic that inevitably accompany financial journalism. A market crash is not merely a bad week, a turbulent month, or even a cyclical correction of ten percent. A true crash—a systemic meltdown of the variety seen in 1929, 2000, or 2008—is a profound structural event. It is characterized by sudden, panicky liquidations, severe liquidity freezes, cascading margin calls, and a fundamental breakdown in the pricing mechanisms of capital assets. To evaluate whether we are standing on the precipice of such an event, we must look past the superficial noise of daily market volatility and examine the foundational pillars that support modern equity valuations.
Historical precedents: How crashes actually form
To understand the mechanics of a potential future crash, we must study the anatomy of past collapses. History rarely repeats itself identically, but it rhymes with remarkable consistency. In almost every major financial crisis, a specific sequence of psychological and structural failures precedes the downfall.
Take the dot-com bubble of the late 1990s. The underlying catalyst was a genuine, world-changing technological revolution: the commercialization of the internet. Investors correctly recognized that the web would transform global commerce. However, this correct macro thesis was distorted by irrational exuberance. Companies with zero revenue and no viable business model achieved multibillion-dollar valuations simply by appending ".com" to their names. When reality finally caught up with speculation in March 2000, the NASDAQ composite plummeted by nearly 78 percent, wiping out trillions of dollars in wealth and taking years to recover.
Similarly, the 2008 global financial crisis was rooted in the housing market, but its severity was amplified by structural leverage and complex financial engineering. Subprime mortgages were bundled into opaque derivatives, rated AAA by complacent agencies, and leveraged heavily by major financial institutions using borrowed money. When housing prices leveled off and default rates ticked upward, the entire house of cards collapsed because the system was saturated with hidden leverage.
The lesson from these historical episodes is clear: crashes are rarely caused by a single bad news headline. Instead, they are the result of structural imbalances that accumulate over years. These imbalances typically manifest as excessive leverage, widespread overvaluation disconnected from fundamental cash flows, and a pervasive belief among market participants that "this time is different."
Decoding valuation metrics: Are stocks dangerously overpriced?
One of the primary arguments put forward by pessimists anticipating a crash is the sheer height of current equity valuations. Traditional metrics used to measure market expensiveness, such as the Shiller P/E ratio (Cyclically Adjusted Price-to-Earnings ratio), the Buffett Indicator (total market capitalization relative to GDP), and price-to-free-cash-flow multiples, are flashing warning signs.
The Shiller P/E ratio, which smooths out earnings over a ten-year economic cycle to account for inflation and business fluctuations, has historically hovered around an average of 17. During extreme market peaks, such as 1929 and 2000, this ratio climbed well past 30. In recent years, it has remained elevated at historical highs, surpassed only during the dot-com era and the peak of the 2021 post-stimulus rally. For value-oriented analysts, this metric alone suggests that future expected returns over the next decade will be muted, and the probability of a sharp mean-reverting correction is uncomfortably high.
Concurrently, the Buffett Indicator, which compares the total value of the stock market to the size of the national economy, has broken previous historical records. When this ratio climbs significantly above 100 percent, it implies that equities are commanding a price far out of proportion to the underlying productive capacity of the real economy.
However, looking at valuation metrics in a vacuum can lead investors astray. Proponents of the "new paradigm" argue that the structural composition of the stock market has fundamentally evolved. Modern market indices are heavily weighted toward asset-light technology giants. These companies boast massive profit margins, immense cash reserves, high returns on invested capital, and scalable business models that look nothing like the capital-intensive industrial and manufacturing firms of the 20th century. Because these mega-cap technology firms generate prodigious amounts of free cash flow, some analysts argue that higher P/E multiples are entirely justified. A dollar of earnings today commands a higher price because the quality, growth durability, and international reach of those earnings are superior to past eras.
The macroeconomic environment: Interest rates, inflation, and liquidity
Beyond stock-specific valuations, the broader macroeconomic backdrop plays a decisive role in determining whether a market crash is imminent. For over a decade following the 2008 financial crisis, global central banks maintained an ultra-loose monetary policy environment. Interest rates were pinned near zero, and central banks engaged in massive quantitative easing programs, flooding the global financial system with cheap liquidity.
In this environment, "There Is No Alternative" (TINA) became the dominant market mantra. With safe-haven assets like government bonds yielding virtually nothing, institutional investors, pension funds, and retail participants were forced out along the risk curve into equities, real estate, and speculative digital assets to generate any meaningful return.
The landscape shifted dramatically when inflation surged to multi-decade highs, forcing central banks worldwide into the most aggressive interest-rate-hiking cycle in modern history. Higher interest rates alter the fundamental math of investing in two profound ways:
The Discount Rate Effect: In financial theory, the present value of a company is equal to the sum of its future cash flows discounted back to the present. When interest rates rise, the discount rate increases. This mathematically reduces the present value of future earnings, hitting high-growth, long-duration technology stocks the hardest because the bulk of their projected cash flows lies far in the future.
The Risk-Free Competition: When short-term government bonds and high-yield savings accounts offer risk-free returns of 4 to 5 percent, the opportunity cost of holding volatile equities increases exponentially. Capital naturally rotates away from risk assets toward guaranteed yield.
Despite these headwinds, the anticipated recession and subsequent market crash following the rapid rate hikes have been remarkably delayed. Corporate balance sheets entered this tightening cycle in relatively strong shape, having locked in low-interest fixed-rate debt during the pandemic era. Consumer balance sheets, bolstered by accumulated savings and resilient labor markets, sustained spending longer than many economists predicted.
Structural vulnerabilities in modern markets
Even if macroeconomic fundamentals avoid a catastrophic downturn, modern financial market architecture contains unique structural features that can accelerate a routine sell-off into a full-scale crash.
The rise of passive investing, specifically exchange-traded funds (ETFs) and index funds, has fundamentally transformed how capital flows through the market. A vast majority of daily trading volume is now driven by systematic, algorithmic, and passive strategies that buy or sell entire baskets of stocks based on rules rather than fundamental business analysis. While indexation has lowered costs for everyday investors, it introduces a dangerous feedback loop during periods of distress. When a wave of selling is triggered, passive vehicles sell constituents indiscriminately, regardless of an individual company's underlying financial health. This can cause high-quality, fundamentally sound companies to plunge alongside overvalued speculative assets during a liquidity squeeze.
The proliferation of retail trading platforms, zero-commission brokerages, and options trading has injected a high degree of speculative fervor into specific pockets of the market. Short-dated options trading and leveraged exchange-traded products can create localized gamma squeezes, where market makers are forced to buy underlying shares rapidly to hedge their positions, driving artificial upside volatility. Conversely, when momentum reverses, these same derivative structures can accelerate downward spirals with breathtaking velocity.
The psychology of Fear and greed
No analysis of a potential stock market crash is complete without acknowledging human psychology. Markets are ultimately aggregate reflections of human fear, greed, hope, and panic.
Behavioral finance demonstrates that investors are loss-averse; the pain of losing money is psychologically twice as intense as the joy of making an equivalent gain. During a bull market, greed dominates, driving prices higher as investors engage in FOMO (Fear Of Missing Out) and chase momentum. However, market sentiment can flip on a dime. When a catalyst emerges, whether it is a geopolitical conflict, a banking failure, or a macroeconomic shock, fear takes over.
Margin calls act as the primary transmission mechanism for this psychological panic. When leveraged investors see the value of their portfolio drop below required maintenance levels, their brokers automatically liquidate their holdings to cover debts. This forced selling pushes prices down further, triggering more margin calls at lower price thresholds. This self-reinforcing feedback loop is what separates a standard market decline from a true systemic crash.
Historical echoes – what past bubbles teach us about the next big drop
Market downturns rarely arrive out of nowhere; they generally rhyme with historical precedents. To understand whether a monumental crash is imminent, looking back at legendary corrections, such as the 1929 crash, the 2000 Dot-Com bust, and the 2008 Global Financial Crisis, reveals recurring behavioral patterns among investors and policymakers alike.
The psychology of mania and denial
Every major market peak shares a common psychological footprint: absolute conviction that "this time is different." During the late 1990s, investors poured capital into dot-com startups with zero revenue, convinced that the internet had fundamentally rewritten the rules of corporate valuation. Similarly, in the mid-2000s, subprime mortgages were bundled into AAA-rated securities, with institutions operating under the assumption that nationwide real estate prices never drop simultaneously.
When valuations stretch to historic highs today, particularly within concentrated sectors like artificial intelligence and mega-cap technology, echoes of past manias become audible.
Euphoria breeds leverage: Low interest rates and easy access to margin debt amplify speculative bubbles.
The narrative shift: When sentiment turns, the narrative pivots overnight from "growth potential" to "systemic risk," triggering forced liquidations.
Structural breaks vs. Cyclic corrections
History also distinguishes between a standard bear market, a routine 20% pullback that cleanses excess, and a systemic crash that shatters financial plumbing. A cyclic correction is typically absorbed by diversified portfolios within a few years, whereas a structural break causes cascading failures across interconnected institutions.
During 2008, the issue wasn't merely falling home values; it was opaque counterparty risk within the derivatives market. Today, systemic vulnerability might look different, hiding within private equity valuations, shadow banking networks