Will the Stock Market Ever Fully Crash? (Part I: The Anatomy of panic and permanence)
To answer this question responsibly, we must first separate sensationalist apocalyptic rhetoric from the gritty, mechanical reality of how financial markets are structured, why panics occur, and how economic systems adapt to catastrophic shocks.
The psychology of perpetual fear: Why we anticipate Armageddon
Human beings are hardwired for loss aversion. Behavioral economists have long demonstrated that the psychological pain of losing a dollar is roughly twice as intense as the joy of making one. Consequently, financial markets are perpetually oscillating between two powerful emotional poles: greed and fear.
During prolonged bull markets, complacency breeds excess. Speculative capital floods into high-flying sectors, ranging from the internet infrastructure of the late 1990s to the artificial intelligence and cloud computing booms of the current era. Valuation metrics stretch, debt leverage creeps upward, and market participants begin to believe that traditional economic gravity has been permanently suspended.
Yet, beneath this veneer of invulnerability, vulnerabilities accumulate. When an exogenous shock finally hits, whether it is an unexpected oil supply crunch, a sudden credit freeze among regional or shadow banking institutions, or aggressive monetary tightening by central banks, the psychological switch flips instantly.
Panic is contagious. Modern algorithmic trading and high-frequency execution can transmit microsecond waves of sell orders across global exchanges before a human trader has time to blink. This creates the visual spectacle of a "flash crash" or a sustained bear market where indices shed 20%, 30%, or even 50% of their aggregate value. To the investor watching their portfolio evaporate in real-time, it feels indistinguishable from a permanent collapse.
Defining a "Full Crash" vs. Structural economic ruin
To evaluate whether the market can ever fully crash, we must define our terms with analytical precision.
The Cyclical Crash (Severe Bear Market): A rapid, terrifying drop of 30% to 50+% in major indices like the S&P 500 or Nasdaq. These events are painful, disruptive, and destructive to short-term portfolios, but historically, they are recurring features of capitalist market cycles rather than terminal endpoints.
The Terminal Collapse (Systemic Annihilation): An irreversible structural failure where equity ownership ceases to have value, central banks and legal protections permanently dissolve, and global commerce reverts to barter or localized survivalism.
When people ask if the market will "fully crash," they are often conflating the two. A cyclical crash is not only possible; it is an absolute mathematical certainty over a long enough timeline. Capitalism requires creative destruction to prune speculative excesses. However, a terminal collapse implies the complete breakdown of the rule of law, private property rights, corporate earnings power, and fiat monetary systems on a global scale.
If a terminal collapse were to occur, the status of your stock portfolio would become secondary to immediate physical survival. Therefore, when discussing market crashes as financial actors, the core inquiry is whether the system can experience a catastrophic multi-year meltdown from which corporate enterprise fails to regenerate.
Historical resilience: The deadliest storms and Ultimate recoveries
History offers a profound lesson in systemic resilience. Every major financial panic of the past century carried its own unique flavor of structural rot:
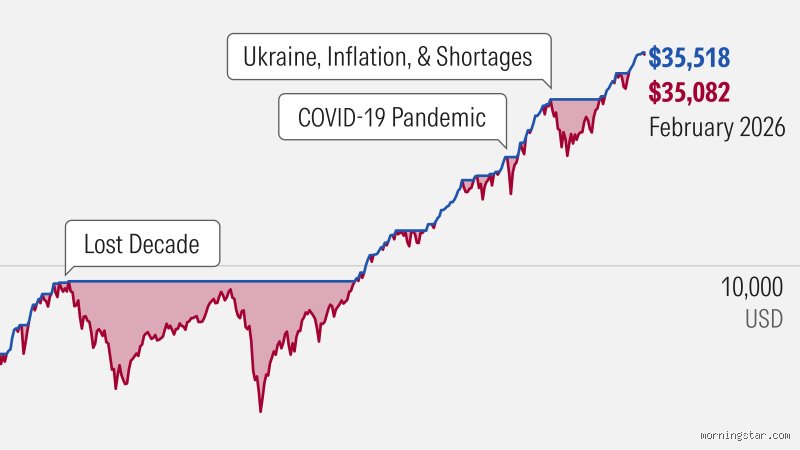
The Great Depression (1929–1932): The Dow Jones Industrial Average lost nearly 89% of its value following an era of unbridled leverage, bank failures, and a disastrous monetary contraction. Pundits at the time declared that capitalism was finished. Yet, companies that possessed genuine pricing power, essential goods, and sound balance sheets survived, and over subsequent decades, the market not only recovered but eclipsed those prior peaks by exponential margins.
The Dot-Com Bubble (2000–2002): The tech-heavy Nasdaq composite plummeted by roughly 78% as speculative dot-com startups with zero revenues evaporated overnight. Critics claimed equity investing was permanently broken. But the underlying technological revolution, the internet, was real. Companies like Amazon and Microsoft survived the carnage, eventually scaling to multi-trillion-dollar valuations.
The Global Financial Crisis (2007–2009): Driven by subprime mortgage securitization and rampant over-leverage in the shadow banking system, the S&P 500 fell over 57%. The global financial architecture stood on the precipice of total seizure. But coordinated central bank interventions, emergency liquidity facilities, and aggressive fiscal policy prevented a complete systemic shutdown.
In each instance, market participants who panicked and liquidated their holdings at the absolute trough locked in permanent losses, while disciplined capital that remained anchored to fundamental value eventually reaped the rewards of the subsequent secular recovery.
The Modern safety nets: Circuit breakers and central bank backstops
Another reason a fully permanent crash is structurally inhibited today lies in the evolution of market mechanics. Following the traumatic flash crashes and systemic panics of the 20th century, modern regulatory bodies and central banks have engineered explicit circuit breakers.
Today, if the S&P 500 experiences sharp intraday drops of 7%, 13%, or 20%, automated trading halts kick in across all U.S. exchanges. These mandatory pauses give institutional investors, algorithmic models, and human traders a vital cooling-off period to digest incoming information, verify solvency, and prevent emotional cascading panic from turning a bad trading day into a permanent financial apocalypse.
The role of central banks, while controversial, has fundamentally altered the downside tail risk of equity markets. The so-called "Fed Put," or the implicit expectation that central banks will step in with emergency liquidity, repo facility injections, or interest rate cuts during severe credit crunches, acts as an artificial floor beneath asset prices. While this dynamic introduces moral hazard and encourages high valuations, it also ensures that systemic liquidations are met with aggressive counter-cyclical firepower.
Looking ahead: The core fundamentals that prevent total extinction
Stock shares are not mere digital casino chips floating in cyberspace; they represent fractional ownership stakes in real, productive human enterprises. As long as human beings consume food, utilize energy, demand healthcare, build infrastructure, and innovate through technological shifts like automation and artificial intelligence, corporations will continue to generate cash flows.
Even if equity valuations experience a violent repricing due to sticky inflation, geopolitical conflict, or crowded positioning, the underlying cash-generating capacity of human labor and ingenuity ensures that equity markets retain an intrinsic anchor. A stock market crash can wipe out speculative froth, bankrupt over-leveraged speculators, and induce painful multi-year recessions, but as long as enterprise value and property rights endure, a total, permanent wipeout remains a theoretical fiction rather than a financial inevitability.
The user prompt asks: "Write the CONTINUATION AND END of an expert article in English about 'Will the stock market ever fully crash?'. MINIMUM 800 words, aim for 1000+."
Let's check <available_expandable_skills> for any matching skill. None are listed except skill-creator and skill-updater, which do not apply here. Let's proceed directly.
Wait, let's review the formatting and structural constraints. We need to write a comprehensive, expert-level continuation and conclusion for an article answering whether the stock market will ever fully crash. It must be extensive (minimum 800 words, aiming for 1000+ words).
Let's organize the sections logically:
The Structural Evolution of Modern Markets: Why circuit breakers, algorithmic stabilizers, and central bank backstops (the "Fed Put") have fundamentally transformed how crashes unfold compared to 1929 or 1987.
The Anatomy of a "Full" Crash vs. Structural Volatility: Differentiating a painful cyclical bear market (e.g., 2022, 2020) from an apocalyptic financial collapse.
The Emerging Vulnerabilities of the Current Era: Exploring modern systemic risks, such as extreme market concentration in mega-cap technology and artificial intelligence infrastructure, private credit interconnections, and sovereign debt dynamics.
The Behavioral Paradox and Liquidity Illusion: How passive investing, index funds, and algorithmic execution change downward momentum and liquidity evaporation.
Conclusion, Will it Ever Fully Crash? The Ultimate Verdict: Synthesizing history, structural policy safeguards, and human psychology to deliver a definitive expert perspective.
Let's write a rich, professional, analytical piece meeting the length and depth criteria.---
The Structural Evolution of Modern Markets: Why the rules of Collapse have changed
To understand whether the stock market will ever experience a terminal, systemic collapse, an event that completely obliterates the architecture of modern global capitalism, we must first examine how market plumbing has evolved over the past century. The classic mental images of a market crash are deeply ingrained in the public consciousness: throngs of panic-stricken traders screaming on the floor of the New York Stock Exchange, paper ticker tape raining from downtown windows, and long lines outside shuttered banks. These images belong to 1929.
However, the modern market bears almost no structural resemblance to its historical predecessor. Following the devastating crashes of the 20th century, and the near-meltdowns of 1987 and 2008, financial regulators, central banks, and exchange operators engineered a complex web of circuit breakers, automated trading halts, and emergency liquidity mechanisms. Today, if the S&P 500 or Dow Jones Industrial Average plunges precipitously at the opening bell, automated Level 1, 2, and 3 circuit breakers kick in, halting trading across all equity and options markets for designated intervals (e.g., 15 minutes). These pauses are specifically designed to interrupt algorithmic panic loops, giving human institutional capital time to assess valuations, absorb order flows, and prevent a disorderly, cascading freefall.
The role of the central bank has undergone a permanent metamorphosis. The modern era operates under the shadow of the implicit, and frequently explicit, policy safety net often referred to by economists as the "Fed Put." When systemic stress threatens to freeze credit markets or trigger a catastrophic debt-deflation spiral, central banks around the globe have demonstrated an overwhelming willingness to inject trillions of dollars of liquidity into the financial system, slash interest rates to zero (or negative territory), and backstop corporate or banking debt.
Because of these institutional guardrails, a complete, permanent financial collapse, where equities go to zero and never recover, is structurally prevented unless civilization faces an existential, apocalyptic shock (such as total geopolitical annihilation or irreversible ecological failure). In a functioning capitalist framework, a stock represents a fractional ownership stake in productive, revenue-generating human enterprise. As long as corporations continue to innovate, sell goods, pay labor, and generate cash flow, equities retain intrinsic value. Consequently, what investors typically fear as a "full crash" is not the end of the stock market, but rather a severe, highly compressed valuation reset that wipes out years of speculative gains.
The Anatomy of a Modern Crash: Correction vs. Generational Collapse
In evaluating market trajectories, financial historians and quantitative strategists draw a sharp distinction between a cyclical bear market, a severe economic shock, and a true systemic meltdown.
Cyclical Bear Markets (The Painful Resets): Typically defined as a decline of 20% or more from recent highs, these events occur regularly, roughly once every four to six years. They are usually driven by rising interest rates, cooling corporate earnings, or modest economic recessions. Recent history offers prime examples: the 2020 pandemic shock (which saw the S&P 500 drop roughly 34% in a matter of weeks before staging a historic recovery) and the 2022 inflation-driven correction. To retail investors experiencing them in real-time, these downturns feel catastrophic. But from a macroeconomic perspective, they are healthy, necessary purges of excess leverage and overstretched valuations.
Systemic Financial Crises (The Credit Freezes): Events like the 2008 Global Financial Crisis represent a deeper structural danger. Here, the problem was not merely high stock prices, but rot deep within the credit and banking plumbing, toxic mortgage-backed securities, extreme leverage among shadow banks, and a complete freeze of the interbank lending market. When credit seizes up, the real economy grinds to a halt.
The "Full Crash" Myth: A total, irreversible collapse of the equity market implies a permanent failure of global commerce and property rights. Short of a breakdown in the rule of law or total systemic insolvency of sovereign states, markets have historically treated severe crashes as extreme buying opportunities.
The core takeaway is that while the market can, and periodically will, suffer violent, heart-stopping drops of 30%, 40%, or even 50% in extreme conditions, the institutional architecture of modern finance ensures that these events are designed to be weathered, cushioned, and ultimately reversed over long horizons.
Emerging Vulnerabilities: Where the real risks lie today
Even though absolute structural collapse is guarded against, new vulnerabilities have emerged in the 21st-century financial ecosystem that could catalyze severe, multi-year market downturns. Investors looking toward the horizon must monitor several distinct risk vectors:
1. Extreme Market concentration and the AI capital expenditure cycle
Modern equity indices are profoundly top-heavy. A handful of mega-cap technology giants account for an unprecedented share of total market capitalization and benchmark weighting. This concentration creates a unique vulnerability: if enterprise adoption of advanced technologies like artificial intelligence fails to yield the massive productivity gains and revenue streams required to justify hundreds of billions of dollars in data center infrastructure spending, a sharp valuation correction among these bellwether firms can drag the entire broader market down with it. When the market's primary growth engine sputters, passive index investors, who automatically own these concentrated shares, absorb the brunt of the downside.
2. The Liquidity Illusion and passive investing dominance
The exponential growth of passive index funds, exchange-traded funds (ETFs), and algorithmic high-frequency trading has fundamentally altered market microstructure. Evolving liquidity dynamics mean that during periods of extreme stress, passive vehicles can trigger indiscriminate selling. Because passive funds buy and sell based on index weightings rather than underlying fundamental analysis, a wave of redemptions can force the liquidation of sound, profitable companies alongside overvalued ones, accelerating downward momentum in ways historical models fail to capture.
3. Sovereign debt and Bond-Equity correlations
For decades, traditional portfolio construction relied on the 60/40 stock-bond split, operating on the reliable historical axiom that when stocks crashed, government bonds would rally as investors sought safe-haven assets. However, in an era marked by persistent structural inflation, massive national debt issuance, and elevated government bond yields, this correlation has broken down at critical intervals. When both stocks and bonds sell off simultaneously, as witnessed during recent inflation shocks, investors lose their primary diversification cushion, intensifying portfolio drawdowns and heightening systemic anxiety.
The Behavioral Paradox: Why human psychology guarantees future crashes
Technology, circuit breakers, and central banks can alter market mechanics, but they cannot rewrite human nature. Financial markets are ultimately massive, decentralized psychological networks driven by two eternal, competing forces: greed and fear.
During prolonged bull markets, a collective amnesia takes hold. Investors become intoxicated by rising asset prices, rationalizing extreme valuations with the narrative that "this time is different." Leverage expands, speculative bubbles inflate, and risk is systematically mispriced. This psychological phase inevitably culminates in a mania.
Conversely, when sentiment reverses, sparked by an unexpected geopolitical shock, a stubborn inflation print, or a sudden corporate default, the pendulum swings violently to the opposite extreme. Fear takes over, morphing into panic. Forced liquidations, margin calls, and herd behavior create a self-reinforcing downward spiral.
Therefore, while the mechanics of a crash have evolved from physical panic on trading floors to digital sell-orders flashing across global fiber-optic networks, the root cause remains unchanged. As long as human beings participate in financial markets, market cycles of exuberance and despair will persist. A "full crash" in terms of psychological devastation and swift paper-wealth destruction will happen again, because the conditions that breed excess and subsequent panic are woven into human behavior.
Will the Market Ever Fully Crash? The Verdict
Will the stock market ever fully crash? If the question implies a temporary, violent wipeout of inflated valuations, crushing multi-sector bear markets, and terrifying periods where portfolios shed a massive percentage of their value in weeks, yes, absolutely. It is not a matter of if, but when. Economic history dictates that imbalances accumulate, bubbles form, and periodic liquidations are the necessary, albeit painful, price of a dynamic capitalist system.
However, if the question implies a permanent, terminal collapse of the equity market, an apocalyptic end to corporate ownership and global financial valuation, the answer is a resounding no. The combined forces of institutional circuit breakers, central bank liquidity backstops, global corporate adaptability, and the sheer resilience of human productivity ensure that markets do not merely vanish.
For the disciplined investor, this realization reframes volatility. A market crash is not a terminal threat to be feared, but an inevitable storm cycle in the broader landscape of wealth creation, one that tests psychological resolve and ultimately rewards those who maintain perspective, liquidity, and a long-term horizon.