At first glance, human psychology and retail intuition scream after. After all, waiting ensures that the investor collects the cash dividend deposited directly into their brokerage account, capturing what feels intuitively like a guaranteed bonus on top of their equity position. Conversely, selling before the ex-dividend date means walking away from a cash payout that you have watched accumulate on paper.
However, professional portfolio managers and quantitative finance professionals approach this question through a completely different lens, one shaped by market efficiency, corporate finance theory, and complex tax jurisdictions.
1. Demystifying the "free money" fallacy
To evaluate whether selling before or after a dividend is advantageous, we must first dismantle the most pervasive myth in retail investing: the belief that a dividend payment represents free, additive wealth.
When a publicly traded company announces a cash dividend, it is signaling financial health, steady cash flows, and shareholder-friendly capital allocation policies. However, a dividend is not a lottery win or a gift from corporate management. It is a mandatory cash outflow from the corporation’s balance sheet.
When a company pays out cash to its shareholders, its total enterprise value decreases by the exact aggregate amount of that cash disbursement. Imagine a lemonade stand that owns five dollars in cash and a lemon squeezer worth ten dollars, giving it a total net asset value of fifteen dollars. If the owner decides to distribute five dollars in cash to themselves, the stand now owns zero cash and a lemon squeezer worth ten dollars. Its net asset value drops instantly to ten dollars.
Public equity markets operate on this exact same economic principle. A corporation is worth the sum of its future cash flows discounted to present value, plus its current net assets, including cash on hand. When cash leaves the corporate treasury to land in a shareholder's brokerage account, the intrinsic value of the corporation is reduced by that exact cash amount. Understanding this fundamental identity is the cornerstone of answering the timing question.
2. Anatomy of a Dividend timeline: Understanding the Ex-Dividend Date
Many investors confuse the dates associated with dividend distributions, leading to flawed execution strategies. To time a sale effectively, you must understand four critical milestones in the dividend lifecycle:
Declaration Date: The date the company's board of directors officially announces the upcoming dividend, specifying the dollar amount, the record date, and the payment date.
Ex-Dividend Date: The most critical date for any investor contemplating a sale. This is typically one business day before the record date. If you buy a stock on or after the ex-dividend date, you are not entitled to the upcoming dividend. Conversely, if you own the stock before the ex-dividend date and sell on or after it, you retain the right to receive the dividend.
Record Date: The date the company checks its ledger to determine which shareholders are officially registered to receive the dividend payout.
Payment Date: The day the cash dividend is actually deposited into the eligible shareholders' brokerage accounts.
Because the ex-dividend date is the definitive dividing line that determines who gets paid, it is the exact moment when market prices adjust to reflect the impending cash outflow.
3. The mechanics of Market valuation and the Ex-Dividend price drop
What happens to a stock’s price on the morning of its ex-dividend date? In a theoretically efficient market, the stock price opens lower by the exact amount of the dividend.
If Company XYZ is trading at one hundred dollars per share and declares a two-dollar quarterly dividend, rational market participants, including institutional algorithmic traders, market makers, and arbitrageurs, will reprice the stock downward at the market open on the ex-dividend date. The opening price will adjust to ninety-eight dollars, assuming all other broader market conditions remain constant.
This price adjustment is not a penalty or a market anomaly; it is a mathematical necessity. If a stock did not drop by the dividend amount on the ex-dividend date, an immediate arbitrage opportunity would exist. Investors could buy the stock moments before the ex-dividend date, collect the two-dollar cash payment, sell the stock at the exact same entry price of one hundred dollars, and lock in a risk-free two percent return. Because modern financial markets do not tolerate risk-free arbitrage, prices adjust instantly.
The Real-World friction: Market noise and volatility
While the theoretical price drop is exact, real-world execution is complicated by daily market volatility. If Company XYZ drops two dollars on its ex-dividend date, but the broader stock market surges by three percent that same morning due to positive macroeconomic data, Company XYZ’s stock price might actually finish the day higher.
This creates a psychological illusion for retail investors. An investor who sells after the ex-dividend date might look at their account and see that the stock price went up or stayed flat, leading them to believe they "got the dividend for free" without suffering a capital loss. In reality, the stock underperformed the broader market or its own intrinsic trajectory by the exact amount of the dividend. Had they sold before the ex-dividend date, their capital would have been positioned differently, and their total return profile would have reflected the avoidance of that mechanical price reduction.
4. The Tax Trap: Capital Gains vs. Dividend income
While the pre-tax economic value of selling before versus selling after a dividend is theoretically neutral (thanks to the ex-dividend price adjustment), tax policy changes the math completely.
Different jurisdictions tax dividend income and capital gains differently, introducing a powerful variable that can heavily tilt the scales in favor of selling either before or after.
Ordinary income vs. Qualified Dividends
In the United States and many other developed tax frameworks, dividends are categorized as either ordinary (taxed at higher marginal income tax rates) or qualified (taxed at preferential long-term capital gains rates, typically 0%, 15%, or 20%). However, to qualify for the lower rate, an investor must satisfy the holding period requirement, typically holding the stock unhedged for more than 60 days during the 121-day window that begins 60 days before the ex-dividend date.
If an investor buys a stock just days before the ex-dividend date and sells it shortly thereafter, any dividend received will likely fail the holding period test and be taxed as ordinary income. For high-income earners, this can trigger a tax rate exceeding 37% plus state taxes, compared to the much lower capital gains rates.
Capital Gains realization and Tax timing
Selling a stock before the ex-dividend date realizes a capital gain or loss immediately. Selling after the ex-dividend date separates the transaction into two distinct taxable events:
The receipt of taxable dividend income (often taxed in the year received).
The eventual realization of a capital gain or loss when the stock is sold, where the cost basis is calculated against the post-dividend market price.
For taxable accounts, forcing a dividend payout can create an unwanted tax liability in the current calendar year. If an investor does not need immediate liquidity, triggering a taxable dividend event can destroy tax-advantaged compounding efficiency, whereas holding capital in unrealized capital gains allows the investor to defer taxation until they choose to execute a sale.
Preview of Part 2
As we have established in this foundational analysis, the decision to sell a stock before or after a dividend is rarely as simple as capturing a cash bonus. The mechanical price drop on the ex-dividend date neutralizes the immediate financial gain, while complex tax rules, transaction costs, and portfolio rebalancing requirements introduce significant strategic nuances.
In the upcoming second part of this expert guide, we will dive into advanced execution strategies, including:
Quantitative evaluations of the Dividend Capture Strategy and why it frequently underperforms buy-and-hold investing after accounting for transaction friction and taxes.
How institutional investors factor dividend schedules into options pricing models and total return forecasts.
A definitive decision-making framework to help you determine whether your specific tax bracket, time horizon, and portfolio goals dictate selling before or after your next major dividend distribution.
...As established in the mechanics of the ex-dividend timeline, the stock price adjusts downward on the ex-dividend date by roughly the exact value of the distribution. Therefore, the choice of whether to sell before or after a dividend is rarely about capturing "free money", because no such surplus exists. Instead, the decision hinges on a complex interplay of tax efficiency, transaction costs, portfolio rebalancing goals, and behavioral psychology.
Below is the continuation and expert conclusion to help you navigate this strategic crossroads.
The Tax maze: Qualified Dividends, Ordinary income, and account types
Tax treatment is arguably the most critical variable when timing your sale around a dividend distribution. How Uncle Sam (or your local tax authority) views your transaction can drastically alter the net profitability of selling before versus after.
Taxable Brokerage Accounts: In a standard taxable account, dividends trigger an immediate tax event in the calendar year they are paid.
Qualified Dividends: If you hold the stock for more than 60 days during the 121-day window surrounding the ex-dividend date, the dividend qualifies for preferential long-term capital gains tax rates (0%, 15%, or 20% depending on your income).
Ordinary (Unqualified) Dividends: If you fail the holding period requirement, the dividend is taxed at your ordinary income tax rate, which is frequently much higher.
Capital Gains Realized on Sale: When you sell the stock, you also trigger a capital gains tax (or harvest a capital loss). If you sell after collecting the dividend, you are taxed twice in a single transaction: once on the dividend income and once on the capital gain. If you sell before the ex-dividend date, you bypass the dividend tax entirely, consolidating your return solely into capital gains.
Tax-Advantaged Accounts (IRAs, Roth IRAs, 401ks): In retirement accounts, tax consequences are neutralized in the short term. Dividends can accumulate tax-free or tax-deferred, and selling within the account does not trigger immediate capital gains tax. If your holdings are entirely within a tax-advantaged vehicle, you can largely ignore tax implications and focus purely on fundamental valuation and asset allocation.
The fallacy of the "Dividend Capture" Strategy
Many novice retail investors attempt to execute what is known as the dividend capture strategy. The premise sounds foolproof: buy a high-dividend stock just before the ex-dividend date, collect the payout, and immediately sell the stock on or after the ex-dividend date to pocket a quick return.
In reality, the efficient market hypothesis makes this strategy exceedingly difficult to execute profitably for several reasons:
The Market Pricing Adjustment: As noted earlier, stock exchanges and automated market-making algorithms automatically markdown the stock's opening price on the ex-dividend date by the exact amount of the dividend. If a $100 stock pays a $2.00 dividend, it will typically open near $98.00.
Friction and Transaction Costs: Bid-ask spreads, brokerage commissions, and slippage eat into potential margins.
The Tax Drag: Even if the stock price remains resilient due to heavy buying pressure from other income-seeking investors, you are still left with a taxable dividend event. When you factor in short-term capital gains taxes or ordinary dividend tax rates, the net yield of a mechanical dividend capture strategy often underperforms a simple buy-and-hold index fund.
Total return vs. Yield chasing
When deciding when to sell, experienced investors prioritize total return (capital appreciation plus reinvested dividends) over nominal dividend yield.
The Dividend Trap: Sometimes, a sky-high dividend yield is a warning sign rather than a blessing. If a company's stock price has plummeted due to deteriorating fundamentals, its dividend yield will mathematically spike. Selling after collecting a dividend in such a scenario often locks in a severe capital loss that dwarfs the cash payout you received. In such cases, cutting ties before the dividend event, and before further fundamental erosion occurs, is almost always the wiser choice.
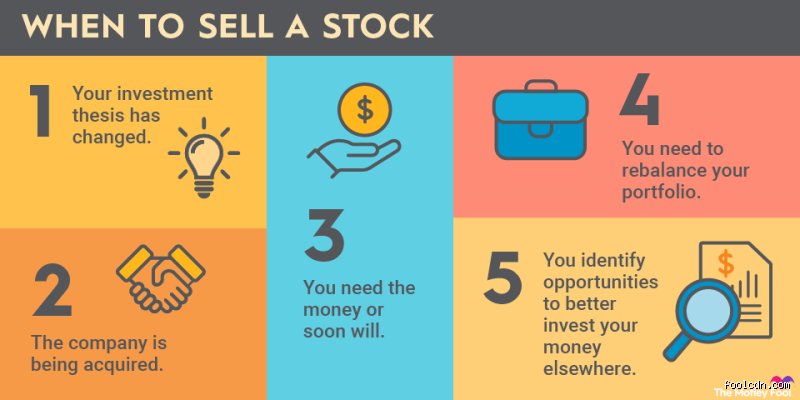
Capital Allocation Efficiency: Ask yourself: Is this company the best place for my capital right now? If a stock has reached your target valuation, or if you need to rebalance your portfolio to reduce risk, holding onto an asset merely because an ex-dividend date is three days away is emotional investing, not strategic investing.
Psychological biases and the "Dividend fallacy"
Behavioral finance reveals that investors frequently suffer from mental accounting and loss aversion when dealing with dividends.
Many investors view dividends as "free cash flow" or "allowance" generated by their portfolio, while viewing stock price declines as temporary paper losses. This creates a psychological barrier against selling shares. Ironically, mathematically speaking, selling a small fraction of a non-dividend-paying stock yields the exact same economic result as collecting a cash dividend from a paying stock.
If you own $10,000 of a stock that pays a 3% dividend, you receive $300 in cash, and your portfolio value drops by $300 (before market fluctuations). If you own $10,000 of a stock that pays no dividend and you manually sell $300 worth of shares, you end up with $300 in cash and $9,700 remaining in the stock. Recognizing that dividends are simply a forced corporate liquidation of your equity helps eliminate the emotional attachment to the ex-dividend calendar.
Your decision framework
Is it better to sell a stock before or after a dividend? The definitive expert answer is: It depends entirely on your broader financial strategy, tax situation, and valuation thesis, never on the dividend date alone.
Use this quick checklist to make your decision:
Sell BEFORE the ex-dividend date if:
You believe the stock is overvalued and you want to lock in capital gains while avoiding an additional taxable dividend event in a taxable account.
The company's fundamentals are weakening, and you fear the stock price will drop past the dividend amount post-payout.
You need to rebalance your portfolio weights immediately to control risk.
Sell AFTER the ex-dividend date if:
You are holding the stock long-term for its compounding income stream, and selling post-dividend aligns with your retirement cash flow plan.
You qualify for favorable qualified dividend tax rates and the minor price adjustment on the ex-dividend date aligns with your orderly exit strategy.
The transaction occurs within a tax-advantaged account (like a Roth IRA), rendering tax timing irrelevant.
Successful investing is about optimizing your entire asset allocation for long-term growth and stability. Let fundamental business analysis and personal financial goals, not calendar dates set by corporate boards, dictate when you buy and sell.