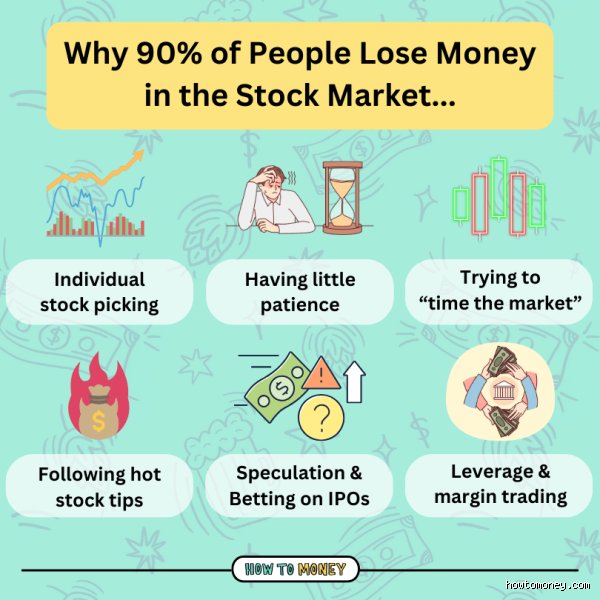
The stock market is often romanticized as a great equalizer—a digital frontier where anyone with an internet connection and a small stake can plant a flag and watch their wealth compound. Yet, beneath the glossy surface of success stories and overnight gains lies a stark, unvarnished reality: the vast majority of retail participants routinely watch their portfolios bleed. If you find yourself staring at a declining account balance, wondering how promising investments turned into painful financial drains, you are certainly not alone.
Losing money in stocks rarely happens because of a single catastrophic error. Instead, it is usually the cumulative result of hidden psychological traps, structural misunderstandings of risk, and the absence of a concrete operational framework. To stop the bleeding, you must first understand the mechanics of why capital leaks out of portfolios in the first place.
1. The Illusion of Control and the Trap of Emotional Trading
When real money is on the line, the human brain undergoes a fascinating and dangerous shift. Decisions that seem logically bulletproof on paper—such as cutting a losing trade or taking partial profits—suddenly become emotionally paralyzing in practice.
Market psychology is dominated by a few powerful cognitive biases:
Loss Aversion: Psychologically, the pain of losing a dollar hurts twice as much as the joy of making one. Because of this, struggling investors often hold onto declining stocks indefinitely, clinging to the desperate hope that "it will eventually come back to even." In reality, time does not heal a broken investment thesis; it often deepens the wound.
FOMO (Fear of Missing Out) and Chasing: Seeing a stock skyrocket 50% in a week triggers an impulsive urge to buy in at the absolute peak. This behavior, driven by greed and social proof, frequently leaves latecomers holding the bag when early investors cash out.
Panic Selling: Conversely, when a broad market correction hits, the sudden plunge triggers an acute survival response. Investors panic-sell at the absolute market bottom, permanently locking in temporary paper losses that would have recovered had they stayed the course.
Trading without an emotional buffer turns the stock market into a high-stakes casino where your own psychology acts as the house edge working against you.
2. Mistaking Activity for Strategy: The Danger of Overtrading
Another silent portfolio killer is the compulsion to constantly tinker. Many participants assume that being an active investor means executing trades every single day. They scan charts hourly, jump on breaking news headlines, and rotate positions chasing short-term momentum.
This constant motion rarely equates to mastery.
3. The Fatal Flaw of Poor Risk Management
Ask ten people why a specific stock lost money, and nine will talk endlessly about the company's valuation, charts, or macroeconomics. They will rarely talk about position sizing—and that is precisely where the game is lost.
Risk management is not about predicting whether a stock will go up or down; it is about ensuring that when you are wrong, the financial damage is controlled and localized. Amateur investors frequently commit capital haphazardly, putting large chunks of their net worth into high-beta, speculative names without predefined exit boundaries.
When a position drops 20% or 30%, a poorly sized trade can inflict a structural deficit that requires an impossibly high percentage gain just to break even. Protecting your baseline capital is the prerequisite for all future compounding; once capital is heavily depleted, the mathematical climb back becomes exponentially harder.
Overcoming the Psychological and Strategic Traps of Market Losses
To successfully stem the bleeding in your investment portfolio, it is vital to look past short-term market noise and evaluate the structural errors that often cause capital erosion. Building upon the foundational realization that individual stock picking and emotional reactions frequently sabotage long-term performance, let us examine how to restructure your approach and transition toward sustainable, disciplined wealth building.
The Danger of Chasing High-Flying Trends
One of the most persistent reasons investors watch their balances shrink is the temptation to buy assets that have already experienced massive, parabolic runs.
The Fear of Missing Out (FOMO): When a specific sector, company, or trendy asset surges into public consciousness, media hype creates an intense psychological pull.
Buying at the Peak: Retail investors frequently enter these positions right as institutional smart money is beginning to take profits. Consequently, they buy near the absolute top, leaving them vulnerable to steep corrections when momentum inevitably shifts.
"A popular stock is rarely a bargain. Paying an inflated price for a business—no matter how exceptional that business might be—severely restricts your future return potential."
The Hidden Drag of Fees, Taxes, and Friction
Many investors meticulously track market movements while completely ignoring the invisible leaks draining their accounts from underneath:
Excessive Portfolio Turnover: Frequent buying and selling triggers transaction fees, commissions, and short-term capital gains taxes. Every time you trade, you pay a toll that slowly chips away at your principal.
High Expense Ratios: Actively managed funds often carry high management expense ratios (MERs) that eat into your returns year after year, frequently underperforming simple, low-cost index funds over long horizons.
Constructing a Resilient Action Plan
If your portfolio has taken a beating, abandoning the market entirely or chasing quick recovery trades will usually compound your errors.
Step 1: Conduct a Portfolio Audit: Review every holding to determine whether you bought it based on a robust long-term business thesis or merely on a short-term impulse or internet tip.
Step 2: Embrace Broad Diversification: If your losses stem from holding just two or three volatile individual stocks, pivot your focus toward diversified index funds or exchange-traded funds (ETFs) that track major, multi-industry market segments.
Step 3: Automate Your Strategy: Implement dollar-cost averaging (DCA). By investing a fixed amount at regular, scheduled intervals regardless of market conditions, you remove emotion from the equation and automatically buy fewer shares when prices are high and more shares when prices are low.
Step 4: Define a Written Investment Policy: Outline your time horizon, maximum risk tolerance, and asset allocation goals before allocating new capital. Having a written rulebook prevents panic selling during inevitable market downturns.
Shifting Your Mindset for the Long Haul
Ultimately, wealth accumulation in the stock market is a test of temperament rather than raw intellect. Markets naturally fluctuate, and temporary drawdowns are a standard cost of admission for achieving higher long-term returns than cash or traditional savings accounts can offer.
By shifting your perspective away from daily ticker changes and focusing instead on business fundamentals, asset allocation, and cost control, you can transform past losses into invaluable lessons—turning your portfolio into a resilient engine for long-term financial security.
What specific asset class or investment strategy has caused you the most concern in your portfolio recently?