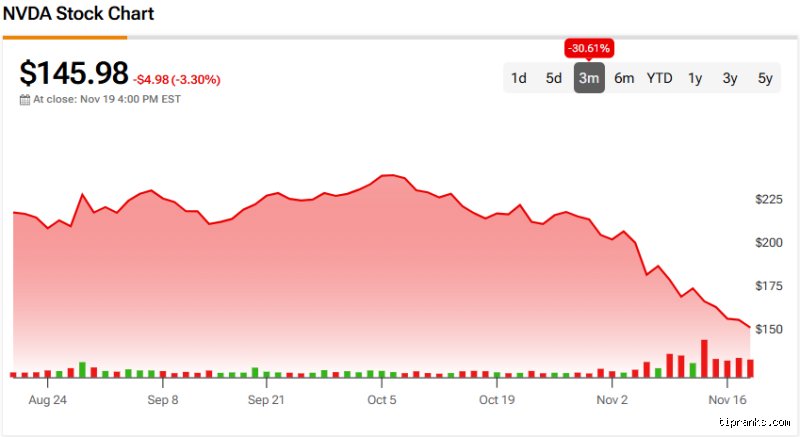
Navigating the crucible: Is Nvidia stock still a Hold in the new AI landscape?
However, the market environment of late 2026 presents a vastly more complex tapestry. Following a turbulent stretch defined by significant stock price compression, heightened macroeconomic scrutiny, and unexpected corporate governance headlines—including the departure of Jensen Huang and interim leadership under Chief Financial Officer Colette Kress—investors are forced to re-evaluate the core thesis. Amidst this backdrop, Wall Street opinion remains deeply fragmented. While a substantial majority of analysts maintain constructive buy ratings with ambitious long-term price targets, a persistent faction argues for a "Hold" posture. To determine whether Nvidia stock truly remains a Hold, or if the recent sell-off has quietly transformed a high-risk darling into a generational value opportunity, one must deconstruct the interplay between macroeconomic infrastructure spending, valuation multiple contraction, escalating competitive pressures, and the execution risk of a post-founder leadership transition.
The fundamental strength: Operational resilience and unrivaled Financial velocity
To understand why many institutional investors continue to advocate for holding or accumulating Nvidia shares rather than abandoning the thesis, one must first confront the sheer gravity of the company's financial performance. Skeptics frequently attempt to frame the cooling of stock price momentum as evidence of an imminent collapse in fundamental demand. Yet, recent quarterly disclosures paint a radically different picture, one characterized by exceptional operational momentum and robust cash generation.
Nvidia’s fiscal results continue to defy historical precedent for a technology enterprise of its trillion-dollar scale. Revenue on a trailing basis has more than doubled year-over-year, propelled by relentless demand across the data center ecosystem. Far from showing signs of structural exhaustion, the enterprise and cloud infrastructure markets continue to expand. Major hyperscale cloud providers, the foundational pillars of the capital expenditure boom, accelerated their deployments, reporting sequential multi-percentage gains in cloud infrastructure spending. Simultaneously, the sovereign AI and enterprise vertical markets have begun to scale, demonstrating that demand is diversifying well beyond a concentrated cohort of U.S. mega-cap technology firms.
Profitability metrics remain the envy of the global semiconductor industry. Despite mounting supply chain commitments and the introduction of complex, next-generation architectures, Nvidia’s gross margins have consistently outperformed conservative guidance bands. The company's ability to maintain adjusted gross margins near the mid-70% threshold underscores an extraordinary degree of structural pricing power. When combined with disciplined operating expense management, this pricing power translates directly into explosive free cash flow generation, surging nearly 100% year-over-year to multi-billion-dollar quarterly figures.
For the long-term holder, these fundamentals provide an immense margin of safety. A company capable of generating massive cash flows while growing top-line revenue at high double-digit rates is fundamentally distinct from the cyclical, low-margin hardware suppliers of previous computing eras. From this viewpoint, the stock represents an essential core holding; the underlying engine of the AI hardware stack remains intact, operating at maximum capacity, and printing cash regardless of near-term market sentiment fluctuations.
Valuation compression: Have shares reached an undervalued inflection point?
One of the most compelling arguments put forward by proponents of a bullish or holding stance is the dramatic compression of Nvidia’s valuation multiples. Throughout its parabolic ascent in 2023 and 2024, critics regularly pointed to the company's lofty price-to-earnings (P/E) ratio as a primary deterrent, arguing that perfection was heavily priced into the equity.
Fast forward to late 2026, and the valuation landscape has undergone a tectonic shift. Driven by a sharp correction in the stock price, brought on by a combination of broader tech sector rotation and company-specific governance shocks, Nvidia’s valuation multiples have compressed to multi-year lows. In fact, trailing and forward P/E multiples have dipped significantly below their historical averages from preceding years, rivaling cyclical troughs seen during previous semiconductor downturns.
When evaluating these compressed multiples against projected earnings growth, a fascinating paradox emerges. While consensus estimates point toward robust top- and bottom-line expansion for the upcoming fiscal years, the stock trades at a forward P/E multiple that is a fraction of its historical three-year average. In historical terms, it is exceedingly rare to find a market leader experiencing structural secular growth trading at valuation levels typically ascribed to mature, slow-growing industrial hardware firms.
This valuation compression creates a bifurcated psychological environment for investors:
The Value-Driven Buyer perceives the drawdown as an aggressive market overreaction, arguing that compressed multiples provide a unique entry point or accumulation zone for long-term wealth creation.
The Cautious Holder, however, interprets the compression as a rational market adjustment. They argue that multiple contraction often precedes a structural deceleration in growth rates, signaling that Wall Street is beginning to price in the inevitable law of large numbers and cyclical saturation.
Macro-Commitments and capital expenditure risks: The 390 billion dollar question
Despite the comfort offered by compressed valuation multiples and strong near-term earnings beats, a rational "Hold" thesis must carefully weigh the mounting structural risks facing the enterprise. Chief among these is the unprecedented escalation of Nvidia’s contractual purchase commitments and supply chain obligations.
Recent balance sheet disclosures reveal that Nvidia’s purchase commitments, primarily driven by multi-year supply agreements for advanced packaging, high-bandwidth memory (HBM), and specialized components required for next-generation AI accelerators, have surged dramatically, reaching hundreds of billions of dollars. Simultaneously, obligations tied to cloud service agreements and data center infrastructure leases have expanded exponentially.
While these extensive contractual obligations are necessary to secure the scarce supply required to meet global AI demand, they introduce a profound structural vulnerability:
Operating Leverage Risk: High fixed commitments mean that any unexpected, sharp deceleration in end-market demand or capital expenditure spending by hyperscalers could quickly pressure operating margins.
Customer Concentration and ROI Scrutiny: As major cloud providers and enterprise buyers spend tens of billions of dollars annually on AI infrastructure, corporate boards across the global economy are increasingly demanding measurable return on investment (ROI). If enterprise adoption of generative AI applications fails to monetize at a pace that justifies these staggering infrastructure outlays, a cyclical pause or pullback in data center capital expenditures becomes a tangible threat.
Thus, while Nvidia’s order book remains full and forward guidance remains robust, the sheer magnitude of its financial commitments ties its fortunes tighter than ever to the macro-economic health of the broader technology sector's capital allocation cycle.
Navigating the volatility: The fundamental case for patient capital
As the artificial intelligence infrastructure race matures, the debate surrounding Nvidia Corporation (NASDAQ: NVDA) has shifted from unbridled enthusiasm to a rigorous stress-test of its long-term moat. With recent quarters continuing to display staggering top-line acceleration, highlighted by fiscal third-quarter revenues surging past $115 billion, the underlying enterprise engine remains robust. Yet, recent executive transitions, evolving macroeconomic pressures, and intense industry scrutiny have left many market participants questioning whether to accumulate, trim, or maintain their positions.
For investors currently evaluating their portfolio exposure, the designation of a "Hold" is far from a neutral or passive stance. Rather, it represents a strategic decision to honor the exceptional cash-generating power of the business while respecting structural headwinds that warrant disciplined risk management.
Margin resilience versus competitive pressures
A primary concern for analysts evaluating Nvidia’s intermediate-term trajectory centers on gross margin sustainability. Skeptics frequently argue that as major cloud service providers (hyperscalers) design proprietary application-specific integrated circuits (ASICs) and alternative merchant silicon providers scale their offerings, Nvidia’s unprecedented pricing power will inevitably face erosion.
However, recent financial disclosures tell a remarkably resilient story:
Operating Efficiency: Non-operating income and net margins continue to benefit from unmatched software ecosystem lock-in via CUDA, creating a sticky developer environment that hardware alternatives struggle to replicate.
Platform Transitions: The commercial rollout and scaling of advanced computing architectures, such as the Vera Rubin platforms, demonstrate that Nvidia is not merely selling standalone graphics cards, but deeply integrated data center solutions.
Free Cash Flow Generation: With quarterly free cash flows reaching historic highs, the company retains enormous financial flexibility to fund internal research and development while aggressively returning capital to shareholders through buybacks and dividends.
Despite these formidable strengths, valuation multiples remain sensitive to sentiment shifts. When market sentiment fluctuates due to external headlines or sudden shifts in tech-sector leadership, even minor contractions in forward multiple expansions can stall stock price appreciation, making a "Hold" rating the most sensible posture for existing shareholders who wish to avoid overexposure during digestion phases.
The shift from training to inference
Another critical dimension in the ongoing "Hold vs. Buy/Sell" debate involves the structural evolution of enterprise AI workloads. Historically, Nvidia’s dominance was built on the massive computational requirements of training frontier large language models. As the industry matures, a larger proportion of corporate AI spending is shifting toward inference, the execution phase where models run live queries for end-users.
While inference places different demands on hardware architecture, sometimes opening doors for specialized CPUs or alternative accelerators, Nvidia’s hardware versatility ensures it remains a dominant force across both paradigms. Nevertheless, the transition introduces architectural complexities and heightens the importance of execution from incoming leadership. Investors maintaining a hold position allow themselves the necessary time to observe how smoothly these operational handoffs occur without subjecting their capital to the binary risks of aggressive new-position accumulation during periods of transition.
Strategic portfolio considerations: Why "Hold" wins for now
Deciding to hold Nvidia stock requires balancing extraordinary secular tailwinds against short-term volatility factors:
Tax Efficiency and Long-Term Horizon: For long-term shareholders sitting on substantial capital gains, premature liquidation triggers unnecessary tax liabilities. Maintaining a core holding allows investors to compound wealth through secular AI adoption without interrupting the tax-advantaged compounding of their initial capital.
Execution Risk Mitigation: Leadership evolution and shifting global trade dynamics introduce headline risks that can cause sharp, temporary intraday and multi-week pullbacks. A hold strategy insulates investors from emotional knee-jerk selling while keeping them fully anchored to the company's elite operating margins.
Core Allocation Discipline: For portfolios where Nvidia has naturally grown into an outsized percentage due to past appreciation, holding, paired with disciplined rebalancing if weightings become overly concentrated, ensures that risk parameters remain aligned with individual financial goals.
Patience as an Advantage
Nvidia remains the undisputed backbone of modern accelerated computing, backed by financial metrics that few corporate entities in history have ever achieved. But the sheer scale of its operations means that future percentage gains will require flawless execution, sustained enterprise IT spending, and the successful navigation of complex global headwinds.
For investors already holding shares, maintaining discipline, monitoring upcoming earnings guidance for sustained free cash flow growth, and letting the business fundamentals work over a multi-year horizon remains the most prudent path forward. The underlying technology titan is far from finished, but respecting the current cycle of consolidation ensures that your portfolio remains as resilient as the hardware driving the next generation of computing.