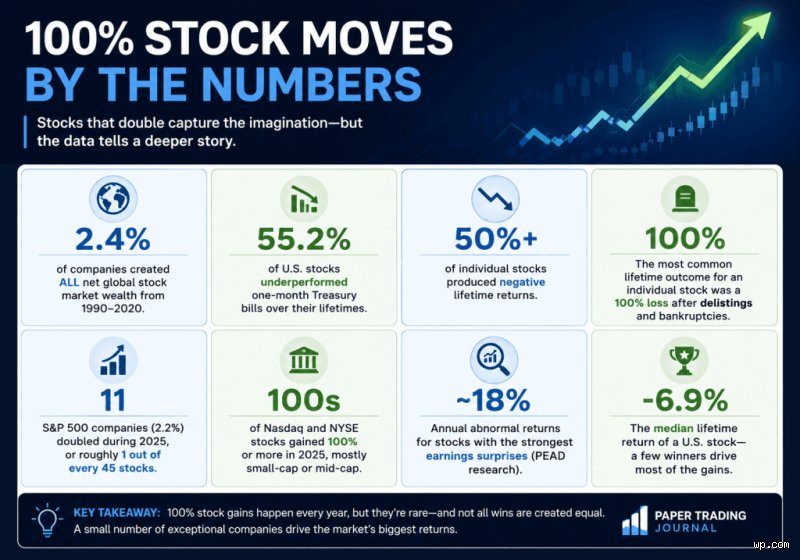
True financial analysts and portfolio managers approach the question—“Which stock will double?”, not as a random lottery ticket selection, but as a rigorous exercise in mathematical probability, structural business analysis, and valuation forensics. A stock does not double because of hope; it doubles because its underlying intrinsic value expands aggressively, forcing the market to re-price the enterprise to reflect a vastly superior financial reality.
To understand how equities achieve a 100% return, we must deconstruct the financial mechanics of price appreciation, examine the gravitational pull of market capitalization, and map out the structural catalysts that separate generational compounders from permanent capital traps.
1. The mathematics of doubling: Revenue, Margins, and multiples
At its core, a stock’s market price is a product of two distinct variables: earnings per share (EPS) and the price-to-earnings (P/E) multiple that the market is willing to assign to those earnings (Price=EPS×P/EPrice = EPS imes P/EPrice=EPS×P/E). Therefore, for a stock to double, one of three things must happen:
Earnings double while the valuation multiple remains completely flat.
The valuation multiple doubles while earnings remain completely flat (pure multiple expansion or speculative re-rating).
A synergistic combination of both earnings growth and multiple expansion occurs, where earnings grow by 40% and the multiple expands by 40%, compounding to deliver the 100% total return.
Relying purely on multiple expansion is a dangerous game. When investors buy a stagnant business simply because its P/E ratio expands from 15x to 30x, they are engaging in the "Greater Fool Theory", betting that someone else will pay an even more absurd price down the line. Sustainable, repeatable equity doubling is almost always driven by fundamental operational growth, where revenue expansion unlocks operating leverage, causing net income to outpace top-line growth significantly.
The triple engine of outperformance
When screening for businesses capable of doubling, professional analysts look for companies firing on three specific cylinders:
Secular Top-Line Expansion: The company operates in a growing Total Addressable Market (TAM) where organic demand outpaces global GDP growth by several multiples. Whether it is enterprise cloud migration, advanced semiconductor packaging, cybersecurity automation, or next-generation healthcare logistics, top-line revenue must compound at 15% to 25% annually.
Operating Leverage: As the business scales, fixed costs (such as corporate overhead, software infrastructure, and foundational R&D) remain relatively stable while gross profits climb. This dynamic causes operating margins to widen year-over-year, turning a 20% revenue growth rate into a 40% earnings growth rate.
Reinvestment Runaway: The management team does not need to return all capital immediately via dividends; instead, they possess high-return internal projects or bolt-on acquisition strategies where every dollar reinvested generates a high Return on Invested Capital (ROIC).
2. Market capitalization gravity: Why size matters
One of the most common mistakes novice investors make is ignoring the laws of corporate physics. Market capitalization is the ultimate gravitational force in equity markets.
Consider the sheer economic scale required for a company to double its share price:
If a mega-cap technology titan valued at $2 trillion doubles, it must add another $2 trillion in net enterprise value, roughly equivalent to creating an entirely new corporation the size of Apple or Amazon from scratch within a short span of time. While possible over long multi-decade horizons, achieving a rapid 100% return from a $2 trillion baseline requires macroeconomic shifts of unimaginable proportions.
Conversely, take a high-quality small-cap or mid-cap enterprise valued at $2 billion. For this company to double, it must add just $2 billion in market value. In a globalized economy with trillions of dollars in institutional liquidity moving fluidly across borders, a well-managed mid-cap company capturing market share in a high-growth niche can achieve a $4 billion valuation with relative operational agility.
The sweet spot: The billion to billion band
Historically, empirical market studies demonstrate that the highest frequency of "baggers", stocks that double, triple, or quadruple over a 3-to-5-year window, resides in the small-to-mid-cap tier ($2B to $20B valuation).
At this scale, companies have already survived the existential risks of early-stage startups; they have proven product-market fit, positive operating cash flow, and established customer retention. Yet, they remain entirely under the radar of massive index funds, pension pools, and Wall Street sell-side analysts who cannot take meaningful positions in micro-caps due to liquidity constraints. When a $5 billion company executes brilliantly, institutional accumulation can cause the stock price to re-rate aggressively, driving rapid appreciation.
3. Structural moats and Secular Tailwinds: Separating signal from noise
A company cannot double its intrinsic value unless it possesses a sustainable competitive advantage, what legendary investor Warren Buffett famously termed an economic moat. Without a moat, high gross margins inevitably attract fierce competition, driving prices down and crushing profitability.
When evaluating potential candidates for explosive appreciation, look for these four classic moat archetypes:
Network Effects: Platforms where the value of the service increases exponentially for every new user who joins. Think of global digital marketplaces, payment networks, or specialized B2B workflow ecosystems where switching costs are prohibitively high.
High Switching Costs: Software, data infrastructure, or enterprise hardware integration that is so deeply embedded into a client's daily operations that migrating to a competitor risks catastrophic operational downtime.
Cost Advantages & Scale Economies: Supply chain dominance, proprietary manufacturing processes, or vertically integrated logistics networks that allow a company to underprice competitors while maintaining superior operating margins.
Intangible Assets: Regulatory approvals, specialized patents, deep intellectual property portfolios, or powerful brand equity that legally or culturally locks out new entrants.
Aligning with Secular Mega-Trends
Equities rarely double in stagnant industries. To find a 100% winner, you must fish in ponds where the water level is rising. Current secular mega-trends driving asymmetric upside include:
The Artificial Intelligence Infrastructure Stack: Beyond consumer-facing software wrappers, the picks-and-shovels providers, advanced silicon designers, high-end lithography equipment makers, specialized cooling systems, and hyper-scale data center operators, are experiencing unprecedented demand elasticity.
Cybersecurity Consolidation: As threat vectors multiply and automated attacks become standard, enterprises are moving away from fragmented point solutions and consolidating their security spend onto unified, AI-driven platforms.
Advanced Healthcare & Contract Biomanufacturing: Genomic sequencing, targeted biologics, and specialized contract development and manufacturing organizations (CDMOs) locked into long-term pharmaceutical pipelines provide predictable, high-margin cash flow growth.
4. Avoiding the Value Trap and the Hype Illusion
In the quest to double capital, investors frequently fall into two psychological traps: Value Traps and Hype Bubbles.
A Value Trap occurs when a stock appears astonishingly cheap, trading at a P/E ratio of 5x or 6x, but is cheap for a structural reason. The underlying business model is declining, disrupted by technological obsolescence, or facing secular contraction. Buying a dying retailer or a commoditized industrial manufacturer just because it is cheap rarely leads to a double; more often, it leads to a permanent loss of capital as earnings evaporate.
On the other end of the spectrum is the Hype Illusion. This is the speculative frenzy surrounding early-stage companies with zero revenue, astronomical valuations, and grandiose promises of future disruption. While these stocks can spike violently on market sentiment, they are highly fragile. When macroeconomic conditions tighten or interest rates rise, speculative froth evaporates first, leaving retail investors holding massive unrealized losses.
True wealth creation requires balancing growth potential with financial resilience. The ideal candidate maintains positive operating cash flow, manageable debt levels, and a pristine balance sheet that allows it to invest aggressively through economic downturns while weaker competitors go bankrupt.
Looking ahead: The screening methodology
Having established the foundational economic framework, mathematical realities, and structural guardrails required for an equity asset to double, the next logical step is to operationalize this knowledge.
In the second part of this expert analysis, we will transition from theory to practice. We will explore quantitative screening criteria, examine specific financial ratios that signal impending momentum, outline portfolio risk-management protocols, and review case studies of how top-tier institutional investors vet asymmetric opportunities in today's dynamic macroeconomic environment.
The anatomy of a doubling stock: Beyond the Hype
When investors ask, "Which stock will double?" they are usually hunting for the holy grail of equity research: the elusive multibagger. While media headlines frequently spotlight speculative micro-caps or overnight tech sensations that skyrocket by 100% in weeks, sustainable capital appreciation requires a rigorous framework. Doubling a stock’s price is not merely a function of luck; it is a mathematical outcome driven by expanding earnings, structural tailwinds, pricing power, and an initial valuation that leaves room for multiple expansion.
In this continuation of our expert analysis, we move past superficial stock-picking to explore the quantitative filters, qualitative catalysts, and macroeconomic environments that separate a true wealth-building compounder from a classic value trap.
1. The core mathematics of a 100% Return
To understand how a stock doubles, we must first break down the fundamental driver of long-term equity performance: Total Shareholder Return (TSR). Mathematically, a stock price (PPP) is a product of its Earnings Per Share (EPSEPSEPS) and its Price-to-Earnings (P/EP/EP/E) multiple:
P=EPS×P/EP = EPS imes P/EP=EPS×P/E
For a stock to double (2P2P2P), one of three scenarios must occur:
Pure Earnings Growth (EPS×2EPS imes 2EPS×2): Earnings double while the valuation multiple remains entirely flat. This is the gold standard of investing, characteristic of high-margin software companies, dominant platforms, and secular growth leaders.
Multiple Expansion (P/E×2P/E imes 2P/E×2): Earnings remain completely flat, but market sentiment shifts dramatically, doubling the valuation multiple. This is speculative, risky, and prone to sharp reversals.
The Hybrid Approach: Moderate earnings growth combined with modest multiple re-rating (e.g., a 40% increase in earnings coupled with a 45% expansion in the P/E ratio).
Expert analysts prioritize companies driving their trajectory through Scenario 1 or a healthy Scenario 3. Relying strictly on multiple expansion is a dangerous game that leaves portfolios vulnerable to macroeconomic shocks.
2. Key characteristics of High-Probability doublers
When scanning global markets for candidates capable of achieving a 100% gain over a realistic investment horizon (typically 3 to 5 years), professional portfolio managers look for four non-negotiable pillars:
High Return on Invested Capital (ROIC): Companies that generate superior returns on every dollar they reinvest into their business do not need external financing to grow. They compound intrinsic value organically.
Secular Tailwinds Over Cyclicality: Businesses tied to structural megatrends, such as artificial intelligence infrastructure, next-generation cybersecurity, clean energy grid modernization, or digital transformation in emerging markets, possess an external tailwind that lifts all corporate boats.
Unimpeachable Pricing Power: In an inflationary environment, companies that can raise prices by 5% to 10% without losing customer volume protect their operating margins and guarantee bottom-line expansion.
Operational Scalability (High Gross Margins): Initial costs may be heavy, but incremental revenue should cost very little to produce. Software-as-a-Service (SaaS), select semiconductor designers, and asset-light platform aggregators excel here.
3. Case studies: Where the Growth hides
While no single stock can be guaranteed to double, observing historical market behaviors reveals distinct sectors where these ingredients frequently converge:
A. The Infrastructure & hardware backbone
The massive capital expenditures flowing into artificial intelligence and data center scaling have turned select hardware and semiconductor providers into earnings powerhouses. Companies providing specialized silicon, optical networking components, and power management solutions often experience sudden, explosive inflections in net income that outpace Wall Street's forward estimates.
B. Beaten-Down disruptors with proven units
Occasionally, a high-growth category leader suffers a temporary drawdown due to macroeconomic headwinds, regulatory noise, or compressed sector valuations. When a company's underlying key performance indicators (KPIs), such as active user growth, net retention rates, and free cash flow generation, continue to trend upward while the stock price sits stagnant or lower, the compression creates a coiled spring effect.
4. Managing risk and portfolio Sizing
Chasing 100% returns inherently involves elevated volatility. A balanced approach requires disciplined risk management:
Position Sizing: Never allocate an outsized portion of a core portfolio to high-beta, growth-oriented candidates. Limit speculative high-growth holdings to a satellite allocation that you can comfortably manage through market drawdowns.
Thesis Tracking: Monitor quarterly execution rather than daily stock price fluctuations. If revenue growth remains robust, unit economics improve, and management executes on capital allocation, short-term market apathy is merely noise.
Patience Over speculation
Finding a stock that will double is less about finding a secret ticker and more about mastering financial discipline. By focusing on exceptional business models, robust cash generation, and reasonable entry valuations, investors position themselves to capture extraordinary returns without resorting to blind speculation.