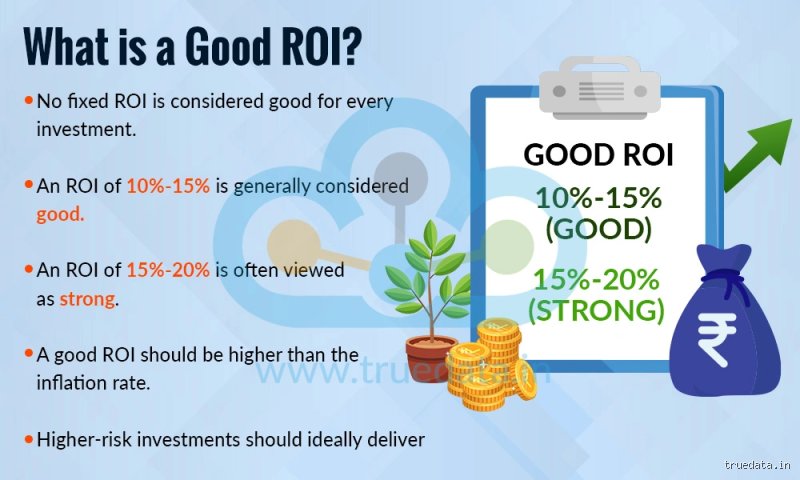
Yet, for all its mathematical simplicity, the question—"What is considered a bad ROI?", is deceptively complex.
Ask a venture capitalist investing in early-stage biotech startups, a digital marketer running performance ads, a real estate mogul buying multi-family units, and a conservative retiree managing dividend stocks, and you will get four wildly different answers. To one, a 15% return is a catastrophic failure; to another, it is a phenomenal success.
Understanding what constitutes a "bad" ROI requires stripping away the simplistic rule of thumb that "anything above zero is good" and examining the intricate interplay of opportunity cost, risk profiles, time horizons, industry benchmarks, and inflation.
1. The fundamental baseline: The mathematics of loss and Break-Even
To understand what makes an ROI bad, we must first ground ourselves in the basic formula. At its core, Return on Investment is calculated as:
ROI=Net ProfitCost of Investment×100 ext{ROI} = \frac{ ext{Net Profit}}{ ext{Cost of Investment}} imes 100ROI=Cost of InvestmentNet Profit×100
When you run this calculation, you generally fall into one of three psychological and financial zones:
Positive ROI (> 0%): You made more money than you put in. Your investment generated a net profit.
Zero ROI (0%): You broke even. You recouped your exact principal, but earned zero net gain.
Negative ROI (< 0%): You lost money. Your final value is less than your initial outlay.
The absolute definition of "bad": Negative returns
From a purely literal standpoint, any negative ROI is a bad ROI because it represents the destruction of capital. If you invest $10,000 into a project and walk away with $8,000, your ROI is -20%. You have lost $2,000 of hard-earned money.
However, seasoned investors and corporate executives know that capital destruction is only the most obvious symptom of a bad investment. Far more insidious are investments that yield a positive ROI that is nevertheless considered disastrously poor when placed in its proper context.
2. The illusion of green: Why a positive ROI can still be "bad"
One of the most common traps for novice investors and business owners is celebrating any return greater than zero. If a project generates a 3% ROI over the course of a year, it is easy to view it as a win because "money was made."
In professional finance, however, an investment is evaluated not in a vacuum, but against alternative uses of capital. This brings us to two critical concepts: Inflation and Opportunity Cost.
The Inflation Trap
Inflation is the silent tax on purchasing power. If your investment generates a nominal ROI of 3% over a year, but the annual inflation rate sits at 4%, your real ROI is actually negative (-1%).
Real ROI≈Nominal ROI−Inflation Rate ext{Real ROI} \approx ext{Nominal ROI} - ext{Inflation Rate}Real ROI≈Nominal ROI−Inflation Rate
While your account balance may show a slightly larger number at the end of the year, you can actually buy less with that money than you could twelve months prior. Any investment whose ROI fails to outpace the rate of inflation is, by definition, a bad investment over the long term because it results in a net loss of real purchasing power.
The Opportunity Cost benchmark
Beyond inflation lies the hurdle of opportunity cost. Every dollar you deploy into Project A is a dollar you cannot deploy into Project B, C, or a risk-free benchmark like U.S. Treasury bonds or a broad-market index fund (such as the S&P 500).
Historically, the S&P 500 has delivered an annualized historical average return of roughly 8% to 10% (before adjusting for inflation). Therefore, if you tie up your capital in a private business venture, a real estate flip, or a marketing campaign that yields a steady 4% ROI, you have actually achieved a bad ROI relative to the market. Why take on the massive operational risk, liquidity constraints, and stress of running a business project for a 4% return when you could have achieved double that return passively by buying an index fund with virtually zero effort?
In professional capital allocation, if an investment fails to clear your hurdle rate, the minimum rate of return required to justify the risk, it is classified as a bad ROI, regardless of whether it printed a positive nominal number.
3. Industry context: One man’s trash is another man’s treasure
What is considered "bad" varies dramatically depending on the sector, asset class, and inherent risk profile of the venture. You cannot evaluate a high-growth tech startup using the same yardstick you use for a municipal bond or a commercial strip mall.
High-Risk, High-Reward: Venture Capital and startups
In the world of venture capital (VC) and angel investing, the risk profile is astronomical. Statistically, roughly 75% to 90% of early-stage startups fail completely, resulting in a -100% ROI.
Because investors are taking on total-loss risk, a 10% or 20% ROI is not just "bad", it is considered a complete failure that ruins the fund's economics. Venture capitalists operate under a "power law" model where they expect out of a portfolio of ten startups:
6 to 7 total write-offs (-100% ROI)
2 mediocre returns (1x to 3x ROI)
1 to 2 massive home runs (10x to 100x+ ROI)
If a startup returns a modest 15% over three years, it is viewed as a bad outcome because it failed to cover the catastrophic losses absorbed by the rest of the portfolio. In VC, any investment that does not target a minimum 20% to 30% IRR (Internal Rate of Return) or a 10x multiple over its lifespan is generally rejected at the underwriting stage.
Real Estate: Stability and cash flow
Conversely, in real estate investing, the risk profile and leverage dynamics are entirely different. Real estate investors often utilize debt (mortgages) to amplify their equity returns.
In residential or commercial real estate:
An annual cash-on-cash return below 5% is frequently considered poor, especially in a high-interest-rate environment where safe high-yield savings accounts or CDs might offer comparable yields with zero landlord headaches.
A double-digit cash-on-cash return (10% to 15%+) paired with solid property appreciation and principal paydown is generally considered healthy and successful.
However, if a fix-and-flip project nets an ROI under 15% to 20% after accounting for holding costs, renovation overruns, realtor fees, and unexpected structural defects, experienced flippers consider it a bad ROI because the profit margin was too thin to justify the immense stress and execution risk.
Corporate finance and Capital expenditures (CapEx)
When a Fortune 500 company evaluates whether to build a new factory, acquire a competitor, or launch a new product line, they calculate their WACC (Weighted Average Cost of Capital). WACC represents the average rate a company expects to pay to finance its assets through debt and equity.
If a company’s WACC is 8%, any internal project with an ROI below 8% destroys shareholder value. Even an ROI of 9% might be deemed unacceptably bad when weighed against the execution risk and the opportunity cost of alternative corporate initiatives. In corporate finance, a "good" ROI must comfortably exceed the cost of capital to create genuine economic value.
4. The time horizon factor: Speed matters
Time is the fourth dimension of ROI. A numerical return cannot be judged in isolation from how long it took to achieve that return.
Consider two investments:
Investment A: Generates a 20% ROI over 1 year.
Investment B: Generates a 20% ROI over 10 years.
Investment A is phenomenal. Investment B is mathematically abysmal. Spread over a decade, a total 20% return translates to an annualized compound growth rate (CAGR) of roughly 1.84% per year, far below inflation and bank deposit rates.
When evaluating what makes an ROI bad, professionals rely heavily on Annualized ROI or Internal Rate of Return (IRR). If an investment ties up your liquidity for years while delivering meager annualized gains, the opportunity cost makes it a glaring failure.
(This concludes Part 1 of our expert analysis on what constitutes a bad ROI. In Part 2, we will examine specific departmental benchmarks, including digital marketing ad spend, employee training programs, and personal finance milestones, alongside actionable frameworks for auditing your own investments to weed out underperforming assets before they drain your portfolio.)
... [Continuation from previous analysis of baseline metrics and basic calculations]
Industry-Specific failures: Where "good" and "bad" diverge
A critical error in financial analysis is applying a blanket percentage threshold across entirely different sectors. What constitutes a catastrophic return in one arena might be acceptable, or even standard, in another. To accurately identify a bad ROI, you must calibrate your expectations against sector-specific realities, regulatory constraints, and inherent risk profiles.
Marketing and Customer Acquisition: Marketing is uniquely high-variance. Because campaigns directly target revenue generation with immediate, measurable spend, benchmarks are steep. In digital marketing and paid acquisition, an ROI below 100% (meaning you fail to double your initial ad spend to cover gross margins and overhead) is generally classified as underperforming. An absolute negative ROI or anything below 50% points to severe target-audience misalignment, broken conversion funnels, or messaging fatigue.
Capital Business Investments (Equipment & Tech): When a firm allocates capital toward enterprise software, automated machinery, or structural expansions, the threshold is anchored to the Weighted Average Cost of Capital (WACC). If a company’s cost of borrowing or raising capital is 8%, and an operational upgrade yields a sluggish 4% ROI, that investment is value-destructive. Even though the return is positive on paper, it actively erodes shareholder value because the company is paying more to finance the initiative than the initiative is generating in return.
Real Estate (Rental Properties & Flips): In real estate, leverage and liquidity play massive roles. For a long-term rental property, a net cash-on-cash return falling below 4% to 5% is widely considered poor, especially when weighed against the illiquidity of the asset, property management headaches, maintenance liabilities, and prevailing risk-free interest rates. For property flips, where capital is tied up under high-stress renovation timelines, an ROI dropping below 10% signals a failed project, as it rarely compensates for unforeseen construction overruns and market shifts.
The invisible killers: Nominal vs. Real ROI
One of the most dangerous misconceptions in finance is assuming that any positive ROI is, by definition, a "good" or acceptable outcome. In reality, a nominally positive return can mask a deeply bad financial result when exposed to macroeconomic pressures.
1. Inflationary Erosion
If an investment generates a nominal ROI of 3% over a given year, but the national inflation rate sits at 4% or higher, your purchasing power has diminished. Your nominal profit is positive, but your real ROI is negative. Failing to account for inflation means celebrating a loss disguised as a gain.
2. The Opportunity Cost penalty
Money is finite, and every dollar deployed into Project A represents dollars withheld from Projects B, C, or a risk-free benchmark. Suppose a corporate treasury allocates funds to an internal initiative yielding a 5% return. If those same funds could have effortlessly captured an average historical equity market return of 9% to 10% or sat in a high-yield treasury instrument with zero operational risk, that 5% return is a bad ROI. It represents an opportunity cost penalty, the silent bleeding of potential wealth.
The psychological trap: Sunk Cost fallacy and "zombie Investments"
Recognizing a bad ROI mathematically is only half the battle; the harder part for decision-makers is acknowledging it psychologically. Human psychology is heavily prone to the sunk cost fallacy, the tendency to continue investing resources into a failing project simply because a substantial amount of time, money, and emotional capital has already been spent.
In corporate environments, bad ROIs often morph into "zombie projects." These are initiatives that bleed capital month after month, generating negligible or negative returns, yet persist because no executive wants to admit initial failure. To combat this, elite organizations institute strict hurdle rates and automated review gates. If a project fails to clear specific milestone-based ROI thresholds within a defined grace period, it is systematically restructured or terminated, freeing up capital for high-velocity opportunities.
Strategic remediation: What to do When ROI goes south
Discovering that an asset, campaign, or business unit is generating a bad ROI should not induce panic; rather, it should serve as a strategic trigger for action. When confronted with poor returns, management teams and investors generally have three viable paths:
The Operational Pivot (Optimization): If the core premise of the investment is sound but execution is flawed, dissect the cost-to-revenue ratio. Are customer acquisition costs too high? Are operational inefficiencies eating margins? Streamlining processes can rescue a marginal ROI and push it into profitable territory.
The Strategic Divestment (Kill Switch): If structural headwinds, shifting market dynamics, or permanent technological obsolescence make recovery impossible, cut your losses. Liquidate the asset, reallocate remaining capital, and redeploy it where yields align with your hurdle rate.
The Risk-Adjusted Rebalancing: Sometimes a bad ROI is simply a symptom of mispriced risk. If an investment carries high volatility but yields low-tier returns, restructure the capital stack or hedge the exposure to protect the baseline.
Redefining value beyond the percentage
Determining whether an ROI is "bad" requires stepping back from the isolated spreadsheet cell and looking at the broader ecosystem. A bad ROI is not merely a negative number; it is any return that fails to justify the risk assumed, falls short of your cost of capital, loses ground to inflation, or squanders superior alternative opportunities.
By stripping away vanity metrics, establishing rigorous industry-specific benchmarks, and maintaining the discipline to pull the plug on underperforming ventures, organizations and individual investors alike can protect their capital and ensure every dollar works toward sustainable, high-impact growth.