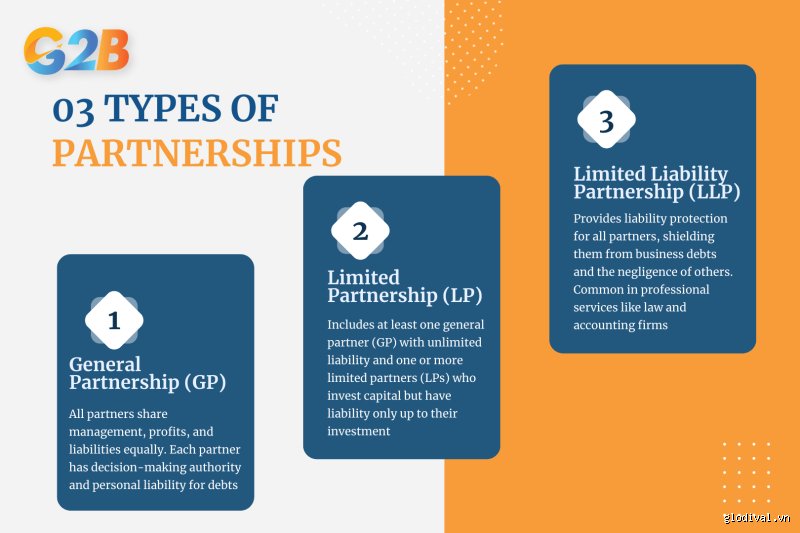
Navigating structural nuances: The Limited Partnership (LP)
An LP cannot exist with a homogenous group of owners. By definition, it requires a minimum of two distinct classes of participants:
The General Partner (GP): Much like members of a standard general partnership, the GP in an LP assumes total, unlimited personal liability for the enterprise's debts, obligations, and legal missteps. They retain absolute control over daily operations, strategic choices, and administrative execution.
The Limited Partner (LP): Often colloquially referred to as "silent partners" in casual conversation, limited partners function primarily as capital contributors. They inject funds, property, or expertise into the venture expecting a return on investment, but they are legally barred from participating in day-to-day management. In exchange for relinquishing operational control, their personal financial exposure is strictly capped at the amount they have invested or promised to invest.
Strategic application of Limited Partnerships
The LP structure shines brightly in specific capital-intensive industries, most notably real estate development, venture capital funds, film production, and oil and gas exploration.
Imagine a large commercial real estate project. An experienced developer acts as the General Partner, orchestrating zoning permits, architectural design, contractor relations, and daily site work. However, the developer lacks the multi-million-dollar capital required to break ground. They pitch the project to external investors, wealthy individuals or institutions, who are willing to supply the capital but have zero interest in managing construction crews or negotiating leases. These investors step in as Limited Partners.
From a risk-management perspective, the LP structure offers a brilliant compromise. The investors' personal assets (homes, savings accounts, other business ventures) are legally shielded from lawsuits or bankruptcies originating from the project. Conversely, the general partner maintains the autonomy they require to steer the ship without being gridlocked by a committee of investors.
Formalities and registration requirements
Unlike a casual general partnership that can form implicitly through behavior, a Limited Partnership is a creature of statute. Because it shields personal assets through limited liability, state governments mandate a formal registration process. Founders must file a certificate of limited partnership with the appropriate state authority, pay filing fees, and draft a comprehensive written partnership agreement. This agreement must explicitly delineate the financial contributions, profit-distribution percentages, and boundaries between general and limited roles to prevent future litigation.
Modern professional protection: The Limited Liability Partnership (LLP)
As commerce evolved, traditional partnerships proved risky for service-oriented professionals who worked closely together but wanted protection from each other’s professional negligence. This gave rise to the third primary model: the Limited Liability Partnership (LLP).
Originally popularized by law firms, accounting practices, medical groups, and architectural agencies, the LLP provides a hybrid shield that combines the internal democratic management of a general partnership with varying degrees of liability protection.
How Liability works in an LLP
The defining characteristic of an LLP is how it handles professional malpractice and internal liability. In a standard general partnership, if Partner A commits professional negligence or medical malpractice, Partner B’s personal assets can be seized to pay off the resulting judgment.
An LLP alters this harsh reality:
Protection from Peer Malpractice: If a partner in an LLP makes a professional error, commits negligence, or faces a malpractice suit, the other partners are generally shielded from personal liability. Their personal savings and homes remain safe; only the assets of the offending partner and the general assets of the business itself are exposed.
Retained Personal Liability for Own Actions: Crucially, an LLP does not grant total immunity. A partner is always fully responsible for their own personal negligence or wrongful acts. Partners remain personally liable for ordinary commercial debts of the business, such as office leases, utility bills, or general bank loans, depending heavily on the specific statutes of the state or jurisdiction in which the LLP is registered.
+-----------------------------------------------------------------+
| LLP LIABILITY STRUCTURE |
+---------------------------------+-------------------------------+
| Partner A (Negligent Actor) | Partner B (Innocent Peer) |
| - Personally liable for error | - Protected from peer error |
| - Business assets exposed | - Personal assets shielded |
+---------------------------------+-------------------------------+
Operational equality and registration
Unlike Limited Partnerships, which create a rift between active managers and passive investors, an LLP assumes that all partners have the right to participate in the day-to-day management of the enterprise. Everyone shares equal management authority unless specified otherwise in the partnership agreement.
Forming an LLP requires strict adherence to state or national regulatory bodies. Many jurisdictions restrict LLPs exclusively to licensed professionals (such as certified public accountants, attorneys, and physicians). Founders must file formal registration documents, pay annual maintenance fees, maintain required professional liability insurance (malpractice insurance), and ensure the business name properly reflects its legal designation (e.g., "Smith & Jones, LLP").
Comparative evaluation matrix
To synthesize these structural options, stakeholders must weigh operational control against legal vulnerability. Choosing the incorrect structure can expose personal nest eggs or choke a business of essential capital.
| Feature | General Partnership (GP) | Limited Partnership (LP) | Limited Liability Partnership (LLP) |
|---|---|---|---|
| Primary Purpose | Simple shared ventures | Raising passive capital | Protecting professionals from peer liability |
| Partner Roles | All general partners | General Partner(s) + Limited Partner(s) | All partners hold equal status/rights |
| Management Control | Shared equally by default | Restricted to General Partner(s) | Shared by all partners |
| Personal Liability | Unlimited for all partners | Unlimited for GPs; Capped for LPs | Shielded from peer malpractice; exposed to own actions |
| Formation Complexity | Lowest (can be informal) | Moderate to High (State filing required) | Moderate to High (State registration + licensing rules) |
| Tax Treatment | Pass-through taxation | Pass-through taxation | Pass-through taxation |
Tax implications and Pass-Through mechanics
A unifying characteristic across all three primary partnership types is their treatment under federal, state, and local tax codes. Partnerships generally enjoy pass-through taxation (also known as transparent taxation).
Unlike C-Corporations, which face "double taxation" (paying corporate income tax on profits, followed by individual income tax on shareholder dividends), a partnership as an entity does not pay federal income tax. Instead, the business files an informational tax return (such as IRS Form 1065 in the United States) detailing total revenues, deductions, gains, and losses.
Profits and losses flow directly through the business to the individual partners proportional to their ownership interest or partnership agreement allocations. Each partner receives a Schedule K-1 outlining their specific share of the earnings, which they must then report on their personal income tax returns.
While this avoids corporate-level taxation, it introduces certain considerations:
Self-Employment Tax: General partners and LLP members who actively participate in the business are typically subject to self-employment taxes on their distributive share of income, covering Social Security and Medicare obligations.
Tax on Paper Profits: Partners can be taxed on their allocated share of business profits even if those earnings were retained within the company to fund future growth rather than distributed directly as cash dividends.
Crucial steps in drafting a Partnership Agreement
Regardless of whether founders select a General Partnership, a Limited Partnership, or a Limited Liability Partnership, operating without a comprehensive, legally binding Partnership Agreement is one of the most perilous mistakes an entrepreneur can make. Relying strictly on default state laws governing partnerships often leads to chaotic outcomes if disputes arise.
An exhaustive partnership agreement should explicitly address and codify the following core provisions:
Capital Contributions: Detailed accounting of what each partner contributes initially (cash, real estate, intellectual property, machinery) and protocols for future capital calls if the business requires additional funding.
Profit and Loss Allocation: Clear mathematical formulas determining how earnings and debts are distributed. Profits do not automatically split 50/50; they can be tied to performance metrics, hours worked, or capital percentages.
Decision-Making and Voting Authority: Defining whether major operational changes require unanimous consent, a simple majority, or executive fiat from a designated managing partner.
Dispute Resolution Mechanisms: Outlining steps to take if partners reach an unresolvable deadlock. This often includes mandatory mediation, binding arbitration, or structured buyout provisions before resorting to expensive public litigation.
Exit Strategies and Dissolution: Clear guidelines for what happens if a partner wishes to retire, becomes disabled, files for personal bankruptcy, or passes away. It should include buy-sell clauses, valuation formulas for ownership stakes, and rules regarding the right of first refusal for remaining partners.
Conclusion
Selecting the appropriate partnership structure requires an objective, clear-eyed evaluation of risk tolerance, financial goals, and operational control.
Choose a General Partnership only when trust is absolute, operational simplicity is paramount, and the risks of liability are low.
Opt for a Limited Partnership when you require outside capital from passive investors while retaining absolute managerial authority.
Establish a Limited Liability Partnership when practicing a licensed profession where safeguarding personal assets from a partner's professional error is vital.
By balancing these legal frameworks with expert counsel and a meticulously written partnership agreement, business owners can construct a resilient foundation for sustainable growth and long-term commercial success.