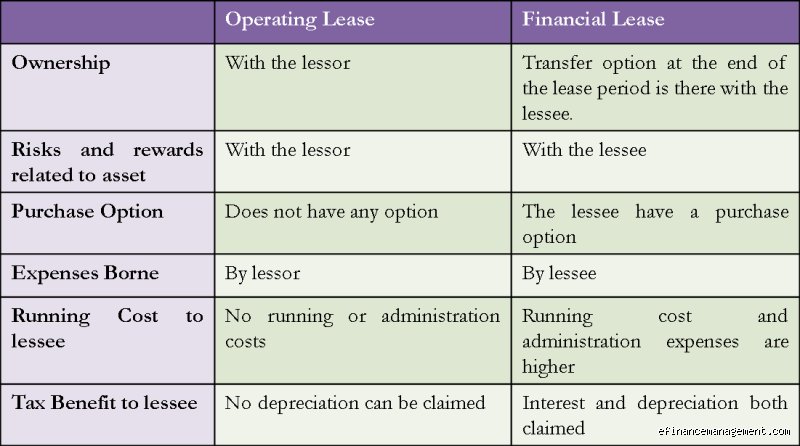
Both operating and finance leases must be recognised on the balance sheet as a right‑of‑use asset and a lease liability. The distinction lies in how they are subsequently reported on the income statement and cash‑flow statement.
What is a lease under the new standards?
A contract is a lease if it gives the lessee the right to control the use of an identified asset for a period in exchange for consideration. The asset must be identifiable and the lessee must have the right to obtain most economic benefits and direct the asset’s use.
When can a lease be excluded?
Leases with a term of 12 months or less, or those for low‑value assets (under IFRS 16), may be exempted. Exempted leases are expensed straight‑line and do not appear on the balance sheet.
How are leases classified?
Both standards use a set of indicators. A lease is classified as a finance lease if any of the following apply:
- Ownership is transferred to the lessee.
- The lessee has a purchase option it is reasonably certain to exercise.
- The lease term covers a major part of the asset’s remaining economic life.
- The present value of lease payments equals or exceeds substantially all of the asset’s fair value.
- The asset is specialized and has no alternative use for the lessor.
Initial recognition and measurement
At commencement the lessee records:
- A right‑of‑use (ROU) asset equal to the lease liability plus any initial direct costs and restoration obligations.
- A lease liability measured at the present value of future lease payments, discounted at the implicit rate or the lessee’s incremental borrowing rate.
Subsequent accounting for finance leases
Finance leases are amortised. The lease liability is reduced by principal payments and increased by interest expense. The ROU asset is depreciated over the lease term or the asset’s useful life, whichever is shorter.
Subsequent accounting for operating leases
Operating leases are expensed on a straight‑line basis over the lease term. The lease liability is reduced only by the lease payments; the ROU asset is not depreciated. Cash‑flow statements show lease payments as operating cash outflows.
Summary table
| Feature | Finance lease | Operating lease |
|---|---|---|
| Balance‑sheet recognition | ||
| Income‑statement treatment | Interest + depreciation | Straight‑line expense |
| Cash‑flow classification | Financing | Operating |