The evolution of lease Accounting and why IFRS 16 was introduced
For decades prior to the adoption of IFRS 16, corporate balance sheets offered a distorted picture of lease commitments. Under previous standards such as IAS 17, companies utilized a binary classification system that categorized leases either as finance leases or operating leases. Finance leases were capitalized, meaning they appeared on the balance sheet as assets with corresponding liabilities. Conversely, operating leases were treated much like traditional rental agreements. Lease payments were expensed directly through the income statement on a straight-line basis, while the underlying leased asset and its corresponding liability remained entirely off the balance sheet.
This off-balance-sheet accounting treatment created a significant blind spot for investors, analysts, and creditors. Companies could acquire substantial operational assets—such as retail store networks, commercial fleets, office buildings, and heavy machinery—through long-term lease arrangements without reporting the associated debt obligations on their balance sheets. Consequently, financial leverage ratios appeared deceptively favorable, masking the true financial risk carried by the organization. Regulatory bodies and standard-setters recognized that this lack of transparency undermined comparability between companies that purchased assets using debt and those that leased them.
The International Accounting Standards Board addressed this discrepancy by developing IFRS 16, which became effective for annual reporting periods beginning on or after January 1, 2019. The fundamental philosophy behind the standard is that every lease conveys a right to control the use of an identified asset for a period of time in exchange for consideration. Therefore, gaining control of an asset through a lease transaction is economically similar to purchasing it with borrowed funds. Bringing these commitments onto the balance sheet ensures that financial statements reflect economic reality rather than legal form, establishing a level playing field for global financial markets.
Core principles of IFRS 16: Right-of-Use Assets and lease liabilities
At the heart of IFRS 16 lies a single accounting model that applies to almost all lease agreements. Under this model, a lessee is required to recognize two primary items on the balance sheet at the commencement date of the lease: a right-of-use asset and a lease liability. Understanding how these two components are calculated and managed is essential for anyone seeking to master the mechanics of modern lease accounting.
The lease liability is measured initially at the present value of the lease payments that remain unpaid at that date. Calculating this present value requires determining the lease term, identifying the scheduled lease payments, and selecting an appropriate discount rate. The lease term includes the non-cancellable period of the lease, alongside periods covered by an option to extend the lease if the lessee is reasonably certain to exercise that option. Payment streams typically include fixed payments, variable lease payments that depend on an index or a rate, amounts expected to be payable under residual value guarantees, and the exercise price of a purchase option if the lessee is reasonably certain to exercise it. The discount rate used is generally the interest rate implicit in the lease, or if that rate cannot be readily determined, the lessee's incremental borrowing rate.
Simultaneously, the right-of-use asset is measured at cost. This initial cost comprises the amount of the initial measurement of the lease liability, any lease payments made at or before the commencement date less any lease incentives received, any initial direct costs incurred by the lessee, and an estimate of costs to be incurred in dismantling and removing the underlying asset or restoring the site on which it is located. Following initial recognition, the right-of-use asset is depreciated over the shorter of the lease term and the useful life of the underlying asset, unless ownership transfers at the end of the lease. Meanwhile, the lease liability is adjusted over time to reflect interest accruals and lease payments made, mirroring standard loan amortization schedules.
Operating leases versus finance leases under the new rules
A common point of confusion during the transition to IFRS 16 involves how the distinction between operating and finance leases applies to lessees. For lessors, the traditional dual accounting model remains largely unchanged; lessors continue to classify leases as either operating or finance based on whether the risks and rewards incidental to ownership are transferred.
However, for lessees, the distinction has vanished from the balance sheet. All lessee leases are now treated similarly to historical finance leases upon initial recognition, meaning they all result in the creation of a right-of-use asset and a lease liability. Despite this unified balance sheet treatment, the impact on the income statement can still differ depending on the nature of the underlying asset and the specific terms of the agreement.
For leases that would have previously qualified as finance leases under older standards, the income statement presentation remains consistent: depreciation expense is recognized on the right-of-use asset, and interest expense is recognized on the lease liability. This creates a front-loaded expense profile, where total expenses are higher in the early years of the lease due to declining interest charges over time.
For leases that would have previously been classified as operating leases, the income statement expense profile shifts dramatically. Instead of a single, straight-line operating lease expense categorized entirely within operating expenses, the lessee now records depreciation on the right-of-use asset (typically within operating expenses) and interest expense on the lease liability (categorized within financing costs). Consequently, operating profit (EBIT) and EBITDA tend to increase under IFRS 16 because the rental expense is split into depreciation and interest, shifting expenses down the income statement.
Practical steps for implementing IFRS 16 in your organization
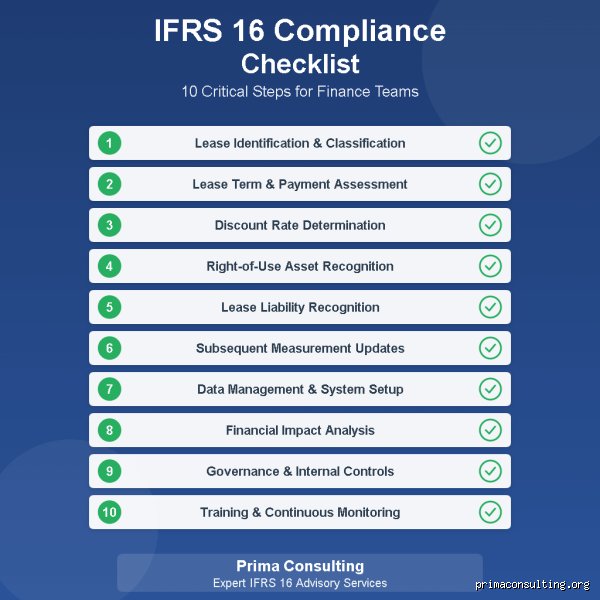
Implementing IFRS 16 requires a systematic, cross-functional approach involving accounting, legal, procurement, and information technology teams. Organizations must begin by conducting a comprehensive contract review to identify all agreements that contain leases, even those embedded within service contracts or IT agreements. Under IFRS 16, a contract contains a lease if it conveys the right to control the use of an identified asset for a period of time in exchange for consideration.
Once all lease contracts are identified and cataloged, data extraction becomes the priority. Key data points, such as commencement dates, expiration dates, renewal options, payment frequencies, escalation clauses, and applicable discount rates, must be gathered from disparate sources and centralized. Many organizations find that managing this volume of data manually through spreadsheets is unsustainable, prompting investments in specialized lease accounting software solutions designed to handle ongoing calculations, journal entries, and note disclosures automatically.
Following data centralization, companies must establish robust internal controls and accounting policies to govern future lease modifications, reassessments, and impairments. Regular audits of lease data ensure compliance and accuracy, preventing reporting errors that could impact financial statement integrity. Training finance personnel on the mechanics of discount rate selection, liability remeasurement, and right-of-use asset depreciation guarantees sustained operational readiness.
Impact on financial Ratios and key performance indicators
The adoption of IFRS 16 fundamentally alters a company's financial profile, impacting key performance indicators and financial ratios used by lenders, investors, and management. Because liabilities increase significantly with the addition of lease obligations, solvency ratios such as the debt-to-equity ratio deteriorate, reflecting higher financial leverage.
At the same time, return on assets (ROA) tends to decrease because total assets expand due to the capitalization of right-of-use assets, while net income may experience minor fluctuations depending on the maturity profile of the company's lease portfolio. Conversely, operating margins and EBITDA improve because operating lease rentals are replaced by depreciation and interest expenses, which sit outside traditional operating profit calculations. Financial analysts must carefully adjust their evaluation frameworks to account for these structural shifts, ensuring that comparative analyses across different industries and reporting periods remain accurate and meaningful.
Uncovering the hidden complexities: Lease modifications and remeasurements
While most finance professionals understand the baseline mechanics of IFRS 16, bringing operating leases onto the balance sheet as a right-of-use (ROU) asset and a corresponding lease liability, few anticipate the operational friction caused by routine lease modifications. This is perhaps one of the most overlooked and underestimated aspects of the standard. Under previous rules (IAS 17), amending a lease often meant a simple footnote disclosure or a minor prospective adjustment to rent expense. Under IFRS 16, almost every amendment, whether it is expanding square footage, shortening a term, or altering rental payments, triggers a complex recalculation of both the ROU asset and the lease liability.
I’ve seen firsthand how mid-sized companies treat lease modifications as administrative afterthoughts, only to face severe audit adjustments during year-end close. When I tried to help a growing retail client untangle a series of mid-term store expansions and partial surrenders across fifty locations, we discovered that simple handshake agreements documented via email amendments required deep accounting re-evaluations. Under IFRS 16, a modification that is not a separate lease requires the lessee to remeasure the lease liability using a revised discount rate at the effective date of the modification, while simultaneously adjusting the ROU asset. If the modification decreases the scope of the lease, a proportional or complete termination must be recognized, immediately impacting the income statement with a gain or loss.
Failing to track these changes in real-time creates a compounding error that distorts asset valuations and operating metrics. It requires cross-functional collaboration between real estate, legal, and finance teams to ensure that every contract tweak, no matter how minor, flows seamlessly into the lease accounting ledger.
The discount rate dilemma: Finding the true incremental Borrowing rate
Another subtle yet critical challenge under IFRS 16 is determining the appropriate discount rate. The standard dictates that entities should use the interest rate implicit in the lease if that rate can be readily determined. However, in practice, lessors rarely disclose this rate, forcing lessees to rely on their incremental borrowing rate (IBR).
Calculating an accurate IBR is far more nuanced than simply pulling your corporate revolving credit facility rate. The IBR must reflect the specific asset class, the lease term, the currency, and the economic environment in which the lease is held.
Asset-Specific Risks: A warehouse lease in a developing market carries a different risk profile and financing cost than a standard office lease in a major metropolitan hub.
Matching Terms: The borrowing rate must align with the exact duration of the lease contract. Applying a short-term borrowing rate to a fifteen-year real estate lease fundamentally misstates the present value of the liability.
Secured vs. Unsecured Borrowing: Since ROU assets represent secured obligations, the IBR should theoretically reflect a secured borrowing rate rather than a general corporate unsecured debt yield.
When companies rely on a single, blanket corporate discount rate for all leases across the organization, auditors frequently push back. Establishing a robust matrix for discount rates requires close coordination with treasury departments to model synthetic borrowing rates that accurately mirror what the entity would pay to borrow over a similar term to obtain an asset of similar value.
Beyond the balance sheet: The ripple effect on financial Ratios and covenants
The introduction of IFRS 16 fundamentally reshapes financial statements, shifting expenses from operating expenses (rent) to depreciation and interest. While operating income (EBIT) and EBITDA generally improve because rental expense is replaced by depreciation and interest, the balance sheet swells with debt.
This structural shift has profound implications for financial covenants and lending relationships.
Leverage Ratios: Debt-to-equity and debt-to-EBITDA ratios increase significantly. For companies with substantial retail or logistics footprints, this can push them perilously close to breaching debt covenants that were originally negotiated under legacy accounting frameworks.
Return on Assets (ROA): Because total assets increase due to the recognition of ROU assets while net income remains relatively stable in the early years of a lease, ROA typically drops.
Cash Flow Presentation: While total cash flow remains unaffected, the classification changes. The principal portion of lease payments moves from operating cash flows to financing cash flows, enhancing operating cash flow metrics while dampening financing cash flows.
Forward-looking treasury teams proactively engage with lenders well in advance of major lease portfolios expanding, negotiating covenant definitions (often termed "frozen GAAP" or covenant modifications) to ensure that accounting changes do not inadvertently trigger technical defaults.
Practical takeaways for ongoing compliance
Navigating IFRS 16 successfully requires shifting mindset from a compliance checkbox to an ongoing operational process. Because leasing is inherently dynamic, with renewals, terminations, and index-linked escalations occurring regularly, static spreadsheets quickly become obsolete. Organizations must implement dedicated lease management software or robust internal controls that link real estate operations directly to general ledger accounting. By establishing clear governance protocols, maintaining meticulous audit trails for every lease modification, and refining discount rate methodologies, finance leaders can transform IFRS 16 from a recurring compliance burden into a source of strategic clarity regarding their long-term commitments.
How do index-based or variable lease payments impact the initial measurement of the lease liability under IFRS 16?
Under IFRS 16, lease liabilities are initially measured at the present value of lease payments that are not paid at the commencement date, which explicitly includes variable lease payments that depend on an index or a rate (such as consumer price index adjustments). However, future variable payments tied to performance or usage (such as a percentage of store sales) are excluded from the initial liability and are instead expensed as incurred in the period in which the triggering event occurs. When index-linked payments change subsequent to commencement, the lease liability is remeasured only when the cash flows change due to an adjustment in the reference index, requiring a corresponding adjustment to the right-of-use asset.