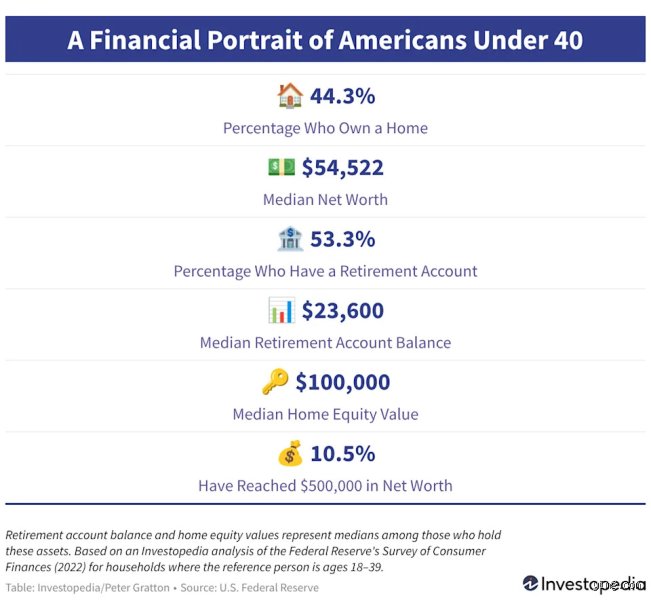
To evaluate how many Americans hold portfolios exceeding five hundred thousand dollars in value, analysts look at both broad participation rates and the steep curve of asset concentration. Approximately fifty to sixty percent of American families own some form of stock, meaning equity ownership is no longer confined exclusively to the highest income brackets. However, crossing the threshold into a portfolio worth more than half a million dollars places a household significantly higher up the wealth distribution curve. Economic surveys indicate that roughly thirty percent of the population maintains stock holdings valued above this milestone during periods of robust market performance, though this proportion fluctuates alongside broader macroeconomic shifts, asset valuations, and market cycles.
The structural mechanics behind how households accumulate such substantial equity holdings usually involve a combination of long term compounding, real estate equity conversion, inheritance, and sustained high saving rates over decades. Most middle class participants accumulate assets primarily through tax advantaged vehicles like 401(k) accounts or individual retirement arrangements. Over a working lifetime spanning thirty or forty years, regular contributions combined with historical equity premiums can push a dedicated saver past the half-million-dollar mark. Even so, the median value of stock holdings for typical American families sits far below that figure, illustrating that while thirty percent may achieve the milestone, the vast bulk of total market capitalization remains concentrated among upper income deciles.
Examining the generational and demographic dimensions of large stock portfolios reveals further concentration. Older cohorts, particularly baby boomers and members of the silent generation, hold the lion's share of high value accounts because they have had more time for their assets to compound and typically peak in their peak earning years. Younger demographics, while increasingly participating in equity markets early through digital brokerages and workplace plans, generally show lower median balances simply due to time horizons. Racial and geographic disparities also play a role in wealth accumulation patterns, mirroring broader economic inequalities across the country.
The Demographic and socioeconomic breakdown
While a macro-level statistic like 30% of the U.S. population holding stock portfolios exceeding $500,000 offers a striking snapshot of modern wealth accumulation, averages and top-line figures can mask deep structural disparities. Stock market participation and capital depth are heavily stratified by age, income, education, and generational wealth transfer.
To fully understand who commands these high-value portfolios, we must examine how demographic slices intersect with the equity market:
Age and Time Horizon: Wealth is fundamentally a function of compounding over time. Younger cohorts (ages 18–29) typically record lower aggregate portfolio values due to shorter accumulation windows, whereas individuals in the 50–64 age bracket show the highest concentration of mature retirement accounts, matching peak earning years.
Educational Attainment: Data from institutions like Gallup consistently highlight that college graduates own stocks at vastly higher rates (around 84% compared to roughly 42% for those with a high school education or less). Higher educational attainment strongly correlates with professional career tracks that provide matching 401(k) plans and higher disposable incomes.
Income Brackets: The chasm between upper-income households and lower-income households remains wide. Approximately 87% of upper-income Americans ($100k+ annual income) participate in the stock market, often holding individual equities and substantial fund shares. Conversely, lower-income brackets find their capital absorbed entirely by non-discretionary living expenses, severely limiting stock market exposure.
| Demographic Variable | General Stock Ownership Rate | Estimated Share Reaching High-Value Portfolios ($500K+) |
|---|---|---|
| Upper Income ($100k+) | ~87% | Very High (Concentrated among top wealth deciles) |
| Middle Income ($50k–$99.9k) | ~71% | Moderate (Typically tied to long-term workplace retirement plans) |
| Lower Income (<$50k) | ~28% | Negligible |
| College Graduates | ~84% | High |
How Americans cross the 0,000 milestone: Vehicles and tactics
Reaching a $500,000 equity portfolio is rarely achieved through speculative trading or overnight wins. Instead, for the vast majority of everyday Americans, this threshold is crossed through systemic, automated wealth-building mechanisms embedded in the modern financial architecture.
1. Workplace Retirement Plans (401(k) and 403(b))
The institutional retirement system acts as the primary engine driving middle- and upper-middle-class Americans past the half-million-dollar mark. Automatic payroll deductions combined with employer matching contributions force a disciplined savings cadence. Over a 20- to 30-year career, an employee contributing 10% to 15% of a median salary into broad-market index funds or target-date funds naturally breaches the $500,000 valuation threshold purely through the math of compounding interest.
2. Tax-Advantaged Individual Accounts (IRAs and Roth IRAs)
Supplementing workplace plans with Individual Retirement Accounts allows savers to accelerate portfolio growth shelter from heavy annual capital gains taxes. The flexibility to allocate these funds into low-cost Standard & Poor's 500 or total stock market index funds removes emotional decision-making, ensuring that portfolios track the long-term upward trajectory of corporate America.
3. Real estate synergy
Interestingly, a significant portion of individuals with large stock portfolios also benefit from homeownership equity. Real estate appreciation and fixed-rate mortgage amortization free up disposable income over time, allowing households to pivot cash flows directly into taxable brokerage accounts or maximize retirement contributions.
Historical context and macroeconomic pressures
The percentage of Americans holding substantial stock portfolios is not static; it fluctuates in tandem with macroeconomic cycles, interest rate regimes, and secular bull or bear markets.
Following major market downturns—such as the 2008 financial crisis or the inflationary shocks of the early 2020s—total household wealth metrics experienced temporary contractions. However, extended secular bull markets, driven heavily by technological innovation and corporate earnings growth, have pushed a greater share of household assets into equities.
The Shift from Pensions to Defined Contribution Plans: Decades ago, corporate defined-benefit pensions shielded workers from market volatility. Today’s shift toward defined-contribution plans (like 401ks) places the burden of investing directly on the individual, transforming a larger segment of the populace into active equity holders.
Inflation and Nominal vs. Real Wealth: A $500,000 portfolio today possesses different purchasing power than it did twenty years ago. Inflation erodes the real value of money, meaning that crossing the half-million-dollar mark is increasingly becoming a baseline target for a secure retirement rather than an indicator of ultra-high-net-worth status.
Important Note: Portfolio valuations shift rapidly based on daily market sentiment. A household holding $520,000 in equities during a market peak can easily see that figure drop below $450,000 during a market correction, demonstrating that asset count volatility affects the exact percentage of Americans above this threshold at any given calendar month.
Strategic lessons for Long-Term Wealth building
Analyzing the mechanics behind how millions of Americans secure a $500,000+ stock portfolio reveals actionable principles that can guide any aspiring investor:
Prioritize Consistency Over Timing: Trying to time market tops and bottoms consistently underperforms a strategy of regular, automated dollar-cost averaging into broad-market funds.
Minimize Fee Drag: High management expense ratios and advisory fees eat away at exponential growth over decades. Low-cost index investing preserves capital for compounding.
Leverage Tax Structures First: Maximize employer matches and tax-advantaged accounts before deploying capital into taxable brokerage accounts to optimize net returns.
Maintain a Long Time Horizon: Equity markets require patience. Short-term volatility is the price of admission for long-term capital appreciation.
Conclusion
The reality that roughly 30% of the U.S. population maintains a stock portfolio valued above $500,000 reflects both the incredible wealth-generating capacity of the American capital markets and the widening gap between active investors and non-participants. While reaching this milestone requires a combination of sustained income, disciplined saving habits, and favorable market conditions, the structural pathways, principally employer-sponsored retirement vehicles and low-cost index funds, remain accessible to a broad swath of the workforce. As economic landscapes evolve, understanding these distributions helps demystify what it truly takes to build long-term financial security in the modern economy.