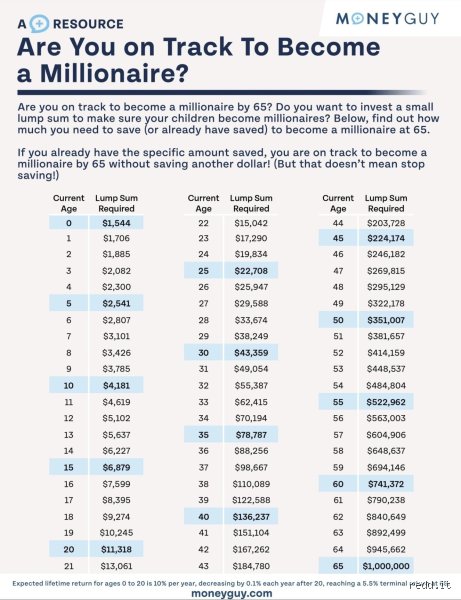
Among the various savings benchmarks, committing $2,000 a month represents a formidable middle ground. It is an aggressive, highly intentional target—roughly $24,000 a year—that demands a deliberate lifestyle design for most households, yet it sits well within the realm of possibility for mid-career professionals, dual-income households, or dedicated frugalists.
So, how long does it actually take to transform $2,000 in monthly contributions into a cool $1,000,000?
The short answer: Between 16 and 22 years, depending heavily on your asset allocation, macroeconomic conditions, and average market returns. But the long answer is far more fascinating, revealing the hidden psychological hurdles, the mechanics of exponential growth, and the structural realities of market volatility that every aspiring investor must navigate.
The mathematics of ,000 a month: Breaking down the Growth Engine
To understand the timeline, we must first examine the two primary fuel sources of wealth accumulation: principal contributions and compound interest.
If you were to stuff $2,000 a month into a mattress or a zero-yield cash box, it would take you exactly 41 years and 8 months to accumulate $1,000,000 purely through raw savings ($24,000 per year × imes× 41.67 years = $1,000,000).
Fortunately, capital is meant to be deployed. When you channel that $2,000 monthly contribution into productive market vehicles, such as broad-market index funds, equities, or diversified asset portfolios, your money begins to generate its own earnings. Those earnings, in turn, begin generating their own earnings. This compounding loop is what compresses a 41-year slog into a timeline of under two decades.
Let’s model how this plays out across three standard historical return scenarios, assuming zero starting balance and monthly compounding contributions:
Scenario 1: The Conservative defensive Portfolio (5% Annual Return)
Asset Mix: Heavy allocation to short-duration bonds, fixed income, and dividend stalwarts.
Monthly Contribution: $2,000
Timeline to $1 Million: ~23.5 Years (approx. 282 months)
Total Principal Invested: ~$564,000
Total Interest Earned: ~$436,000
Takeaway: While safer against steep drawdowns, a conservative posture forces you to work significantly longer and rely heavily on your own cash contributions, as interest accounts for less than half of your final net worth.
Scenario 2: The moderate Balanced Portfolio (7% to 8% Annual Return)
Asset Mix: Standard global stock and bond mix (e.g., a traditional 80/20 equity-to-fixed-income split or balanced index strategy).
Monthly Contribution: $2,000
Timeline to $1 Million: ~18.5 to 20 Years (approx. 222 to 240 months)
Total Principal Invested: ~$444,000 to $480,000
Total Interest Earned: ~$520,000 to $556,000
Takeaway: This represents the historical baseline expectation for disciplined, diversified long-term investors. Here, the wealth generated by the market officially eclipses the cash you physically saved from your paycheck.
Scenario 3: The Aggressive Equity Growth Portfolio (10% Annual Return)
Asset Mix: 100% broad-market equity index funds (such as funds tracking the S&P 500 or total US/global stock market).
Monthly Contribution: $2,000
Timeline to $1 Million: ~16 Years (approx. 192 months)
Total Principal Invested: ~$384,000
Total Interest Earned: ~$616,000
Takeaway: Mirroring the long-term historical nominal average of major equity indexes, an aggressive equity approach cuts the timeline down to roughly 16 years. In this scenario, nearly 62% of your millionaire status is funded entirely by compound market returns, while your personal out-of-pocket contributions account for only 38%.
The three phases of the journey: Why the Timeline feels uneven
One of the greatest psychological traps for investors saving $2,000 a month is the non-linear nature of compounding. Human brains are naturally wired to think linearly; we expect progress to occur at a steady, predictable pace. Wealth accumulation, however, behaves like a hockey stick.
Understanding the three distinct phases of this 16-to-22-year journey can save you from premature panic or burnout:
Phase 1: The heavy lifting (Years 1 to 5)
During the first few years, your portfolio growth will feel painfully slow. If you invest $2,000 a month at an 8% return, after 12 months you will have contributed $24,000, and your total balance will sit around $25,000.
The Reality: For the first several years, your monthly contributions drive almost 90% to 95% of your portfolio's movement. A bad month in the stock market might wipe out several months' worth of investment gains.
The Mindset: This is the phase of raw discipline. You are building the foundation, and your primary job is simply maintaining the habit of automation.
Phase 2: The tipping point (Years 6 to 12)
By year seven or eight, something remarkable happens. Your accumulated principal, combined with years of accumulated gains, creates a portfolio large enough that annual market returns begin to rival, and occasionally exceed, your annual contributions.
The Reality: A 10% swing on a $250,000 portfolio is $25,000 in a single year, more than your entire annual out-of-pocket savings rate of $24,000.
The Mindset: This is where motivation shifts. You begin to see the machine working for you. Market volatility becomes larger in dollar terms, but the sheer momentum of compounding cushions the psychological blow.
Phase 3: Exponential velocity (Years 13 to 20+)
In the final stretch toward the million-dollar mark, growth accelerates dramatically. Between years 15 and 20, a moderate portfolio can easily swing by $50,000 to $100,000 in a strong market year.
The Reality: The final $250,000 accumulates exponentially faster than the first $250,000.
The Mindset: Patience pays off entirely here. Trying to time the market or tinker with your allocations during this phase can severely disrupt the velocity of compounding.
(This concludes Part 1 of our expert analysis. In Part 2, we will examine the hidden friction points, such as inflation, taxation, behavioral discipline during market crashes, and how optimizing your savings rate can compress your timeline even further.)
Navigating market realities: Sequence of returns, volatility, and inflation
When mapping out a timeline to a million dollars, looking at a smooth, upward-sloping mathematical curve is comforting, but it can also be dangerously misleading. Real-world financial markets do not move in straight lines. They experience jagged corrections, prolonged bear markets, economic recessions, and euphoric bull runs. This chaotic reality introduces### The Compounding Engine: Why the Timeline Accelerates
When you commit to investing $2,000 every single month, you are deploying $24,000 of principal capital into the market annually. While that in itself is an impressive savings rate, surpassing the median household income in many regions, the true magic of this strategy lies not in your contributions, but in the exponential curve of compounding returns.
To understand how long it takes to reach the coveted millionaire status, financial planners typically look at historical market averages. The broad stock market, represented by indices like the S&P 500, has historically delivered an average annualized return of roughly 10% before inflation, or about 7% to 8% when adjusted for inflation.
Let us examine how this plays out across different return scenarios, assuming you start from a balance of zero and reinvest all dividends.
Scenario analysis: Expected timelines based on Return rates
Depending on your asset allocation, whether you lean into aggressive growth equities, a balanced index fund portfolio, or a more conservative mix of equities and fixed income, your timeline to $1,000,000 will shift.
| Annual Return (Inflation-Adjusted) | Total Principal Invested | Estimated Time to $1,000,000 | Total Interest / Growth Earned |
|---|---|---|---|
| 5% (Conservative Portfolio) | ~$336,000 | ~14 years (168 months) | ~$664,000 |
| 7% (Balanced Index Strategy) | ~$312,000 | ~12.5 years (150 months) | ~$688,000 |
| 10% (Aggressive Equity Growth) | ~$288,000 | ~11 years (132 months) | ~$712,000 |
As the data illustrates, investing $2,000 a month dramatically compresses the timeline compared to smaller monthly contributions. While someone investing $500 a month might take over 25 years to cross the millionaire threshold, the heavy lifting of a $2,000 monthly commitment cuts that timeframe down to roughly 11 to 14 years.
The Power of the "Crossover Point"
One of the most psychologically fascinating aspects of building wealth through a consistent monthly contribution is what finance writer Morgan Housel and other economists call the "crossover point", the moment when your investment returns begin to equal or exceed your annual earned contributions.
In the early years of your $2,000-a-month journey, your net worth growth is driven almost entirely by your own sweat and savings. In Year 1, you contribute $24,000, and market gains might add another $1,000 to $2,000. It can feel slow, almost mechanical.
However, as you cross into Years 7, 8, and 9, something extraordinary happens. A single market correction followed by a recovery can add $50,000, $80,000, or even $100,000 to your portfolio in a single year, more than double your annual out-of-pocket savings.
Years 1 to 5: Your savings rate does 80% of the heavy lifting. The portfolio grows through sheer force of habit and discipline.
Years 6 to 10: Compounding gains start to match your annual contributions. Your money is now working harder than a part-time employee.
Years 11 to 14: Compounding completely takes over. Market fluctuations dwarf your monthly $2,000 deposits, propelling you rapidly toward and past the $1,000,000 mark.
Strategic optimization: How to shave Years off your Timeline
If you want to accelerate this timeline even further and cross the finish line faster, you can implement several advanced wealth-acceleration tactics without necessarily increasing your baseline stress or lifestyle friction.
1. Front-Loading your contributions
Time in the market beats timing the market. If you receive an annual bonus, a tax refund, or a windfall, deploying that capital into your investment vehicle as early in the year as possible allows those dollars more time to compound. Instead of dollar-cost averaging a bonus across twelve months, lump-sum investing historically outperforms because markets trend upward over long horizons.
2. Asset location and tax efficiency
Paying unnecessary taxes is the silent killer of compounding returns. To maximize your $2,000 monthly output, utilize tax-advantaged accounts wherever possible:
Employer-sponsored plans (like a 401(k) or 403(b)): Lower your taxable income today while your money grows tax-deferred or tax-free (Roth options).
Individual Retirement Accounts (IRAs): Max out contributions annually to shield your capital gains from immediate capital gains tax.
Taxable Brokerage Accounts: Utilize low-turnover, tax-efficient index funds or exchange-traded funds (ETFs) to minimize annual dividend distributions that trigger taxable events.
3. Automating the Process
Behavioral finance proves that willpower is a finite resource. If you have to manually transfer $2,000 from your checking account to your brokerage account every month, you will eventually find an excuse to skip a month, spend it on a vacation, or hesitate during a market downturn. Set up full automation: your paycheck hits, the money moves instantly, and you invest blindly regardless of whether the market is up, down, or sideways.
Navigating market volatility: The psychological test
Reaching millionaire status on a 10-to-14-year timeline is not a smooth, linear upward slope. Along the way, you will inevitably experience severe market corrections, bear markets, and macroeconomic panic.
When your portfolio hits $500,000, a routine 20% market correction will wipe $100,000 off your screen in a matter of weeks. For unseasoned investors, watching six figures of paper wealth vanish triggers a fight-or-flight response.
The secret weapon of the successful $2,000-a-month investor is reframing these downturns. When the market drops 20%, your monthly $2,000 contribution suddenly buys index fund shares at a steep 20% discount. You are essentially buying high-quality assets on clearance. Investors who maintain their discipline through bear markets are invariably the ones who accelerate their timeline when the inevitable bull market resumes.
The Ultimate Destination
Investing $2,000 a month is an elite financial habit. It requires sacrifice, budgeting discipline, and career or business income optimization. Yet, the mathematical reality is undeniable: by consistently feeding the compounding engine, you can transform earned income into generational wealth in just over a decade.
The million-dollar mark is not a magic wand that solves all life's problems, but it represents absolute financial autonomy. It is the point where work becomes a choice rather than a survival necessity, and your money finally begins to work harder for you than you ever had to work for it.