Decoding the mechanics of retail investor returns
Financial history is littered with paradoxes. The S&P 500 has historically delivered an annualized return of roughly 10% before inflation over the last century, which explains why generations of advisers push index funds. But individual account statements tell a darker story. The problem is that retail trading volume spikes precisely at market peaks, driven by pure FOMO.
The psychology of buying high and selling low
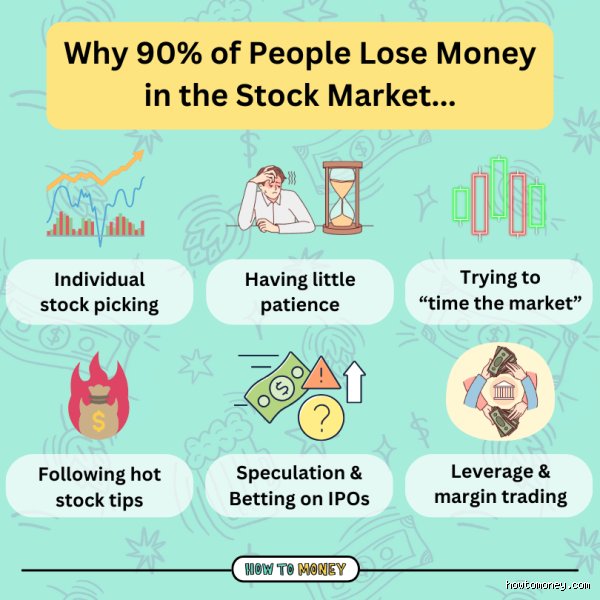
Behavioral finance reveals a grim pattern. When the COVID-19 crash hit in March 2020, retail brokerages like Robinhood saw millions of new accounts open, fueled by stimulus checks and lockdown boredom. Yet, when the Federal Reserve aggressively hiked interest rates in 2022—causing the tech-heavy Nasdaq to plunge over 33%—panic selling erupted. You cannot capture long-term compounding if you bail out at the exact bottom, locking in permanent capital destruction.
The hidden drag of friction costs
Fees quietly eat away at portfolios like termites in a wooden frame. Beyond the visible brokerage commissions, which technically vanished for many apps, investors bleed cash through bid-ask spreads, expense ratios on actively managed mutual funds, and capital gains taxes. As a result, even when a stock goes up, the net take-home pay for the average household shrinks significantly once transaction friction is fully calculated.
The illusion of skill versus random market walk
We love to believe we can outsmart the system. Day trading apps transformed the stock market into a digital casino during the 2021 meme stock frenzy, where names like GameStop surged from single digits to over $480 intraday before crashing back down. Honest assessment: most people treating equities like lottery tickets end up subsidizing institutional algorithms operated by high-frequency trading firms in New Jersey data centers.
The danger of Single-Stock concentration
Diversification protects ignorance, or so the old Wall Street adage goes. Yet, novice traders love sinking their life savings into three or four hyped tech darlings they read about on Reddit or Twitter. When Enron collapsed in 2001 or Silicon Valley Bank imploded in March 2023, undiversified portfolios vaporized overnight. not even close being a safe endeavor when portfolios lack basic asset allocation.
Information asymmetry in modern markets
Information travels instantly, but institutional investors get it faster. Algorithms parse Federal Reserve statements in milliseconds, executing trades before a human can even read the headline. Competing against entities with billions in capital and proprietary analytics tools is like playing chess against a grandmaster while blindfolded.
Passive indexing versus active stock picking
Active management has historically failed to beat a simple index fund over a ten-year horizon. Morningstar data regularly shows that upwards of 80% of active fund managers underperform the S&P 500. If professional portfolio managers with Bloomberg terminals and team analysts can't beat the average, why do casual investors working 9-to-5 jobs think they can do it on their lunch break?
The rise of Low-Cost exchange traded funds
Index funds democratized investing. Vanguard introduced the first retail index fund in 1976, allowing everyday folks to buy a slice of the entire corporate ecosystem for pennies in fees. But even here, human intervention ruins the math. Investors constantly jump between sector ETFs, chasing clean energy one year and artificial intelligence the next, effectively buying high and selling low across entire asset classes.